
AI Startup Radar — Week of 2026-11-04
Global venture funding hit $59 billion in October, driven largely by a record-setting $15.9 billion round for China’s DeepSeek, signaling a massive shift toward AI infrastructure and large-scale model training. This week's highlights include Fal raising $1.3 billion at a $16 billion valuation to meet surging inference demand, and Larridin securing $30 million to help enterprises track AI spending. The dominant theme remains the "picks and shovels" strategy, with investors favoring companies that supply the infrastructure and measurement tools for the AI boom rather than just building new models.
AI Startup Radar — Week of 2026-11-04
Top Funding Rounds
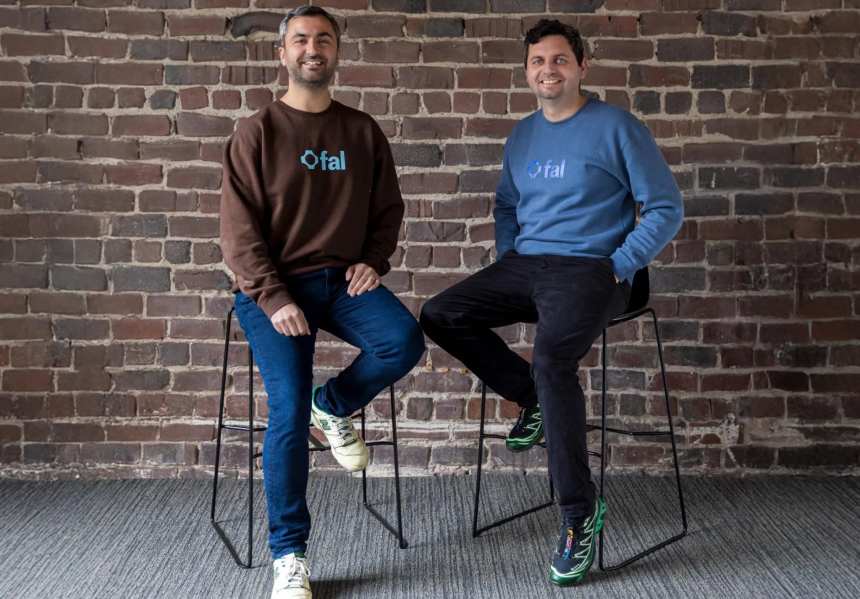
Fal — $1.3 billion Series D (or later)
- What they build: A platform that hosts and runs AI video, image, and audio models, focusing on efficient inference.
- Lead investor: Bessemer Venture Partners, with participation from Nvidia.
- Why it matters: Doubled its valuation to $16 billion, highlighting the critical bottleneck of AI inference capacity as demand for real-time media generation explodes.
Larridin — $30 million Series A
- What they build: A platform helping companies track their AI spending and measure returns on investment.
- Lead investor: Pelion Ventures, with participation from a16z.
- Why it matters: Addresses the growing "AI bill" crisis for corporate America, providing necessary financial visibility into opaque AI costs.
DeepSeek — $15.9 billion Funding Round
- What they build: Large language models and foundational AI capabilities.
- Lead investor: Not specified in brief, but noted as China’s largest startup deal ever.
- Why it matters: This single round accounted for a significant portion of October’s global venture funding, underscoring the scale of capital flowing into Chinese AI labs.
Clinics On Cloud — ₹120 Crore (~$14M) Series B
- What they build: Cloud-based clinic management solutions enhanced with AI features.
- Lead investor: Not specified in brief.
- Why it matters: Part of a broader trend in India where healthcare tech startups are attracting significant capital for digitization and AI integration.
BAG Ventures — $11.3 million Fund I Close
- What they build: A venture fund investing in AI startups across the stack.
- Lead investor: Founded by Google alumni.
- Why it matters: Signals continued interest from operators-turned-investors who understand the technical nuances of enterprise-ready AI products.
Notable Launches and Products
- Google — Announced major October updates including Gemini 4 Argon, Carbon, and Genie 4, focusing on deeper ecosystem integration and model improvements
- PowerPlan — Showcased new AI-powered products and a roadmap for asset lifecycle management at ELEVATE 2026, aimed at helping utilities recover capital faster
- WealthFeed — Added Form 5500 data to its platform, integrating more automated compliance tools for financial advisors
Deals and Partnerships
- Marvell Technology acquires Lumentum Holdings: In a $115 billion all-stock deal, chipmaker Marvell is buying optical components maker Lumentum. This move aims to consolidate AI infrastructure components as investors question industry spending sustainability
- Affle to buy Perion: Affle agreed to acquire Perion for over $420 million, marking a significant consolidation in the ad-tech and AI-driven marketing space
Week in Numbers
| Metric | Value |
|---|---|
| Total disclosed AI funding (Oct Global) | $59 billion |
| Largest round | DeepSeek ($15.9 billion) |
| Most active stage | Late-stage / Growth (implied by mega-rounds) |
| Hottest subsector | AI Infrastructure & Inference |
| Rounds tracked | 10+ notable rounds cited |
Trend Analysis
The market is clearly bifurcating into two distinct investment patterns: massive capital injections into foundation model labs and infrastructure providers, and smaller, targeted rounds for tools that manage or measure AI efficacy. The $15.9 billion round for DeepSeek and the $115 billion Marvell-Lumentum merger highlight that scale is becoming a primary competitive moat in hardware and foundational models. Investors are betting that whoever controls the compute and the optical interconnects will capture the most value in the coming decade.
Conversely, the rise of "AI FinOps" startups like Larridin indicates a maturing enterprise market. As corporations face ballooning AI bills, there is a critical need for transparency and ROI measurement. This shift suggests that while the hype phase of AI is still driving mega-rounds, the operational reality is creating a robust secondary market for governance, tracking, and efficiency tools. The decline in seed-stage deal counts, despite record total funding, confirms that early-stage founders are facing a tougher environment unless they can demonstrate immediate path-to-revenue or unique technical IP.
Geographically, China continues to dominate the headline numbers with DeepSeek’s record-breaking round, but US-based infrastructure plays like Fal remain highly attractive to global VCs. The involvement of Nvidia in Fal’s round further cements the symbiotic relationship between chipmakers and inference platforms, suggesting that the next big wave of value creation lies in optimizing how models are run, not just how they are trained.
What to Watch Next Week
- Regulatory scrutiny on AI M&A: With the Marvell-Lumentum deal closing in, watch for antitrust responses regarding AI hardware consolidation.
- Inference cost trends: As Fal scales, monitor whether inference prices drop, potentially triggering a new wave of application-layer startups.
- Enterprise AI Budget Reviews: Q4 earnings calls may reveal if corporate AI spending is slowing down, which could impact the valuation of "picks and shovels" companies.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
