
AI Startup Radar — Week of 2026-11-07
AI startup funding remains robust with 21 disclosed rounds totaling $2.6 billion in early November, led by Fal’s massive $1.3 billion Series F. The dominant theme is a shift toward AI infrastructure and specialized verticals, with significant capital flowing into inference platforms and enterprise-grade "AI co-worker" solutions.
AI Startup Radar — Week of 2026-11-07
Top Funding Rounds
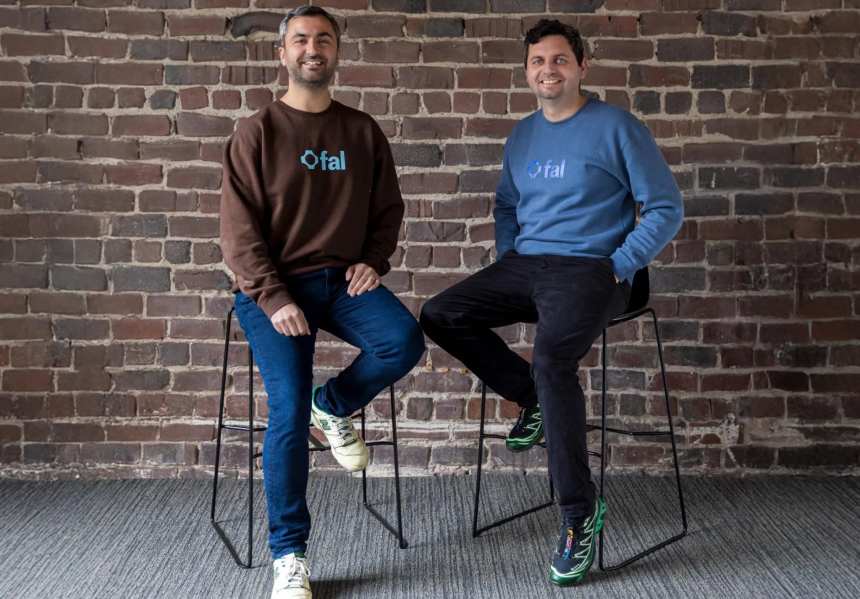
Fal — $1.3 Billion Series F
- What they build: Generative media platform hosting and running AI video, image, and audio models.
- Lead investor: Bessemer Venture Partners, with participation from Nvidia.
- Why it matters: Fal doubled its valuation to $16 billion, signaling that demand for AI inference infrastructure is outpacing model development itself.
Future Secure AI — $115 Million
- What they build: AI "co-workers" designed to handle complex tasks in investment banking, consulting, healthcare, and law.
- Lead investor: Not specified in summary, but focused on enterprise sectors.
- Why it matters: This round highlights the growing market for specialized, high-compliance AI agents that can integrate into regulated industries.

Sand.ai — Funding Amount Not Specified (Leading Nov 5 Activity)
- What they build: AI content generation and corporate data protection infrastructure.
- Lead investor: Not specified in summary.
- Why it matters: As one of the leading deals on November 5, Sand.ai represents the continued focus on making advanced AI commercially viable through security and content generation tools.
Upwind — $400 Million
- What they build: Cybersecurity and AI-driven cloud security solutions.
- Lead investor: Not specified in summary.
- Why it matters: One of the largest rounds for Israeli startups in October, demonstrating the strong investor appetite for AI-enhanced security tools.
Capitolis — $220 Million
- What they build: Fintech infrastructure with AI integration.
- Lead investor: Not specified in summary.
- Why it matters: Highlights the intersection of AI and financial services, a key area for recent capital deployment in the Middle East tech scene.
Notable Launches and Products
- Nothing — Confirmed the December 2026 launch of its first AI-native device, which features no screen and relies on AI interactions, challenging traditional smartphone paradigms.
- Google — Released October AI updates including Gemini 4 Argon, Carbon, and Genie 4, continuing the trend of rapid model iteration and multimodal capabilities.
- AI Leaders Council — Announced the 2026 AI Innovation Awards to recognize companies with proven AI technologies and agents transforming business operations.

Deals and Partnerships
- Marvell Technology & Lumentum Holdings: Marvell’s $115 billion takeover of Lumentum, a data center laser maker, has become the largest equity-based M&A deal of the year (excluding SpaceX-xAI), marking a record for tech sector consolidation.
- Itaú Unibanco & NeoSpace AI: Itaú Unibanco acquired NeoSpace AI for R$ 2.925 billion, focusing on foundational data models to enhance banking AI capabilities.

Week in Numbers
| Metric | Value |
|---|---|
| Total disclosed AI funding (Nov YTD) | $2.6 Billion |
| Largest round | Fal ($1.3 Billion) |
| Most active investors | Bessemer Venture Partners, NVIDIA |
| Hottest subsector | AI Inference & Infrastructure |
| Rounds tracked (Nov YTD) | 21 |
Trend Analysis
The data from early November 2026 indicates a decisive shift from funding model developers to backing the infrastructure that makes those models usable. Fal’s $1.3 billion Series F at a $16 billion valuation underscores this trend; investors are betting that the bottleneck in AI adoption is no longer model capability, but the cost and efficiency of inference. This aligns with broader Q3 2026 data showing AI startups capturing 80% of global venture funding, with infrastructure and vertical-specific applications driving the majority of late-stage capital.
Geographically, while Silicon Valley remains dominant, there is notable activity in Israel, where cybersecurity and fintech AI firms like Upwind and Capitolis are securing large rounds. This suggests that AI applications with immediate, high-value commercial utility—particularly in security and finance—are attracting significant international interest. The involvement of major chipmakers like Nvidia in startup rounds further signals a strategic alignment between hardware providers and software infrastructure layers.
Investor behavior is also becoming more selective regarding "AI co-workers" and agentic workflows. Future Secure AI’s $115 million raise demonstrates that capital is flowing toward AI that can navigate complex, regulated environments like law and healthcare. This marks a maturation of the market, moving beyond generic chatbots to specialized agents that offer measurable ROI in enterprise settings.
What to Watch Next Week
- Nothing's AI Device Pre-orders: As the December launch approaches, pre-order metrics for Nothing’s screen-free AI device will be a key indicator of consumer appetite for non-screen AI interfaces.
- Anthropic IPO Rumors: Recent briefings mention doubts surrounding Anthropic’s potential IPO, which could influence valuation expectations for other frontier AI labs.
- Regulatory Scrutiny on AI Agents: With the rise of "AI co-workers," expect increased regulatory commentary on liability and compliance for autonomous agents in sectors like finance and healthcare.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
