
Chennai Agriculture and Solar Policy Briefing – Sep 26, 2026
REC Power Development and Consultancy (RECPDCL), under India's central government, is pushing to install 11.1MW of rooftop solar across 76 research institutes under the Indian Council of Agricultural Research (ICAR), signaling expanded solar adoption in agriculture. India's solar manufacturing base expanded significantly in the first half of 2026, and falling cell and polysilicon prices from China are expected to impact Indian module prices.
Chennai Agriculture and Solar Policy Briefing – Sep 26, 2026
Administrative Notices and Policy Announcements
-
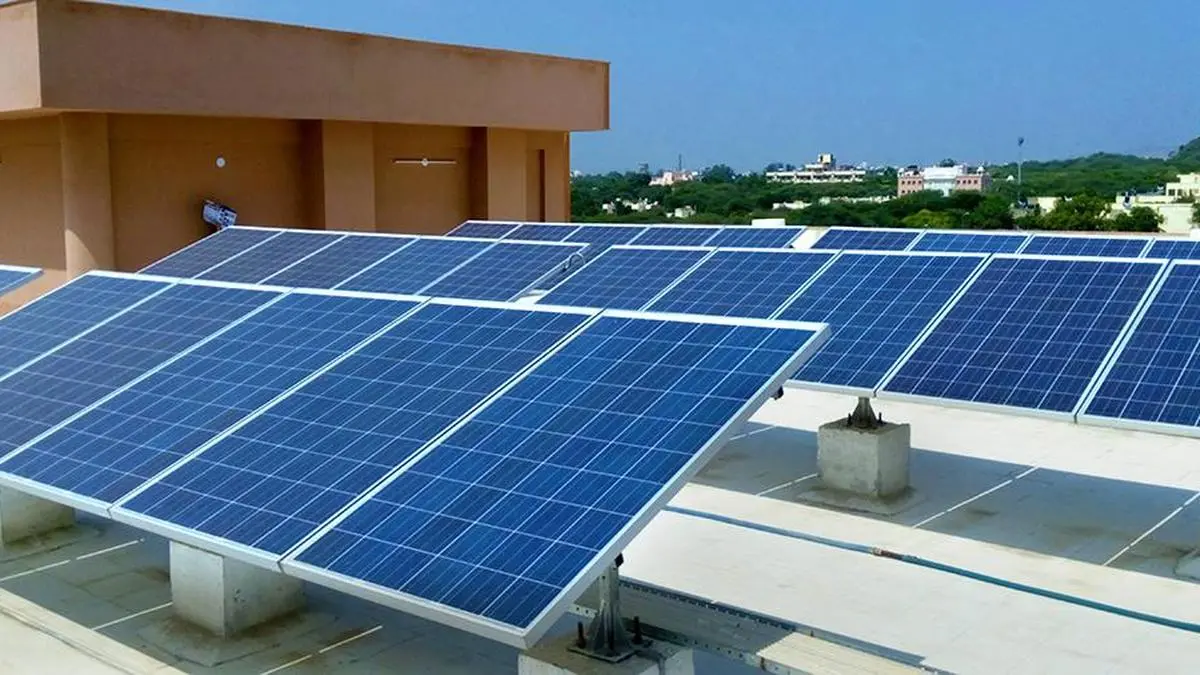
RECPDCL–ICAR Agricultural Solar Project: REC Power Development and Consultancy (RECPDCL), in collaboration with the Indian Council of Agricultural Research (ICAR), is building a total of 11.1MW of rooftop solar power across 76 research institutes spanning 24 states and union territories. Annual power generation is estimated at about 17.3 million kWh. Announced September 25, 2026.
-
CERC Bans REC Trading for Self-Consumed Cogeneration: The Central Electricity Regulatory Commission (CERC) has banned the trading of Renewable Energy Certificates (RECs) generated from self-consumed cogeneration. Reported September 25, 2026.
No new agriculture or solar announcements specific to Chennai (Greater Chennai Corporation) have been identified within the last 24 hours.
Business Review and Market Opportunities
-
Utility-Scale Order Opportunities in Agriculture: The RECPDCL–ICAR project is a rooftop initiative targeting public agricultural institutions, offering clear central government contracting opportunities for EPC contractors whose bidding sites may include ICAR-affiliated entities within Tamil Nadu.
-
Surging Manufacturing Capacity and Accelerated Supply Chain Localization: India added 50.6GW of module manufacturing capacity and 9.7GW of cell manufacturing capacity in the first half of 2026 alone. This indicates improving domestic procurement conditions for solar installation companies in the Chennai region.
-
Cost Reduction Factors: Chinese cell prices have fallen for three consecutive weeks since peaking in late August, and wafer and polysilicon prices have also dropped, easing upstream costs. This could impact Indian module prices and potentially work to the advantage of installers' margins and bidding strategies. However, it may pose challenges to India's push toward domestic ingot-wafer-cell manufacturing transition.
-
Market Impact of REC Trading Restrictions: CERC's ban on REC trading for self-consumed cogeneration alters the supply structure of the REC market, requiring companies that relied on certificate-based revenue models to reassess their financial planning.
Related Tenders and Project Information
No new tender announcements related to agriculture or solar in the Chennai region have been identified within the past 24 hours (since September 25, 2026). Solar tenders in the Tamil Nadu region can be continuously monitored via the tenderdetail.com compilation page, but listings on this page were posted prior to the cutoff and are excluded from this edition. There are no relevant notices.
Macro Context
-
Massive Manufacturing Expansion: India is rapidly expanding its domestic solar manufacturing base, adding 50.6GW of module and 9.7GW of cell production capacity in the first half of 2026.
-
Renewable Energy Market Regulatory Adjustments: Regulatory fine-tuning of the Renewable Energy Certificate system is underway, with the CERC banning REC trading for self-consumed cogeneration.
-
International Price Spillover: The cascading decline in Chinese cell, wafer, and polysilicon prices is impacting Indian module prices and the domestic manufacturing policy environment.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
