
현대건설 사업 동향 및 보증 리스크 모니터링 — 2026-10-19
Hyundai E&C Business Trends and Guarantee Risk Monitoring|8 min read7.9AI quality score — automatically evaluated based on accuracy, depth, and source quality
Hyundai E&C has reached 12.7 trillion won in cumulative orders for the year with the Mokdong Complex 10 reconstruction win, while expanding power and renewable energy cooperation with Australia's AusNet and CIP. Profitability improvement signals are clear, with third-quarter operating profit projected to jump 103% as the housing sector offsets sluggish plant business.
현대건설 사업 동향 및 보증 리스크 모니터링 — 2026-10-19
주요 사업 변화 및 리스크 신호
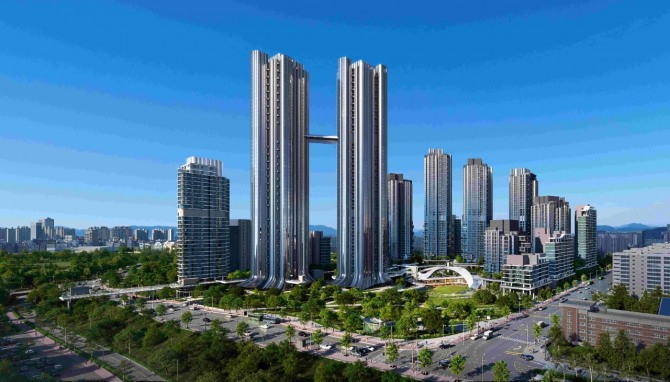
- Mokdong Complex 10 Reconstruction Win and 12.7 Trillion Won Cumulative Orders: Hyundai E&C secured the construction rights for the Mokdong Complex 10 reconstruction project in Seoul, bringing its cumulative orders for the year to 12.7 trillion won. Together with Samsung C&T, the company continues to dominate core urban renewal projects in Seoul.

목동10단지 재건축 조감도 및 관련 뉴스 이미지 - Expanding Energy Infrastructure Cooperation with Australia's AusNet and CIP: Hyundai E&C has expanded power infrastructure cooperation with Australian energy network company AusNet and signed a memorandum of understanding with global energy investment firm Copenhagen Infrastructure Partners (CIP).
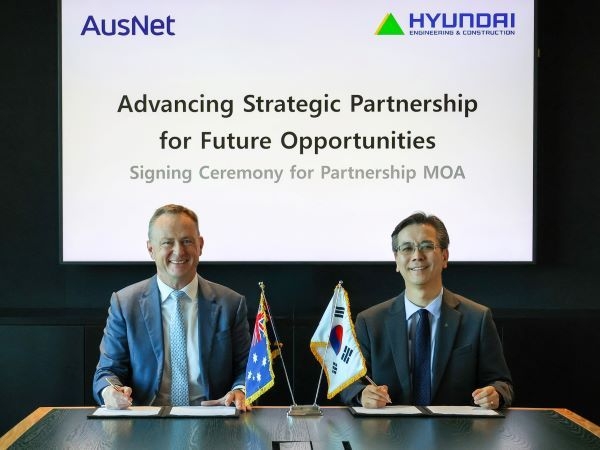
현대건설의 호주 오스넷 및 CIP 협력 관련 뉴스 이미지 - Q3 Operating Profit Projected to Surge 103%: According to a Hana Securities report, despite slowing overseas plant revenue, profitability in the architecture and housing sector has improved due to the completion of housing sites with high cost ratios, leading to expectations of a 103% increase in third-quarter operating profit.
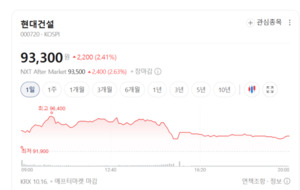
현대건설 3분기 실적 전망 관련 뉴스 이미지 - Financial Soundness and PF Risks: No specific risk signals regarding the resolution of contingent PF liabilities or unsold properties for Hyundai E&C have been identified within the past 24 hours. However, as reported last July, prolonged PF guarantees could trigger credit rating downgrades (2-3 notches) and require continuous monitoring. (Reference: July 14, 2026 report)
보증 리스크 및 협력사 관련 이슈
- Subcontracting and Partner Issues: No news reports regarding delayed subcontracting payments or new disputes over construction cost increases for Hyundai E&C have been identified within the last 24 hours. There appear to be no additional issues following the Shaheen project construction cost settlement friction in March. (Reference: March 9, 2026 report)
- Overseas Grid and Renewable Energy Opportunities: Cooperation with Australia's AusNet and CIP signifies a partnership extending beyond mere construction into power infrastructure and renewable energy sectors. This can serve as a new revenue portfolio opportunity to offset the sluggishness in traditional plant businesses.
- Partner Management in the Urban Renewal Duopoly: As the duopoly structure where Hyundai E&C and Samsung C&T dominate Seoul's core maintenance projects solidifies, subcontracting volumes and partner management burdens at these sites may increase. Implementation status following the fair trade agreement (May 28, 2026) remains quiet.
시장 분석 및 실무 인사이트
- Order Competitiveness vs. Peers: Samsung C&T (Yeouido) and Hyundai E&C (Mokdong) have each secured construction rights worth around 2 trillion won, further cementing the "duopoly" in the urban renewal market. This implies reduced bidding opportunities for other mid-sized builders and strengthened market dominance for Hyundai E&C.
- Key Points for Practitioners:
- Portfolio Diversification: A "rotating growth" strategy is materializing, where housing makes up for sluggish plant business, which in turn expands opportunities into overseas energy infrastructure (Australia).
- Continued Profitability Improvement: The projected surge in third-quarter operating profit indicates that cost ratio management has entered the mainstream, leaving room for potential upward revisions to Q4 and next year's earnings guidance.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Explore related topics
Powered by
