
Cloud Platform Wars — 2026-10-04
AWS maintains its market lead with 28% cloud infrastructure share as of Q2 2026, but Google Cloud's aggressive pricing and superior AI infrastructure continue to reshape competitive dynamics. The latest data reveals stark pricing disparities across container serverless and analytics workloads, with GCP and Azure undercutting AWS by 30-40% in key categories.
Cloud Platform Wars — 2026-10-04
Key Highlights
Market Leadership Remains Concentrated in AWS
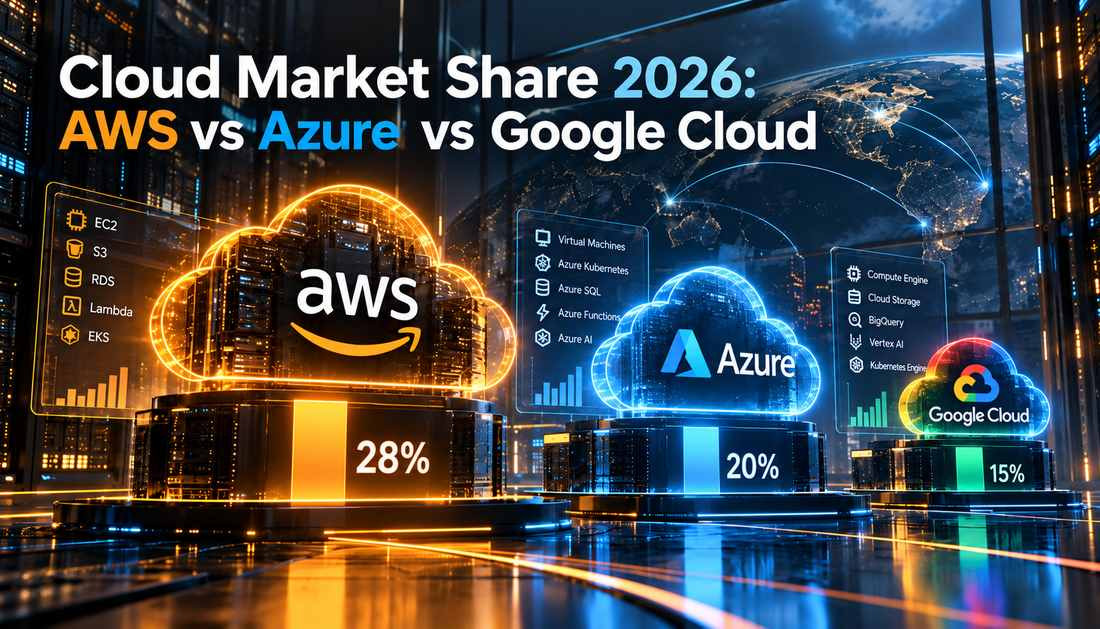
AWS holds 28% of the global cloud infrastructure market based on Synergy's Q2 2026 data, followed by Microsoft Azure at 20% and Google Cloud at 15%, with the overall market reaching $143.4 billion for the quarter.
Kubernetes Costs Reveal Structural Price Differences
For managed Kubernetes deployments, AWS EKS charges $0.10 per hour ($73/month) for control planes, while GCP's standard GKE matches that rate but offers an Autopilot mode with per-pod pricing for simplified cost management. Azure AKS provides a free control plane tier. Production-scale clusters cost $2,100–$3,000 monthly on GCP, $2,200–$3,200 on Azure, and $2,500–$3,500 on AWS.
Container Serverless: GCP and Azure Undercut AWS by ~40%
Google Cloud Run and Azure Container Apps are approximately 40% cheaper than AWS Fargate on per-vCPU-hour pricing, though traditional function-based serverless (Lambda/Functions/Cloud Functions) pricing remains nearly identical across all three platforms.
Analytics Query Pricing Converges
BigQuery (GCP), Athena (AWS), and Synapse Serverless (Azure) are identically priced at $5/TB scanned for analytics workloads, though GCP retains structural advantages in large-scale data processing due to architectural efficiencies.

Analysis
The October 2026 market data reinforces a bifurcated competitive landscape: AWS commands volume and enterprise relationships, but GCP has weaponized pricing asymmetry in container and serverless segments. The 40% cost gap on Fargate versus Cloud Run represents the single largest structural advantage any hyperscaler has built in the past 18 months. For organizations with containerized workloads—the fastest-growing segment in 2026—this difference compounds into seven-figure annual savings decisions.
Equally significant: regional pricing variance is now a material factor. Asia-Pacific and South America regions carry 10–30% premiums over US pricing, fragmenting pricing strategy for global workloads.
The convergence of analytics pricing at $5/TB suggests commoditization in query-based workloads, shifting competitive advantage from unit economics to feature velocity and integration breadth—territories where AWS and Azure's broader service catalogs remain dominant.
What to Watch
- Q3 2026 earnings calls (late October/early November): Watch for Azure and GCP growth rates; any deceleration in GCP's year-over-year gains would signal pricing aggression is reaching saturation
- Multi-cloud networking adoption: AWS–Google Cloud's joint multicloud collaboration (currently in preview) could reshape lock-in dynamics if broadly adopted
- AI infrastructure constraint: All three platforms report compute scarcity; watch for pricing normalization once capacity equilibrium returns
Note on data freshness: This analysis reflects pricing, market share, and cost benchmarks current as of May–September 2026. Regional pricing, commitment discounts, and service-specific rates vary; verify current quotes with each provider before architectural decisions.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
