
Europe Markets Weekly — 2026-09-28
European equities look to build on last week's relief rally as falling oil prices offered respite, but renewed Middle East tension kept investors wary. Monday trading was muted after President Trump rejected Iran's proposal, nudging crude back up and pressuring tech shares. Bond yields and the outlook for ECB rates remain the key swing factors into the new week.
Europe Markets Weekly — 2026-09-28
Market Snapshot
- STOXX 600: +0.2% on Monday; last week gained about 0.5%, snapping a three-week losing streak
- DAX: Finished last week at 25,408.64, up roughly 0.4% weekly after Friday's 0.56% gain; flat early Monday
- CAC 40: +0.3% early Monday
- FTSE 100: +0.3% early Monday
Key Drivers
- Oil relief meets elevated yields: Last week's first weekly gain in three weeks was driven mainly by oil prices retreating, though surging government bond yields capped the rally and left the move a "relief rally" rather than a return to risk-taking.
- Inflation pressure builds again: Euro-area inflation is set to hit a three-year high, keeping pressure on the ECB to lift interest rates further. Goldman Sachs Research expects a December hike and doubts rates stay below 3%, citing resilient growth and Iran-war-related inflation pressure.
- ECB Economic Bull matters: The ECB published Economic Bulletin Issue 6 this week, which adds context to the 10 September 25bp rate hike and the Middle East conflict's inflation impact.
- Euro softens: EUR/USD slipped to around 1.1380 early Monday, pressured by hawkish Fed signals and escalating Middle East tensions; the pair ended last week slightly higher near 1.1403 after Brent fell below $100/barrel on reported US–Iran talks.
Earnings & Corporate
No specific company earnings reports were published since 2026-09-26 in the research results, so no sector-level earnings stories are covered this week.
Geopolitics & Energy
- Trump rejects Iran proposal: Oil prices rebounded Monday after President Trump rejected Iran's offer regarding the Strait of Hormuz, reversing part of Friday's slide that had lifted equities. European bourses opened cautiously as a result, with tech stocks slipping.
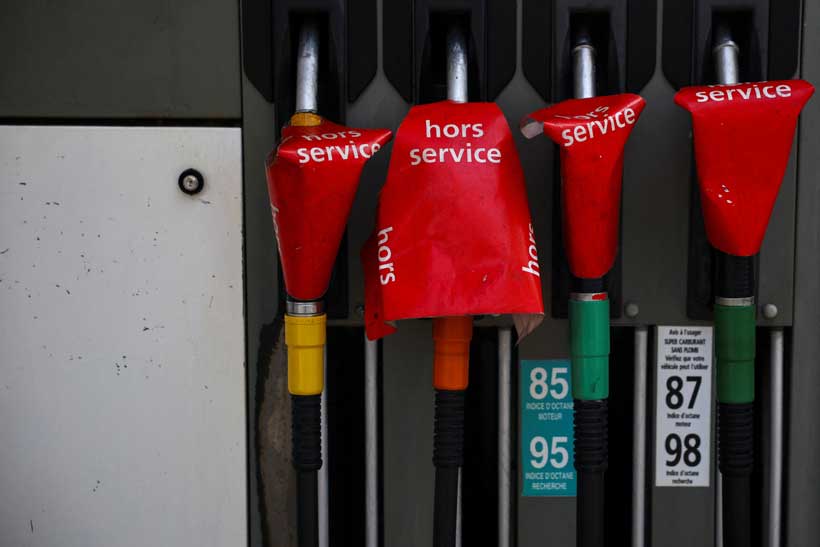
- Diesel is the new vulnerability: Analysis argues the 2026 energy shock runs through oil, diesel and shipping chokepoints rather than gas — a different dynamic from 2022's gas crisis. Separately, European officials flagged risks from a threatened U.S. diesel export cutoff given Europe's reliance on American fuel.
- LNG sanctions risk: U.S. sanctions against Russia could risk further declines in LNG supplies to Europe, with the U.S. law allowing tariffs of up to 100% on countries still buying Russian energy.
What to Watch Next Week
- Middle East / Strait of Hormuz developments after Trump's rejection of Iran's offer, and their effect on crude
- Bond yield trends — elevated yields are still the main counterweight to any equity relief
- Inflation prints due in the week ahead, with euro-area inflation heading toward a three-year high and ECB rate expectations in focus
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
