
글로벌 모닝 브리핑: 미 증시와 세계 뉴스
Wall Street slipped as rising oil prices and strong business activity fueled inflation fears, with the 10-year Treasury yield holding near 5% and the upcoming Trump-Xi summit drawing intense focus. Asian and Korean markets need to keep a close eye on oil, yields, and semiconductor AI momentum today.
Global Morning Briefing — September 23, 2026
Market Snapshot at a Glance
| Indicator | Close / Current | Change |
|---|---|---|
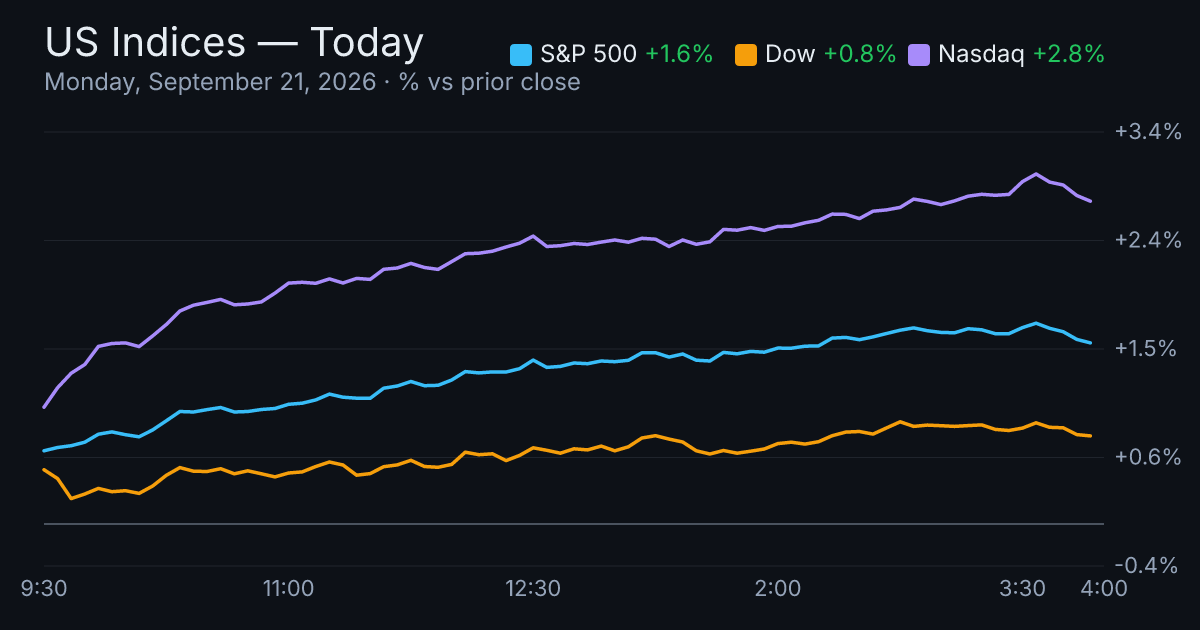
| S&P 500 | 7,764.7 (as of 9/21) | +1.49% |
| Nasdaq Composite | 27,122.09 (as of 9/21) | +2.26% |
| Dow Jones | Around 52,000 (as of 9/21) | +0.71% |
| 10-Year US Treasury Yield | 5.01% (highest since 2007) | — |
| WTI Crude Oil | Hovering above $100.30 | High due to Strait of Hormuz crisis |
| Bitcoin | Reached highest level since January | Up |
The Dollar Index (DXY), gold, and Russell 2000 are omitted as reliable figures within the last 24 hours were unavailable.
US Market Closing Review
Last Monday (September 21), US stocks rallied strongly on easing geopolitical tensions and falling Treasury yields. The Nasdaq surged 2.26% to 27,122.09, the S&P 500 gained 1.49% to 7,764.7, and the Dow rose 0.71%, closing near record highs. This rally was fueled by a recovery in risk appetite as some of the previous week's spike in oil prices and bond yields unwound.

However, the mood completely reversed on Tuesday (September 22). A rebound in oil prices reignited inflation concerns, and US business activity growing at its fastest pace since 2021 sparked interpretations that the need for rate cuts is diminishing, dragging both stocks and bond prices lower. According to Reuters, while tech stocks generally declined, gains in Meta Platforms helped limit the downside for the S&P 500 and Nasdaq. Sector rotation between energy beneficiaries and tech adjustments was visible, alongside a cautious wait-and-see attitude ahead of the upcoming Trump-Xi summit amid wild volatility compared to the previous day.
Key Movers Today (Pre-market as of Sept 23, Confirmed Only)
Top Gainers
- IONQ (IonQ) — Up: Surged in pre-market trading ahead of quantum computing catalysts. Exact percentage figures were not available in the report.
- SIX (Six Flags) — Up: Stock price increase confirmed in pre-market trading.
- META (Meta Platforms) — Up: Rose against the broader tech weakness, helping cushion the index's decline.
Top Losers
- GIS (General Mills) — Down: Fell despite beating Q1 2026 earnings expectations, likely reflecting guidance and cost-related concerns.
Exact percentage changes for individual stocks are omitted as they were not provided in the source.
Macro & Economic Indicators
- US Business Activity Index: Grew at the fastest pace since 2021. Economic resilience stoked inflation worries, pushing expected rate cut timelines further back and causing stocks and bonds to fall together.
- 10-Year US Treasury Yield: Hit 5.01%, the highest level since 2007, with volatility continuing. Higher borrowing costs weigh heavily on growth stock multiples.
- Oil Prices: WTI remained high above $100 per barrel due to the Strait of Hormuz crisis. Supply risks persist as Saudi Arabia reportedly cut supplies to European refiners for October, and French President Emmanuel Macron urged G7 strategic petroleum reserve releases.
Global Top News (Ranked by Market Impact)
Trump-Xi Summit Imminent: The Ultimate Market Focus
- What Happened: Ahead of this week's summit between President Trump and President Xi Jinping, hopes for improving US-China relations lifted risk sentiment, previously driving oil prices down and stock futures up (+0.7% for S&P 500 futures, +1.1% for Nasdaq 100 futures).
- Market Implications: The outcome directly impacts demand for South Korean export sectors (semiconductors, autos, secondary batteries). A trade thaw could act as a KOSPI breakout trigger, while a breakdown risks a sharp reversal in risk appetite.
Crude Oil Holds Above $100 Amid Hormuz Crisis
- What Happened: Following WTI's close at $100.30 (September 18) due to Strait of Hormuz tensions, prices remained elevated as Saudi Arabia's supply cuts to Europe and discussions of a G7 SPR release added to supply uncertainty.
- Market Implications: Higher oil feeds inflation expectations and rising yields, burdening growth stocks. In South Korea, it raises cost pressures for refiners and airlines, and pricing pressures for petrochemicals.
10-Year Yield Hits 5.01%: Highest Since 2007
- What Happened: The US 10-year yield touched 5.01%, marking its highest level since 2007. Expectations for Fed rate cuts following the September 11 CPC have already priced in a July easing cycle and two cuts next year.
- Market Implications: A 5% yield environment pressures global growth stocks and accelerates capital outflows from emerging markets. For the South Korean market, it serves as a key variable for foreign investor flows.
Bitcoin Touches Highest Level Since January
- What Happened: Bitcoin climbed to its highest level since January, showing signs of reversing the downward trend that persisted throughout 2026.
- Market Implications: This can be interpreted as a sign of returning risk-on sentiment, though investors must watch whether momentum can sustain itself in a 5% yield environment.
South Korea Market Checkpoints
The combination of a 5.01% US 10-year yield and $100 oil creates a dual burden for the KOSPI. However, with the Nasdaq recently hitting all-time highs (September 18), AI trading regaining traction, and chip stocks showing strength, heavyweight semiconductor names like Samsung Electronics and SK Hynix enjoy relative defensive support. The outcome of the Trump-Xi summit will likely dictate the valuation direction for export stocks and the broader KOSPI. The USD/KRW exchange rate faces upward pressure amid a strong dollar and 5% US yields, and secondary battery and supply-chain export stocks are expected to see heightened volatility tied to oil and tariff issues.
Watch List for Today
- Events: Trump-Xi Jinping summit (scheduled for this week) — the biggest market variable.
- Earnings: The Q1/Q2 2026 earnings season is drawing to a close, with sector volatility driven by individual corporate reports starting tomorrow.
- Fed & Policy Events: Debates over Federal Reserve rate cut expectations and potential additional easing — with risks of expanding inflation concerns.
- Risk Factors: Potential oil price spikes linked to the Strait of Hormuz and whether the 10-year yield sustains above 5%.
Investor Action Items
- Morning Session Response: Real-time monitoring of headlines surrounding the Trump-Xi summit, checking whether Nasdaq overnight futures and yield spread pressures are easing before taking action.
- Sectors to Watch: Dual monitoring of semiconductors (supported by ongoing AI demand momentum and Nasdaq strength) versus refiners and airlines (facing risks from sustained $100+ oil).
- Risk Management: In a high-yield environment with the 10-year at 5.01%, valuation compression pressures on growth stocks are likely to persist, so maintaining a stance of reducing exposure to valuation-heavy sectors and increasing cash holdings is recommended.
This briefing was prepared based on publicly available sources from the past 24–48 hours. Certain indicators (such as the Dollar Index, gold, Russell 2000, and individual stock performance percentages) have been omitted due to a lack of verifiable latest figures.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
