
오늘의 증시 핵심 브리핑 — 2026-09-29
Following the Chuseok holiday, South Korean stock markets opened lower for both KOSPI and KOSDAQ, while rising U.S. Treasury yields emerge as a global risk factor. U.S. equities initially dipped due to soaring U.S. Treasury yields but rebounded on Friday driven by AI-related stocks. Today's key themes are set by U.S. inflation data (PCE) and Micron's earnings in this semiconductor-focused week.
오늘의 증시 핵심 브리핑 — 2026-09-29
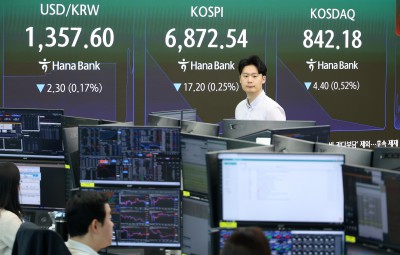
Key Market Issues Today
- Domestic Market Opens Lower: On the morning of the 29th, both the KOSPI and KOSDAQ opened with synchronized declines. Foreign exchange dealing related to the USD/KRW exchange rate took place at the Hana Bank dealing room in Jung-gu, Seoul.
- U.S. Treasury Yields Spike Over the Weekend: On Monday (28th), the U.S. stock market closed lower, weighed down by a sharp surge in Treasury yields early in the week. However, it managed to finish Friday higher, wrapping up a volatile week.
- Directional Test Right After Chuseok: The Herald Economy reported that whether the KOSPI rebounds after reopening following the Chuseok holiday depends heavily on September 30th. Although U.S. Treasury yields topped 5% this week, Wall Street closed higher on the final trading day as AI-related stocks showed strength.
- Focus on U.S. Inflation and Semiconductor Earnings: According to the Financial News weekly stock market outlook, the domestic market is expected to seek direction after checking U.S. inflation indicators (PCE) and semiconductor earnings. Daishin Securities researcher Lee Kyung-min noted that "PCE inflation and..." suggest investors can focus on sectors undervalued relative to their earnings.

Surging Themes and Notable Stocks Analysis
- Inflow into Biotech and Secondary Batteries: On the 28th, the KOSDAQ experienced high volatility, surging up to the 861 level during intraday trading before pulling back to close 0.25% higher at the 841 level. HLB hit the daily upper limit, while EcoProBM soared 6%, with buying in biotech and secondary batteries supporting the index.
- Weakness in Semiconductors and Equipment Stocks: On the same day, semiconductor and equipment stocks showed weakness. Reports also indicated that chipmakers in the U.S. market took a hit due to the OpenAI pause issue.
- Beneficiary of U.S. Fuel Economy Regulation Relaxation — GM: GM is seen as the primary beneficiary of eased U.S. fuel economy regulations, with projected technology cost savings of $20.4 billion.
- Expectations for Eased AI Chip Exports: The Information reported that China may allow Alibaba and ByteDance to purchase new NVIDIA chips. Additionally, reports surfaced that the U.S. and China agreed on $30 billion in tariff reductions and initiated an AI dialogue.
- Oil Price Trends: President Trump reportedly stated that if the war ends "soon," oil prices will plummet. Amid rising oil prices and climbing interest rates, Asian stock markets showed a cautious stance.

Macro Context
- U.S. Interest Rate Upward Pressure: Rising U.S. Treasury yields were the main driver behind the stock market decline on the final trading session before the weekend, with reports showing U.S. Treasury yields broke past 5% this week.
- Gold and Oil Pressures: Gold prices reportedly dropped below $4,300, pressured by Federal Reserve rate hike bets and rising oil prices.
- Cautious Tone in Asian Markets: Asian stock markets remained cautious amid rising oil prices and interest rates. Meanwhile, Taiwan stated that U.S. military support aligns with American interests following the Trump-Xi summit. Iran is advocating for diplomacy after Trump rejected the Hormuz peace plan.
This report is prepared solely based on researched data, and all investment responsibilities lie with the individual.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
