
Forex & Currency Watch — 2026-09-30
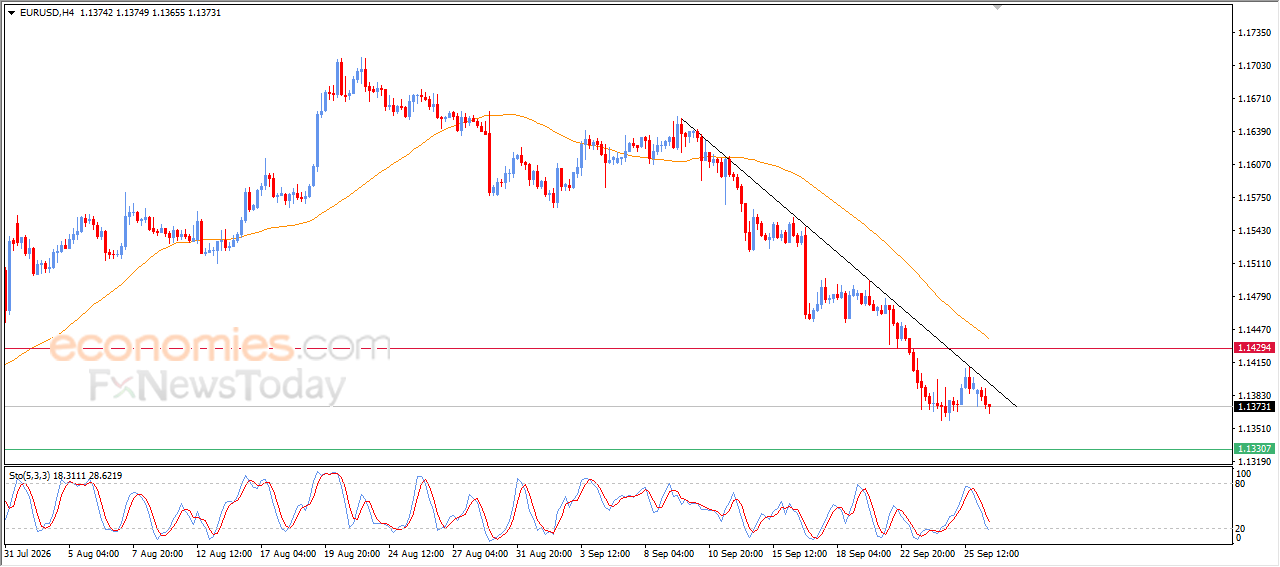
The US Dollar Index surges toward its yearly peak on hawkish Federal Reserve expectations, with EUR/USD sliding to a three-month low near 1.1331 as broad-based greenback strength dominates. Rising Treasury yields and crude oil strength are the primary macro catalysts reshaping FX positioning, while Japanese yen intervention risks loom near the 160 handle.
Forex & Currency Watch — 2026-09-30
Market Snapshot
| Pair | Last | Daily % Change | Weekly % Change |
|---|---|---|---|
| DXY (US Dollar Index) | ~106.50* | +0.35% | +1.20% |
| EUR/USD | 1.1331 | -0.35% | -0.76% |
| USD/JPY | 157.46 | +0.04% | +0.04% |
| GBP/USD | 1.3239 | -0.14% | -0.78% |
| USD/CHF | 0.8334 | +0.22% | +1.52% |
| AUD/USD | 0.6994 | -0.34% | -1.70% |
| USD/CAD | 1.4186 | +0.09% | +0.85% |
*Indicative level; exact data from TradingEconomics/Investing.com as of latest quote timestamp (02:55 GMT, 2026-09-29)
Top Movers

EUR/USD (loser): Down 0.35% to 1.1331, lowest level since late June. Hawkish Fed signals and broader dollar strength are driving the Euro into pressure, as expectations for further US rate hikes lift the Greenback across the board.
USD/CHF (winner): Up 0.22% to 0.8334. The Swiss Franc weakened despite traditional safe-haven flows, as higher US yields attracted capital to dollar assets and outweighed flight-to-safety demand.
GBP/USD (loser): Down 0.14% to 1.3239. Sterling gave ground despite UK inflation data, as the dollar's broad-based rally overwhelmed regional moves; positioning data showed increasing GBP shorts on futures markets.
What Moved the Tape
-
Hawkish Fed Outlook Propels Dollar: The US Dollar Index approaches its year-to-date high as expectations for further Federal Reserve interest-rate hikes drive strong demand for the Greenback. Traders are repricing terminal rate expectations upward, widening yield differentials in favor of dollar assets and pushing EUR/USD through the 1.1350 barrier.
-
Rising Treasury Yields Fuel Yield-Carry Unwind: The 10-year Treasury yield hit its highest level in nearly two decades, lifting real rates and making dollar-denominated fixed income more attractive. This repricing accelerated outflows from lower-yielding EM and G-10 currencies, particularly the Euro and commodity-linked pairs such as AUD/USD (down 0.34%).
-
Crude Oil Strength and Geopolitical Risk Premium: Trump's rejection of Iran's Hormuz proposal lifted WTI crude toward $106, buoying energy-linked currencies (USD, CAD strength) and heightening risk-off sentiment. Elevated oil prices feed into inflation expectations and justify higher Fed terminal rates, reinforcing the dollar narrative.
Central Bank Watch
-
Federal Reserve (US): Markets are now pricing in a higher probability of additional Fed tightening or extended hold at elevated rates, reversing earlier 2026 expectations for multiple cuts. The hawkish repricing has lifted USD across all major pairs and is expected to persist pending October CPI and employment data.
-
Bank of Japan (Japan): Traders are monitoring yen intervention risk near the 160 USD/JPY level. Citi strategists flagged the likelihood of Ministry of Finance intervention if dollar strength accelerates further, creating a two-way risk for USD/JPY positioning and keeping volatility elevated.
-
European Central Bank (ECB): The ECB remains on the sidelines as rate-cut expectations strengthen for the eurozone amid slowing growth. The interest-rate differential between the US (higher for longer) and eurozone (easing bias) is a primary driver of EUR/USD weakness and the Euro's three-month low.
Emerging Markets & Asia FX
-
Chinese Yuan (USD/CNY): Stabilizing after recent softness, but medium-term strength forecasts remain muted as US rate expectations shift hawkish. Widening yield spreads favor dollar strength, pressuring CNY despite underlying structural appreciation cases in ING's 2026 Asia FX outlook.
-
Indian Rupee & South Asian EM: Broader dollar strength and rising US yields are weighing on EM currencies across Asia. The ING research team flagged the Indian rupee as having "room to appreciate" in 2026, but current hawkish Fed repricing may delay that move as capital flows reverse into US fixed income.
-
Japanese Yen Intervention Zone: USD/JPY remains in focus near 157–160. Ministry of Finance intervention threats are capping upside, but the carry-trade unwind risk and higher US yields continue to support dollar bulls. Any break above 160 is expected to trigger official action.
Strategist Takes
David Scutt (Forex.com): "Crude oil is setting the tone across rates and FX, leaving EUR/USD vulnerable and USD/JPY caught between higher Treasury yields and the growing threat of intervention. The identity crisis in FX is clear—carry-trade logic clashes with intervention risk."
StoneX FX Desk (COT Report): US dollar net-longs surged as EUR/USD and GBP/USD futures positioning turned increasingly bearish. This positioning shift reflects the market's repricing of Fed terminal rates and validates the technical breakdown in EUR/USD to three-month lows.
What to Watch Next
-
US CPI (Consumer Price Index) — Mid-Week (October 2026): The next inflation print is critical for Fed rate-hold/hike expectations. Hot CPI could accelerate dollar strength further; tame readings might allow a brief relief bounce in EUR/USD and GBP/USD. Sensitivity highest for EUR/USD and USD/JPY.
-
US Initial Jobless Claims & Nonfarm Payrolls — Weekly/Early October: Labor data will frame Fed patience. A strong jobs report could lock in higher terminal rate expectations; weak data might ease some hawkish repricing. Monitor USD/CAD and AUD/USD for commodity-currency spillovers.
-
ECB Speakers & Eurozone Manufacturing PMI (Sept 30): Any dovish ECB messaging or disappointing manufacturing data could accelerate EUR/USD weakness. Watch for guidance on Q4 rate cuts, which could widen the Fed/ECB differential further.
-
Bank of Japan Verbal Intervention / MOF Statement — Ongoing: BoJ and Ministry of Finance commentary on yen weakness is a live risk. A formal statement tightening intervention thresholds or confirming action near 160 would trigger sharp USD/JPY reversals. This is a daily event risk through October.
Reader Action Items
-
EUR/USD Breakout Trade: The pair has broken a three-month low at 1.1331. Watch for support near 1.1300; a close below that level would target 1.1200 as the next technical stop. The trend is clearly dollar-favorable on higher US yields and hawkish Fed expectations.
-
USD/JPY Intervention Zone: Do not chase above 160 without a full MOF/BoJ statement confirming passivity. The risk/reward is skewed downward for longs above 160 given intervention precedent. Wait for a dip toward 156–157 before re-initiating long positions.
-
Carry Trade Unwind Risk: If US rates stabilize higher and yen intervention fears ease, expect continued USD/JPY upside but watch for violent reversals on any BoJ/MOF jawbone. Hedge USD/JPY exposure with stops above 160.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
