
Gig & Freelance Economy — 2026-10-01
India's gig economy continues rapid expansion with emerging digital freelancing roles, while global platforms face ongoing worker classification debates. Recent data shows 72.9M US independent workers and a $1.5T skilled-freelancer earnings market, though regulatory pressure persists around employment status.
Gig & Freelance Economy — 2026-10-01
Key Highlights
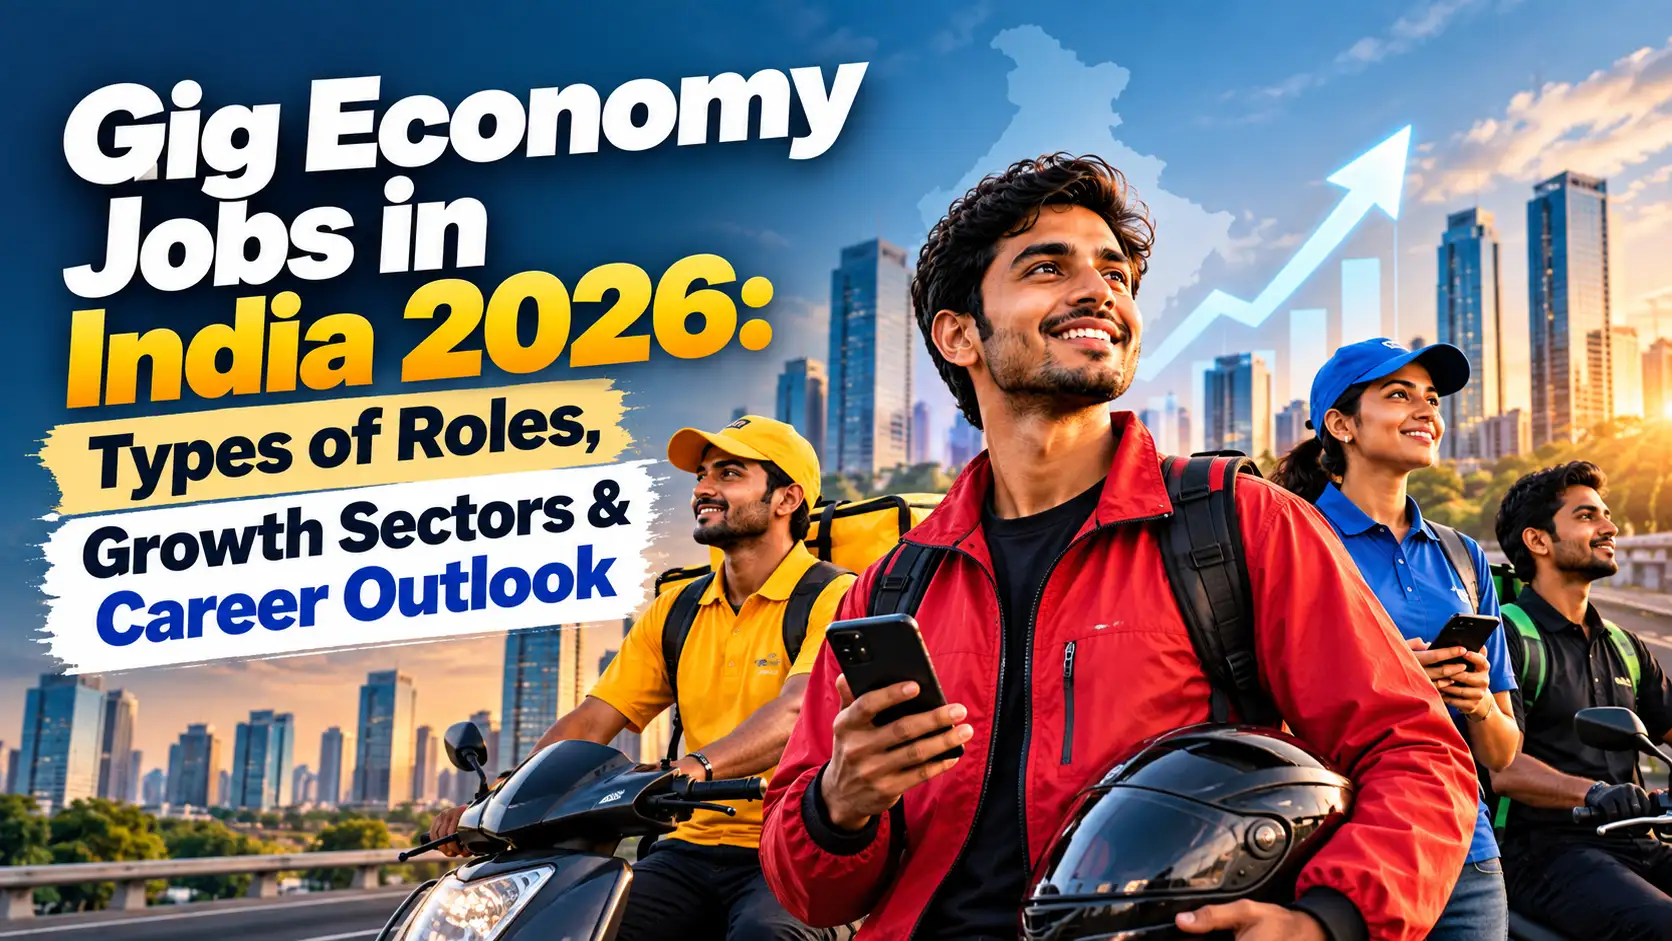
India's Emerging Gig Roles India's gig economy is expanding beyond traditional delivery and ride-sharing into specialized segments. New role classifications include hyper-local logistics coordinators, digital content creators, and platform-specific service providers. The market is witnessing structural shifts as workers transition from single-platform dependency to multi-platform engagement strategies.
Global Workforce Scale The US independent worker population stands at approximately 72.9M workers, representing a significant portion of the labor market. Skilled freelancer earnings in the US reached $1.5T, with online gig demand growth of 41% year-over-year. AI-skill demand among gig workers has surged 109%, indicating rapid reskilling pressures across the sector.
Tax Compliance Pressures Gig workers continue to face self-employment tax obligations (15.3% federal rate) plus income tax requirements. The 2026 regulatory environment introduced updated 1099-NEC thresholds and the Overhaul of Business-to-Business Activity (OBBBA) framework, creating new compliance demands for both workers and platforms.
Analysis
The most significant development in independent work this week centers on India's structural transformation of its gig economy. Rather than remaining concentrated in delivery and transportation, India's sector is fragmenting into specialized digital roles—from content creation to logistics coordination. This mirrors a broader global pattern where gig platforms are moving away from one-size-fits-all models toward role-specific ecosystems.
Simultaneously, US data reveals the gig sector's massive scale (72.9M workers) is driving urgent reskilling demand, with AI competencies becoming non-optional for competitive freelancers. The 109% surge in AI-skill demand suggests platforms and workers are racing to integrate generative AI tools into service delivery—a potential competitive advantage for early adopters but a barrier for workers unable to reskill quickly.
What to Watch
Regulatory Developments: EU platform work directive transposition deadlines approaching late 2026 will likely create cascading changes in how US and other jurisdictions classify gig workers. The DOL's proposed classification rules remain in flux, with employer-favorable standards potentially widening the gap between employee and contractor designations.
Platform Strategy Shifts: Fiverr's gig-packaged service model (no bidding required) and Upwork's emphasis on long-term contracts continue diverging. Toptal's selective 3% acceptance strategy targets premium market positioning, while mass-market platforms consolidate volume.
Tax Policy: The OBBBA framework and updated 1099 thresholds will require platform compliance updates by year-end 2026, likely triggering changes in worker payment processing and reporting.
No sufficient fresh data available for worker earnings trends, strike activity, or platform-specific policy changes in the past 24 hours.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
