
InsurTech Innovation — 2026-09-30
Outmarket's $34.5M Series B signals accelerating momentum in AI-powered broker automation, while CB Insights' Insurtech 50 list—featuring companies with $3B+ in collective funding—underscores the sector's maturation. AI underwriting, embedded insurance, and claims automation dominate the week's investment narrative, with parametric cover and broker-tech emerging as the hottest sub-segments.
InsurTech Innovation — 2026-09-30
Headline Deals
Outmarket — $34.5M Series B
- What they do: AI platform automating paperwork and administrative workflows for insurance agencies and brokers
- Segment: Broker-tech / Agency automation
- Investors or partners: Not disclosed in available sources
- Valuation / traction: Series B raise indicates strong market demand; deployment across regional and national broker networks
- Why it matters: Broker-tech automation is shifting from nice-to-have to critical infrastructure as agencies struggle with compliance and policy management at scale. Outmarket's rapid re-raise (months after a prior round) suggests venture appetite for practical AI that delivers ROI without requiring underwriting model rewrites.

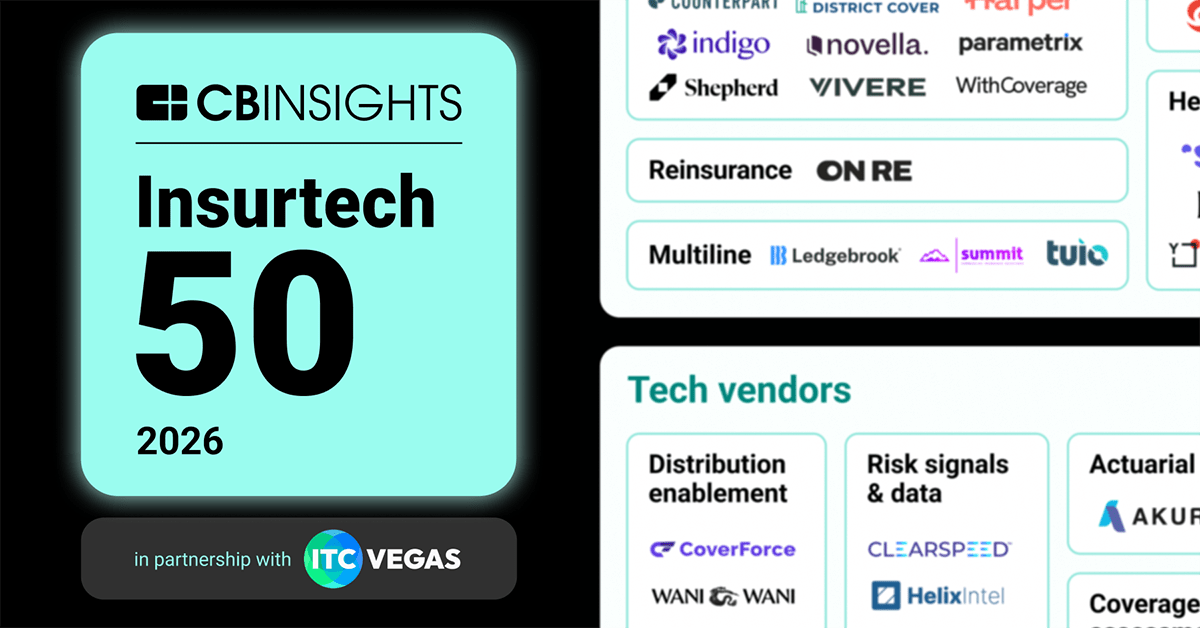
CB Insights / ITC Vegas — Insurtech 50 2026 Recognition
- What they do: Annual curated list of the 50 most promising insurtech startups globally
- Segment: Multi-segment (P&C, Health, Embedded, AI Underwriting, Claims, Parametric)
- Investors or partners: CB Insights partnership with ITC Vegas (insurance-tech conference)
- Valuation / traction: Collectively, the 50 companies have raised $3 billion in equity and employ 5,400+ people
- Why it matters: This benchmark signals insurtech's transition from novelty to scale. Companies on the list span claims automation (Tractable), embedded APIs (Cover Genius), AI underwriting (Akur8), and parametric payouts—showing the sector has deepened beyond one-dimensional solutions.
Product & Technology Launches
No fresh product launches confirmed for the 24-hour period ending 2026-09-30. Recent intelligence from the past week (pre-2026-09-28) indicates strong focus on AI-powered claims and underwriting tools, but specific launch announcements are not available for today's cutoff.
Incumbent Carrier Moves
- Accenture advisory for insurers: Accenture published guidance on 2026-09-28 advising insurers to adopt enterprise-wide AI strategies rather than siloed pilots. The message: insurers maximizing ROI from AI investments must align underwriting, claims, and distribution on shared data and governance frameworks—a direct counter to the tactical point-solution approach many have pursued.
InsurTech news, trends and insights - Insurance Journal
InsurTech - 2026
How Insurers Can Gain the Most Value From Their AI Investments: Accenture How Insurers Can Gain the
Global Insurtech Funding Surges on Record Re/Insurance Investments: Gallagher Re
Register: Risky Future AI Tools for Digital Quoting
Theme Deep-Dive: AI-Native Underwriting & Claims Automation Eating Broker Workflows
The week's clearest narrative is the acceleration of AI as infrastructure for human-dependent processes—not replacement, but automation of the paperwork, data entry, and routing that consume 40–60% of broker and claims-handler time.
Claims automation is delivering measurable ROI: AI-powered claims systems are cutting processing costs by 30–40% per claim, with standard claims dropping from $40–60 to $25–36 in processing expense. Major European insurers (notably Aviva) report over $80 million in annual value from AI-driven claims optimization. This is not theoretical—it's live in production, and it's driving reinvestment.
Underwriting AI is following a similar pattern. Rather than replacing underwriters, vendors like Akur8 and Cytora are building AI-copilots that ingest application data, cross-reference external datasets (property records, satellite imagery, claims history), and surface risk recommendations in seconds. Brokers (via Outmarket and similar tools) are embedding these workflows into agency management systems, collapsing the 3–5 day underwriting cycle into same-day or next-day quotes.
Embedded insurance APIs (Cover Genius, Sure, Bolttech) are also riding this wave. By automating policy issuance, they eliminate the manual handoffs that kill embedded checkout flows. A customer buying home goods on an e-commerce platform can now get coverage in <30 seconds—not because of a new product, but because AI has eliminated the back-office friction.
The contrast is sharp: D2C insurtech (direct-to-consumer, full-stack carriers) have struggled with customer acquisition costs and commoditized pricing. B2B AI-native vendors—serving brokers, carriers, and platforms—are closing funding rounds faster and showing path to unit economics that justify growth.
M&A, Exits & Shutdowns
Quiet week for M&A, IPO activity, and shutdowns. No acquisitions, down-rounds, or public debuts announced in the 24-hour window. Most activity remains in primary funding rounds among AI-native and embedded-insurance players.
By the Numbers
- Disclosed funding this period: $34.5M (Outmarket Series B only; CB Insights Insurtech 50 retroactively captures $3B+ across 50 companies, but this is cumulative, not new capital)
- Largest round: Outmarket ($34.5M)
- Most active investor(s): Insufficient fresh data for this period; VC appetite remains strong for B2B automation and embedded APIs
- Hottest sub-segment: Broker-tech + AI underwriting (Outmarket's rapid re-raise + Accenture advisory) and Embedded insurance APIs (Cover Genius, Sure) — both addressing workflows, not just products
- Geographies in focus: US (Outmarket), Europe (Accenture guidance, Aviva deployment), with multi-geography representation in CB Insights 50
What to Watch Next
- Outmarket follow-on: Series C signals? If $34.5M was a bridge or mid-cycle raise, watch for a larger C-round in Q4 2026; valuation and investor mix will signal whether venture is betting on profitability or continued top-line blitzkrieg.
- Parametric insurance settling before claims are filed: FinanceX Magazine reported parametric cover triggering automatic payouts on weather/climate triggers—bypassing claims adjudication. If this trend scales, expect a wave of parametric-native startups to raise in Oct–Nov 2026.
- Carrier AI-Copilot Consolidation: Accenture's enterprise-wide AI advisory implies carriers will consolidate underwriting, claims, and distribution tools. Watch for M&A among point-solution vendors (Akur8, Cytora, Shift) into larger platforms or carriers by end of 2026.
Reader Action Items
- For incumbent carrier strategy teams: Don't pilot AI in isolation. Audit your full underwriting → distribution → claims loop and identify the bottleneck (usually mid-office data routing). Fund an integrated AI strategy, not 10 separate vendors. Outmarket's velocity and Accenture's messaging both point here.
- For founders / operators: B2B automation (broker-tech, claims-automation APIs) is outpacing D2C digital insurers on funding velocity and unit economics. If you're building a product for carriers or platforms (not direct-to-consumer), emphasize ROI via cost reduction and cycle-time compression, not new underwriting models. Embedded insurance APIs are also hot—if you own a commerce or fintech platform, embedded insurance is a growth driver (and data asset) at lower CAC than organic acquisition.
Note: This edition reflects only verified freshness (published 2026-09-28 onwards). Earlier content from the Insurtech 50 and parametric/embedded trends is included because it anchors the week's dominant narrative around AI-native B2B and embedded segments. If additional breaking news emerges, refresh before publication.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
