
AI in Banking and Insurance Operations — 2026-09-20
The Conference of State Bank Supervisors (CSBS) released a new AI Supervisory Framework on September 16, providing state examiners with guidelines to assess AI risks in banks, including generative AI. Concurrently, RAND Corporation highlighted that insurers are becoming wary of underwriting corporate liability for AI-driven mishaps due to insufficient data on machine-made errors. In Asia, South Korean regulators and industry bodies are actively addressing the gap between AI adoption rates and internal control structures, with only 7.5% of insurers having established dedicated AI control bodies.
AI in Banking and Insurance Operations — 2026-09-20
Top developments
CSBS Releases New AI Supervisory Framework for State Examiners
On September 16, 2026, the Conference of State Bank Supervisors (CSBS) released an Artificial Intelligence Supervisory Framework designed to help state financial examiners identify and assess how regulated institutions use AI. This framework addresses the "federal gap" where existing model risk management guidance (SR 11-7) explicitly excludes generative and agentic AI, leaving these areas to broader risk management. The new guidance aims to standardize how examiners evaluate AI governance, particularly for fraud models and automated decision systems that fall outside traditional credit risk models.
Insurers Wary of Covering AI Liability Due to Data Gaps
A recent RAND Corporation report indicates that insurers are increasingly reluctant to write corporate liability policies covering AI-related losses because they lack sufficient data to price "machine-made mishaps." Unlike traditional risks, the frequency and severity of AI errors—such as hallucinations in advisory bots or biased underwriting decisions—remain poorly understood. This uncertainty is causing insurers to either exclude AI-specific claims or price premiums prohibitively, potentially stalling the deployment of autonomous AI agents in high-stakes banking operations.

South Korean Insurers Lag in AI Governance Structures
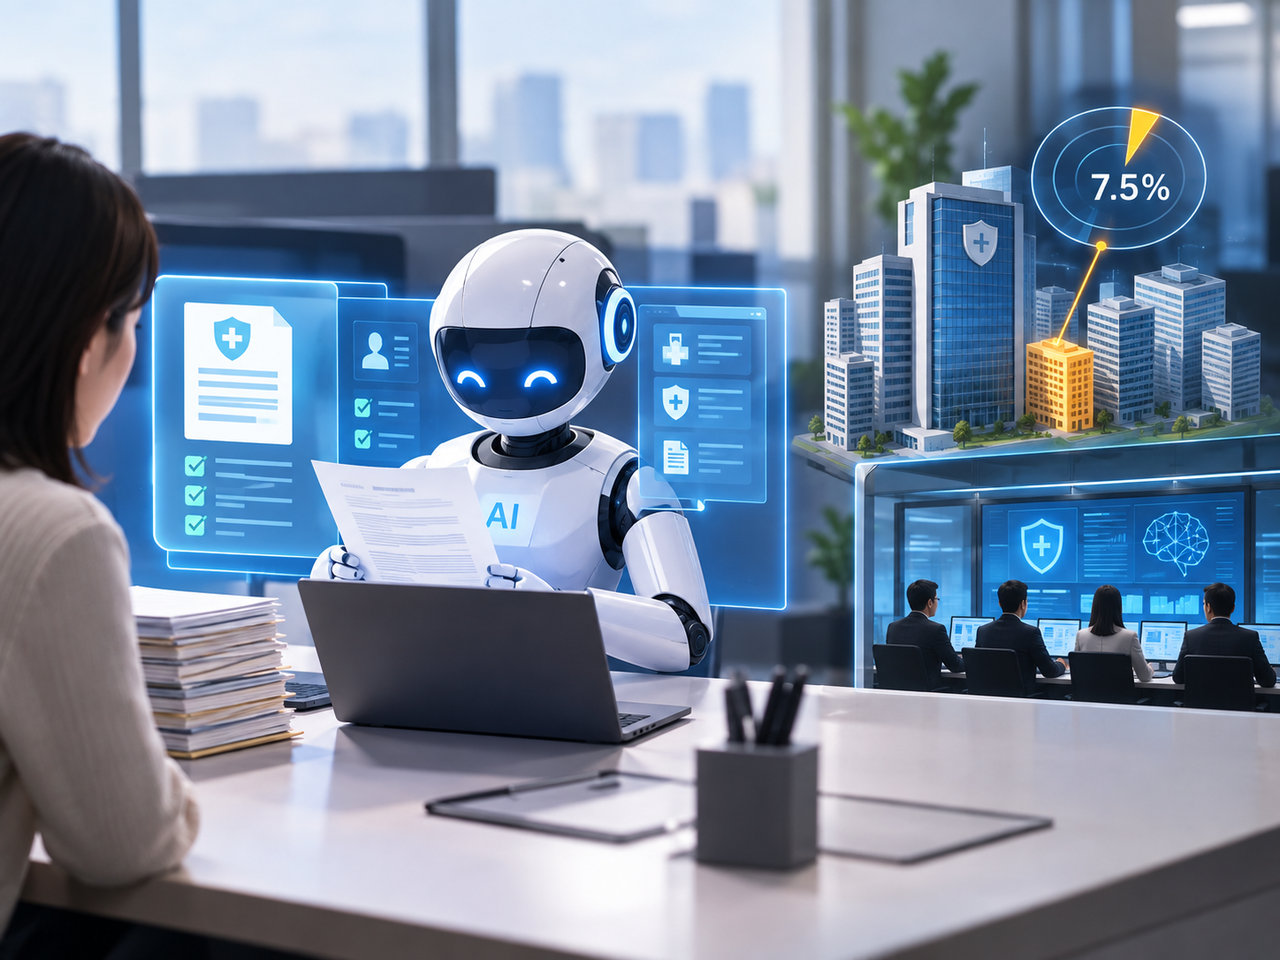
In South Korea, local media reports that only 7.5% of insurance companies have established dedicated "AI control bodies" despite the widespread use of AI in claims assessment and fraud detection. The Financial Supervisory Service (FSS) has strengthened its guidelines to require enterprise-wide risk management for AI, but implementation is uneven. Industry experts argue that without robust internal controls, the rapid adoption of generative AI in customer-facing roles exposes consumers to significant rights violations, prompting calls for stricter regulatory alignment between the new AI Basic Act and financial supervisory rules.
Local view
South Korea: Regulatory Friction and Control Gaps Local stakeholders are highlighting the disconnect between the speed of AI adoption and the maturity of governance frameworks. Herald Economy reports that while AI is deeply embedded in insurance claims processing, the lack of formal control structures (present in only 7.5% of firms) is a critical vulnerability. Meanwhile, Global Economic notes that insurers are calling for the resolution of overlapping regulations between the upcoming "AI Basic Act" and existing FSS guidelines to avoid compliance paralysis. The Digital Today outlet covered the CSBS framework, noting its significance as the first detailed inspection guide for generative AI, which fills a void left by federal US regulators.
Context & numbers
- 7.5%: Percentage of South Korean insurance companies that have established dedicated AI control bodies as of September 2026.
- $394 Billion: Estimated size of the fintech market in 2026, which is increasingly shifting toward agentic AI deployments that require new governance models. (Note: Market context from recent industry analysis)
- September 16, 2026: Date of CSBS AI Supervisory Framework release, marking a key milestone in US state-level AI regulation.
On the radar
- US Federal Guidance Gap: While states move forward, the OCC, Fed, and FDIC continue to exclude generative AI from traditional model risk management (SR 11-7), relying instead on general governance principles. Banks must navigate this dual-track regulatory environment carefully.
- AI Liability Insurance Products: Watch for the emergence of specialized "AI liability" insurance products in Q4 2026, as insurers attempt to model the risk of autonomous agent failures in banking workflows.
- Korean AI Basic Act Implementation: The finalization of enforcement decrees for Korea's AI Basic Act will likely force the remaining 92.5% of insurers to rapidly establish AI control committees or face penalties.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
