
Power for AI: Grid Queues, Nuclear PPAs, Gas Turbines — 2026-10-04
Germany reports grid connection delays reaching 13 years for AI data centers; Siemens Energy lands major gas turbine orders as demand surges; behind-the-meter power architectures gain traction with 400 MW campus projects announced.
Power for AI: Grid Queues, Nuclear PPAs, Gas Turbines — 2026-10-04
Top developments
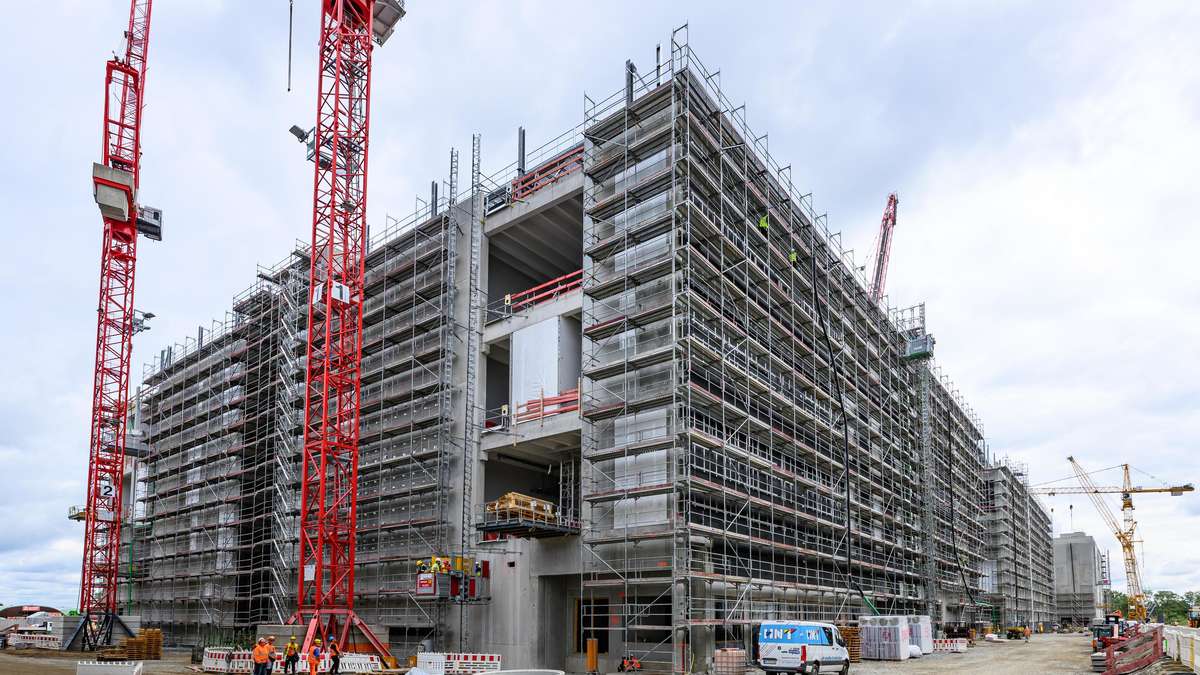
Germany's Grid Connection Crisis: 13-Year Wait for AI Data Centers
Data centers seeking grid connections in Germany now face waits of up to 13 years, particularly in the Frankfurt am Main region, as AI-driven electricity demand explodes. Network operators across Europe struggle to expand transmission capacity fast enough to serve hyperscaler buildouts. This bottleneck is reshaping where companies locate facilities and spurring investments in behind-the-meter generation solutions.
Siemens Energy Lands 119-Turbine Order; Fiscal 2026 Guidance Confirmed
Siemens Energy announced a major order from Dynamis Power Solutions for 119 SGT-400 gas turbine cores and confirmed its fiscal 2026 revenue growth guidance of 14–16%, with earnings trending toward the upper end. The company is reactivating production capacity to meet surging demand as utilities and data center operators accelerate gas-fired generation deployment to fill near-term power gaps before new nuclear assets come online.
Behind-the-Meter AI Campus Power: JERA, Dell and RHAELM Plan 400 MW Installation
JERA, Dell, and RHAELM are developing a 400 MW behind-the-meter AI campus designed to bypass interconnection queue delays by generating power directly on-site. This model—pairing on-campus generation with grid interconnection—reflects a shift toward self-sufficiency as utilities and grid operators struggle to provision capacity fast enough. Amazon signed a Calvert Cliffs nuclear power purchase agreement, further diversifying the corporate power architecture playbook beyond traditional utility contracts.
Global Data Center Power Demand Surges 31% Year-Over-Year in 2026
TrendForce estimates global data center power demand capacity will reach 161 GW in 2026, up approximately 31% year-over-year, driven by accelerating AI server deployments. The research firm warns that a grid supply gap will widen in 2028 if generation capacity does not expand in parallel, amplifying pressure on utilities, grid operators, and power equipment manufacturers.
Data Center-Driven Load Growth Reshapes Renewable Energy Market
U.S. grid planners now forecast annual electricity demand growth of 0.9–1.6% through 2050, with data centers emerging as a major driver alongside manufacturing. This sustained demand growth is reshaping capacity procurement, renewable energy contracting, and utility capital expenditure priorities, accelerating investment in solar, wind, gas turbine backup, and nuclear restarts.
Local view
German media (Merkur, Börse Global, Börse Express) report that Siemens Energy is accelerating turbine production ramp-ups, with Deutsche Bank reiterating a 210-euro price target and analysts highlighting the company's full order book extending to 2028. The grid connection crisis is dominating German utility discussions, with industry stakeholders flagging that Frankfurt-area data centers may need to explore alternative siting or invest in massive behind-the-meter generation to meet timeline expectations.
Japanese media (Nikkei) reports Mitsubishi Heavy Industries' U.S. division expects 2026 gas turbine demand to meet or exceed 2025 levels, citing sustained AI-driven electricity demand. Mitsubishi is doubling large gas turbine production capacity by fiscal 2030 (relative to fiscal 2024) and investing over 100 billion yen across U.S. and Japan manufacturing bases to meet global demand.
Context & numbers
-
PPA pricing (restarted nuclear): Levelized Cost of Energy for restarted nuclear plants ranges $70–95/MWh; hyperscaler deals with Vistra and Constellation Energy imply premium pricing near $110–115/MWh for 20-year contracts.
-
Interconnection backlog: MISO reported 192 GW of pending interconnection requests plus 87 GW of signed generation interconnection agreements not yet built (2026 OMS survey).
-
Nuclear PPAs in force: Vistra holds ~3.8 GW in 20-year nuclear PPAs (1.2 GW Comanche Peak/AWS in ERCOT; 2.6 GW with Meta across PJM plants including 433 MW uprates); Meta's Three Mile Island 835 MW restart supported by 20-year Constellation Energy PPA.
-
Global data center power: 161 GW expected capacity in 2026 (31% YoY growth); 2024 baseline was 192 TWh of electricity consumption (4.7% of U.S. total) across 3,300+ tracked facilities; 970+ facilities under construction or planned.
-
Gas turbine lead times: GE Vernova reported 2031 as earliest delivery slot for new orders, with bookings extending beyond 2026 in a fully committed pipeline.
On the radar
-
FERC large-load tariff rules: Six grid operators must rewrite interconnection rules for data centers ≥20 MW within 60 days; expect accelerated filings and revised cost-allocation mechanisms by late October/November 2026.
-
Siemens Energy results: Fiscal 2026 results and forward guidance due November 11, 2026; market watching for margin confirmation and updated turbine backlog visibility.
-
SMR deployment timelines: New nuclear reactors (including small modular reactors) unlikely to energize before 2035 for most projects; industry consensus points to gas and nuclear restarts as near-term solutions through 2030.
-
Rate case filings: State regulators in PJM, ERCOT, and MISO regions preparing responses to data center cost-shifting concerns; expect new tariff proposals and cost-recovery mechanisms by Q4 2026.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
