
EV Batteries and Charging: LFP, Solid-State, CATL, LG — 2026-10-01
CATL begins trial production at its 100 GWh Debrecen plant while Korean makers pivot to energy storage to offset EV demand softness. Volkswagen deepens ties with Chinese battery maker Gotion via $3.7 billion Europe-Africa investment, and solid-state battery manufacturing patents from Samsung SDI, LG Energy Solution, and SK On signal a shift from materials races to production scalability.
EV Batteries and Charging: LFP, Solid-State, CATL, LG — 2026-10-01
Top developments
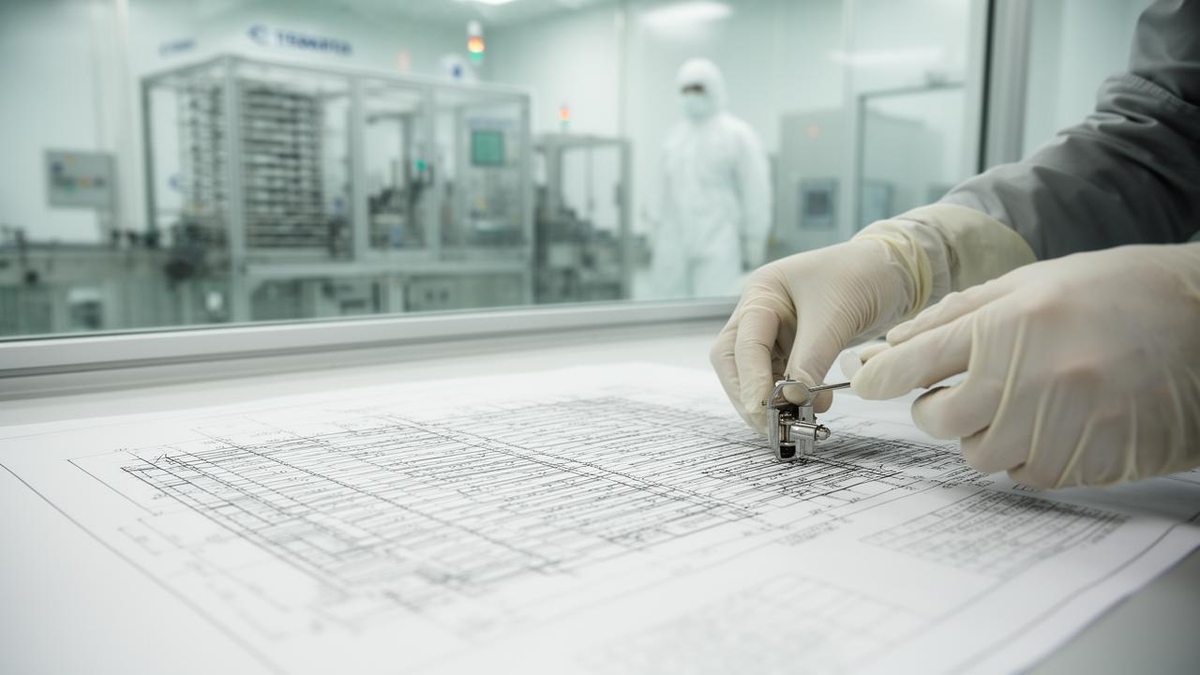
CATL Starts 100 GWh Debrecen Plant Trial Production in Hungary
CATL has begun trial cell production at its newly built 100 GWh facility in Debrecen, Hungary, marking a significant milestone in the Chinese battery giant's European expansion. The plant represents a critical step toward localized LFP and prismatic cell manufacturing outside China and is expected to reach full operational capacity over the coming months.

Volkswagen Invests $3.7 Billion With Chinese Partner Gotion for European and North African Battery Plants
Volkswagen and Gotion High-Tech announced a €3.22 billion ($3.7 billion) joint investment in battery manufacturing across Europe and North Africa, including facilities in Morocco, Slovakia, and Spain. The deal underscores Volkswagen's strategy to build an EV supply chain independent of full China reliance while tapping lower-cost LFP production. This partnership will supply mass-market EVs with competitive lithium-iron-phosphate cells.
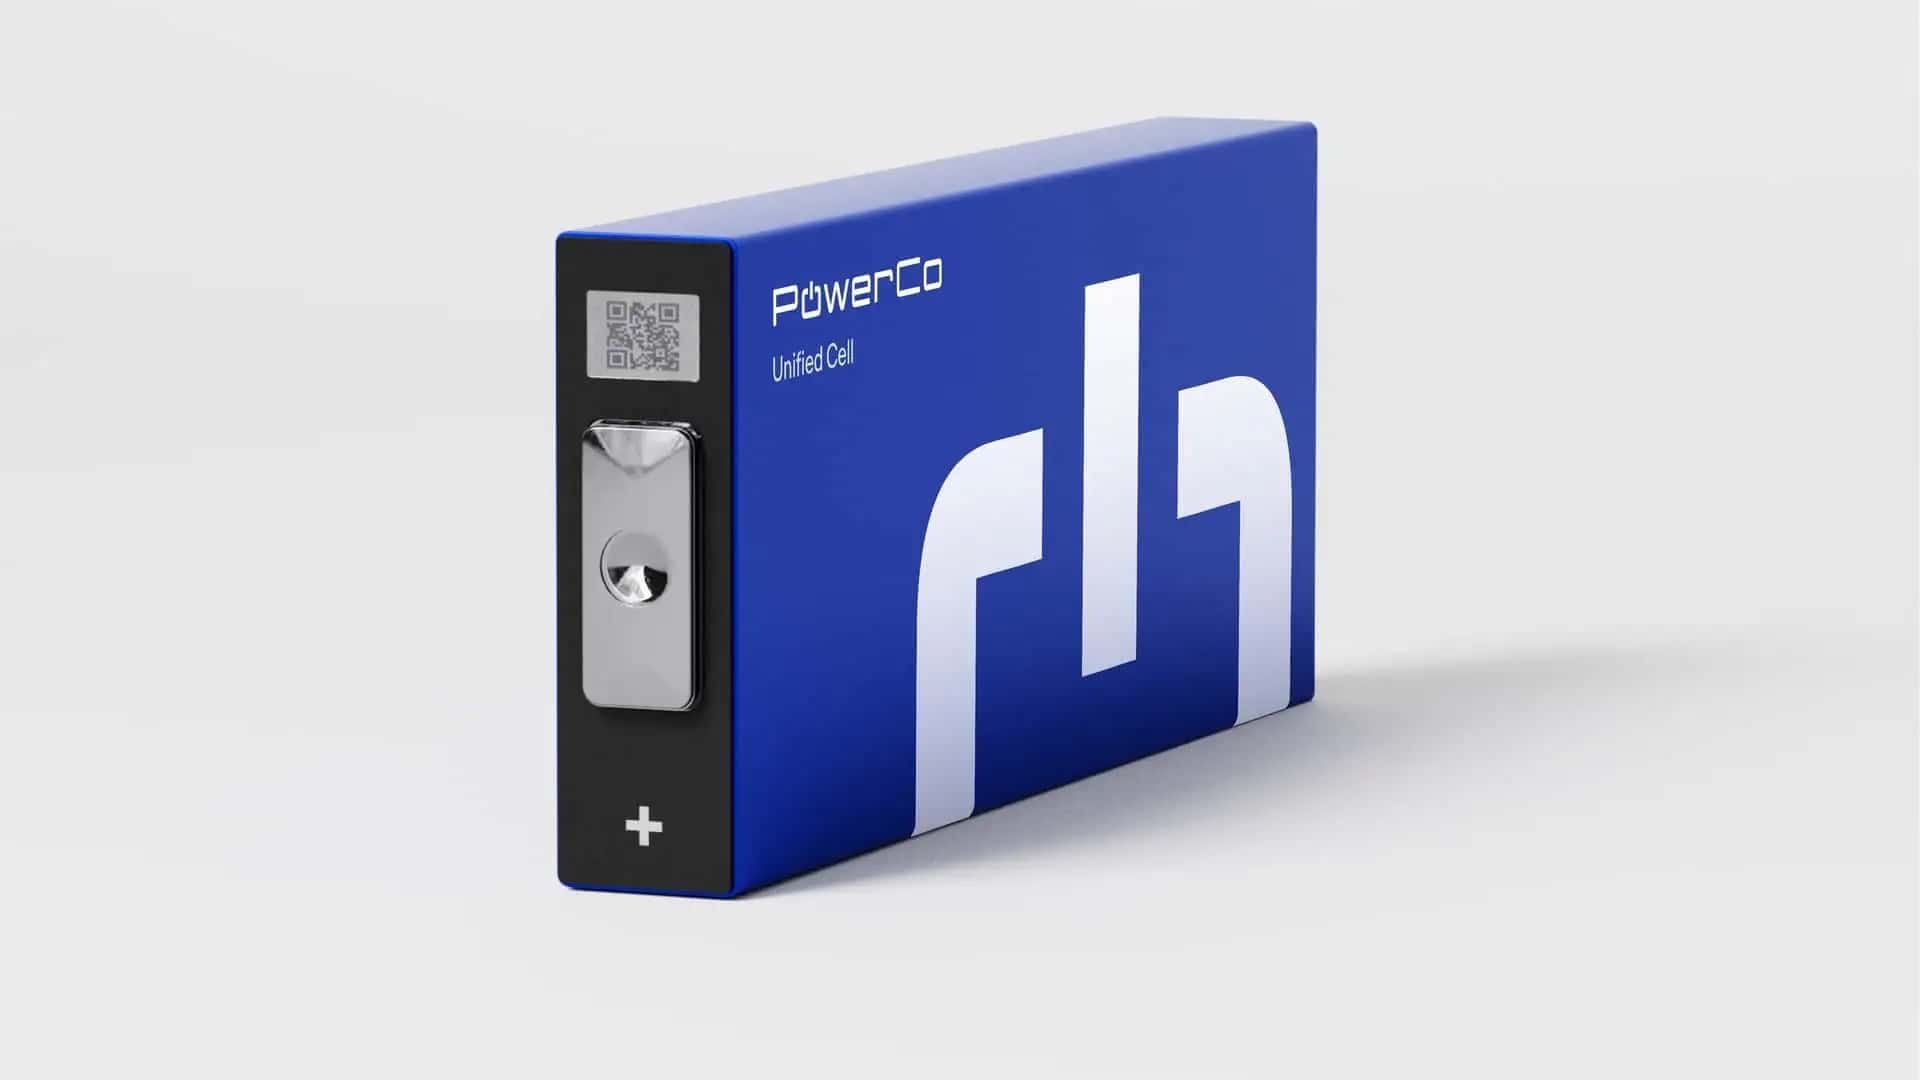
Solid-State Battery Patents Signal Manufacturing Shift, Not Materials Race
Samsung SDI, LG Energy Solution, and SK On have filed patents in September 2026 directly tied to solid-state battery mass production, covering electrode architecture, electrolyte containment, and layer-stacking processes rather than material chemistry alone. This pivot indicates the industry is moving from lab validation to factory-scale challenges.
Korean Battery Makers Surge on U.S. ESS Revenue Amid EV Softness
LG Energy Solution, Samsung SDI, and SK On are posting stronger-than-expected Q3 earnings driven by energy storage system (ESS) contracts in the United States, where AI data center demand and renewable integration are driving a 1 TWh storage target by 2032. Korean makers are converting idle EV battery lines to LFP production for stationary storage, offsetting weak passenger vehicle demand.
General Motors Confirms LMR Battery Production at Spring Hill with LG Energy Solution
General Motors has finalized plans to mass-produce next-generation lithium-manganese-rich (LMR) cells at its Spring Hill facility in partnership with LG Energy Solution, signaling U.S. automakers' commitment to advanced anode-cathode chemistry beyond conventional LFP and ternary platforms.

Local view
China (Sina/WeChat): CATL maintains 41.45% market share in August 2026 domestic shipments (32.54 GWh), but "de-CATL" trends are accelerating as second-tier makers—China National Aviation High-Tech Capital backing Chinese aviation tech, Guoxuan, SVOLT—expand capacity to 600+ GWh combined by 2027. BYD's battery external supply begins ramping 2027, threatening CATL's captive advantage. Chinese state policy targets full solid-state batteries at scale by 2030.
South Korea (Chosun Biz, News1): Korean battery 3-pack (LG Energy, Samsung SDI, SK On) are bidding aggressively on Korea's third round of 1.18 GW ESS central auction, with emphasis on domestic raw material sourcing and supply-chain localization to counter U.S. foreign-content restrictions. ESS revenue is expected to exceed EV revenue for Q3 2026 for Samsung SDI and LG Energy Solution due to U.S. policy tailwinds blocking Chinese battery imports.
Context & numbers
- Global EV battery market share (Jan–Apr 2026): CATL leads with 40.1% (141.4 GWh), BYD second with 14.4% (87.7 GWh). CATL's non-China market share outside China reached 54.9 GWh from Jan–Apr 2026, a 36% YoY increase.
- Q3 2026 ESS outlook: LG Energy Solution earnings expected 30% above consensus; Samsung SDI ESS revenue 2.3× higher YoY due to U.S. storage demand and IRA policy support.
- Charging network expansion: Tesla added 163 Supercharger stations (2,159 ports) in H1 2026. Ionna fast-charging network doubled to 180+ sites with up to 400 kW per port, supporting both NACS and CCS.
- NACS adoption: Stellantis vehicles gain Tesla Supercharger access starting early 2026 in North America; Japanese and Korean markets follow 2027.
On the radar
- Volkswagen Ontario plant delay: PowerCo pushed back St. Thomas, Ontario battery plant opening to 2029 (from 2027), citing demand adjustments and technology refinement.
- China's 2030 solid-state target: Seven-ministry roadmap targets full solid-state battery scaling by 2030; CATL and BYD expected to begin production trials 2026–2027.
- LFP pricing compression: Chinese LFP cell costs now undercut ternary lithium in premium segments (25+ kWh/dollar at volume), prompting mid-market EV adoption of chemistry once reserved for mass-market models.
- Geely–Nio battery-swapping merger talks: Two Chinese EV makers announced consolidation of charging and swapping operations, signaling industry consolidation in retail energy infrastructure.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
