
EV Batteries and Charging: LFP, Solid-State, CATL, LG — 2026-09-14
CATL and BYD continue to dominate the global EV battery market, holding nearly 55% combined share in early 2026, while Chinese LFP battery prices drop significantly. In South Korea, LG Energy Solution, Samsung SDI, and SK On are pivoting aggressively toward Energy Storage Systems (ESS) to offset EV demand stagnation, with SK On securing a massive $1 billion+ US contract. Meanwhile, GM is accelerating domestic battery supply chain development amid heightened scrutiny of Chinese ties in the US automotive sector.
EV Batteries and Charging: LFP, Solid-State, CATL, LG — 2026-09-14
Top developments
Korean Battery Makers Shift Focus to ESS Amid EV Chasm
As electric vehicle demand growth slows ("chasm"), major Korean battery manufacturers are successfully pivoting to the Energy Storage System (ESS) market. LG Energy Solution, Samsung SDI, and SK On achieved simultaneous operating profits in Q2 2026 for the first time since 2024, driven largely by ESS sales tied to AI data centers and grid stability needs. SK On recently secured a significant ESS battery contract in the United States worth approximately 1.5 trillion KRW (~$1.1 billion USD), covering 9 GWh of capacity, marking its first major overseas order of the year. This strategic shift allows these companies to maintain production lines and profitability while EV-specific demand fluctuates.
CATL and BYD Extend Lead in Global Market Share
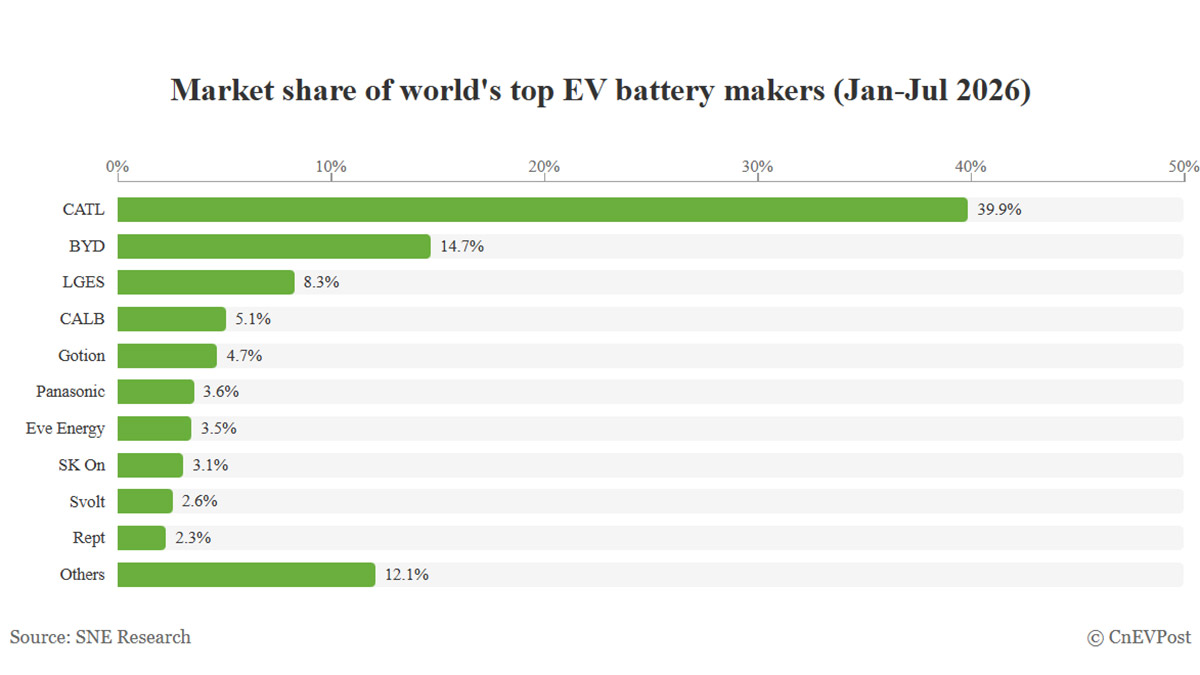
According to SNE Research data released in early September, CATL maintained its position as the global leader with a 39.9% market share from January to July 2026, while BYD held second place with 14.7%. The combined share of the top seven Chinese companies reached 72.8%, underscoring the dominant role of Chinese manufacturers in the global supply chain. Global EV battery usage totaled 725.2 GWh during this period, a 20.4% year-on-year increase, with CATL’s growth outpacing BYD’s slower expansion.
GM Pushes for Domestic Battery Supply Chain
General Motors is actively seeking to establish domestic battery cell supply chains in the United States for both EVs and energy storage, responding to political pressure and supply chain vulnerabilities. This move comes amidst heightened scrutiny by the US Department of Transportation regarding automakers' ties to Chinese battery suppliers, specifically targeting Ford. GM’s initiative aims to reduce reliance on raw materials and cells sourced from China, aligning with broader US efforts to secure critical mineral independence.

LFP Prices Drop, Enhancing Chinese Cost Advantage
Chinese manufacturers CATL and BYD are driving down Lithium Iron Phosphate (LFP) battery prices, creating a significant cost advantage over Western competitors. Reports indicate that Chinese battery packs are now approximately 30% cheaper than their global counterparts due to scaled manufacturing and lower material costs. This price differential is forcing other global players to re-evaluate their cost structures or pivot to higher-margin niches like solid-state or specialized chemistry batteries.
Local view
In South Korea, media outlets like Financial News and Sedaily highlight the "K-Battery" industry's resilience through diversification. Financial News notes that LG Energy Solution is expanding its North American ESS production bases, including in Holland, Michigan, to capitalize on the AI-driven energy demand. Gokorea reports that the competition among LGES, Samsung SDI, and SK On for LFP-based grid storage contracts has intensified, with Tesla’s Megapack demand serving as a key driver for these orders. Additionally, News Post highlights that potential US regulations restricting Chinese-connected ESS providers could further benefit Korean firms that have already established non-Chinese supply chains.
Context & numbers
- Global Market Share (Jan-Jul 2026): CATL (39.9%), BYD (14.7%), Total Top 7 Chinese Firms (72.8%).
- Global Battery Usage: 725.2 GWh (+20.4% YoY).
- SK On US Order: ~1.5 trillion KRW ($1.1B USD) for 9 GWh of ESS batteries.
- Price Gap: Chinese EV battery packs are ~30% cheaper than global average.
- CATL Market Share (Ex-China): 54.9 GWh installed Jan-Apr 2026 (+36.0% YoY).
On the radar
- BYD Solid-State Timeline: Rumors circulating on Chinese social media suggest BYD may target mass production of solid-state batteries by 2027, though official confirmation is pending.
- US Policy Watch: Monitoring the US Department of Transportation's ongoing investigation into Ford’s battery supply chain ties to China, which could set precedents for other automakers.
- ESS Bidding: The upcoming third round of centralized ESS contract bidding in South Korea will be a key indicator of domestic demand and pricing power for LGES, Samsung SDI, and SK On.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
