
EV Batteries and Charging: LFP, Solid-State, CATL, LG — 2026-09-15
BYD’s executive vice president declared the company is "leading" the solid-state battery race with a first EV launch slated for 2027, challenging the dominance of incumbent players. Meanwhile, Korean battery giants LG Energy Solution and Samsung SDI are pivoting aggressively toward the Energy Storage System (ESS) market to offset EV demand slowdowns, with SK On securing a massive $1.1 billion (approx. 1.5 trillion KRW) US ESS order. In China, CATL faces significant stock volatility as automakers accelerate "de-CATL-ization" strategies, even as the company maintains its global market share lead.
EV Batteries and Charging: LFP, Solid-State, CATL, LG — 2026-09-15
Top developments
BYD declares lead in solid-state race
On September 14, 2026, BYD Executive Vice President Stella Li stated that the company holds "the leading position" in solid-state battery development. The announcement confirms plans to introduce its first EV equipped with solid-state technology in 2027, with mass production targeted for 2030. This move positions BYD ahead of many Western and Korean competitors who have recently delayed their own commercialization timelines due to manufacturing complexities.

Korean battery makers pivot to ESS as EV demand cools
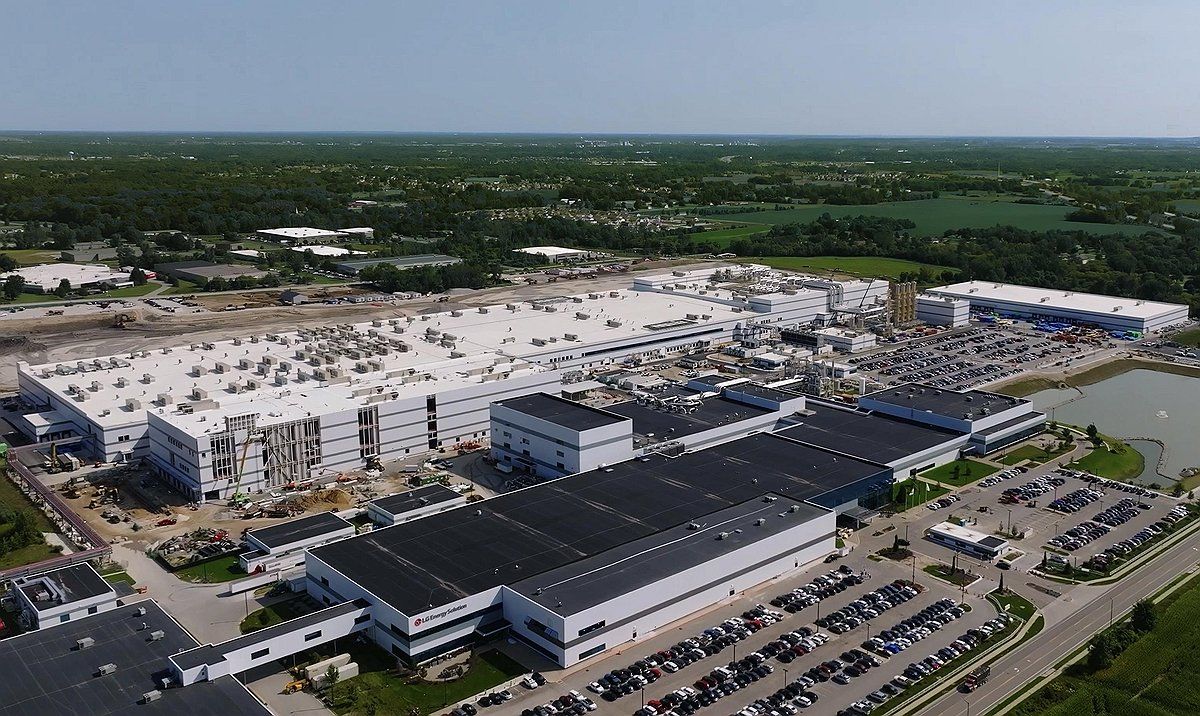
Amidst an EV "chasm" (slowdown), South Korea’s top three battery makers—LG Energy Solution, Samsung SDI, and SK On—are shifting growth focus to the Energy Storage System (ESS) sector driven by AI data center demand. On September 13, reports indicated that LG Energy Solution is expanding its North American ESS production bases, including in Holland, Michigan, while Samsung SDI has seen improved order visibility from customers like Sungrow. This strategic pivot is helping these companies achieve their first simultaneous quarterly profits since 2024.
SK On secures major US ESS contract
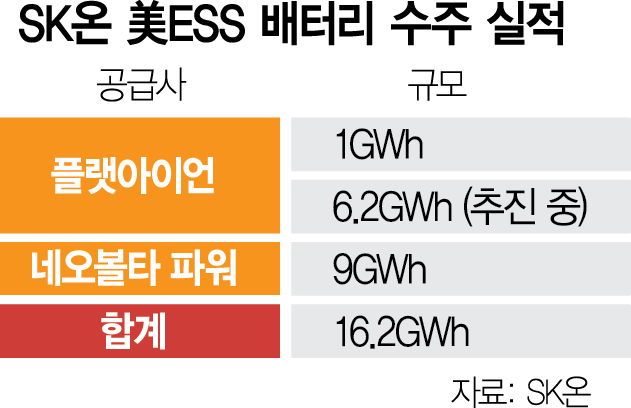
SK On has secured a battery cell supply contract worth approximately 1.5 trillion KRW ($1.1 billion) for energy storage systems in the United States. This deal, representing 9 GWh of capacity, accounts for nearly half of SK On’s annual overseas order target. The contract highlights the intensifying competition among Asian manufacturers to supply the rapidly growing US grid storage market, traditionally dominated by Chinese LFP cells but increasingly open to non-Chinese suppliers due to policy pressures.
CATL stock hits multi-month low amid "de-CATL-ization" fears
CATL’s A-share price fell to 327.10 RMB on September 9, marking its lowest point since March 2026, wiping out over 520 billion RMB in market value from recent highs. Analysts attribute this decline to a trend of Chinese automakers like Li Auto and Xiaomi diversifying their battery suppliers to reduce dependence on CATL. Despite the stock slump, CATL continues to hold the largest global market share, but the erosion of its monopoly power in China’s domestic market is reshaping industry dynamics.

GM pushes for domestic battery supply chain
General Motors announced on September 12 that it is accelerating efforts to establish domestic battery supply chains in the US for both EVs and energy storage. This move comes amid heightened political scrutiny regarding ties between Ford and Chinese suppliers. GM aims to reduce reliance on Chinese raw materials and cells, aligning with broader US policy goals to secure critical mineral independence, though analysts note that full decoupling from China remains difficult in the short term.

Local view
South Korea: Financial media outlets like Financial News and Alphabiz are highlighting the valuation re-rating of Samsung SDI. On September 15, NH Investment & Securities raised Samsung SDI’s target price by 22% to 730,000 KRW, citing stronger competitiveness in prismatic and cylindrical batteries for ESS applications. The consensus among Korean analysts is that the "EV chasm" is being bridged by the explosive demand for grid-scale storage, allowing Korean firms to maintain profitability despite soft EV sales.
China: Weibo discussions and local financial reports are focusing on the "tiering" of the global battery market. Recent posts highlight that while CATL remains the undisputed leader in the first tier, the gap with the second tier (LG Energy Solution and BYD) is narrowing in terms of technological capability, particularly in sodium-ion and solid-state sectors. There is also significant consumer interest in the cost differences between LFP and ternary lithium batteries for replacement parts, reflecting a more cost-conscious domestic EV market.
Context & numbers
- Global Market Share: From January to July 2026, global EV battery usage reached 725.2 GWh. CATL maintains its top position with a significant lead, though specific share percentages for this exact period are being consolidated in weekly industry reports.
- Korean Profitability: LG Energy Solution, Samsung SDI, and SK On achieved simultaneous quarterly profits in Q2 2026 for the first time since Q3 2024, driven largely by ESS orders rather than passenger EVs.
- SK On Order Size: The newly secured US ESS contract is valued at 1.5 trillion KRW (~$1.1 billion USD), covering 9 GWh of capacity.
- BYD Timeline: First solid-state EV in 2027; mass production in 2030.
On the radar
- Samsung SDI Target Price: Watch for further analyst upgrades following the recent 22% target price hike, which signals confidence in the ESS-driven earnings recovery.
- CATL Stock Volatility: Monitor if the "de-CATL-ization" trend leads to further supplier diversification announcements from major Chinese OEMs like Xiaomi or NIO.
- US Supply Chain Policy: Keep an eye on regulatory responses to GM’s domestic supply chain push, particularly regarding tariff exemptions for non-Chinese battery materials.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
