
ASEAN Stocks: VN-Index, JCI, SET, PSEi and KLCI — 2026-09-17
Vietnam’s stock market is witnessing a significant shift in foreign sentiment ahead of its September 21 FTSE Russell emerging market upgrade, with net foreign inflows reversing a three-year trend. Meanwhile, Indonesia’s Jakarta Composite Index (JCI) faced continued selling pressure from foreign investors, particularly in the banking sector, while Thailand’s SET Index rebounded sharply following easing concerns over US Federal Reserve interest rates.
ASEAN Stocks: VN-Index, JCI, SET, PSEi and KLCI — 2026-09-17
Top developments
Vietnam: Foreign Inflows Surge Ahead of FTSE Upgrade
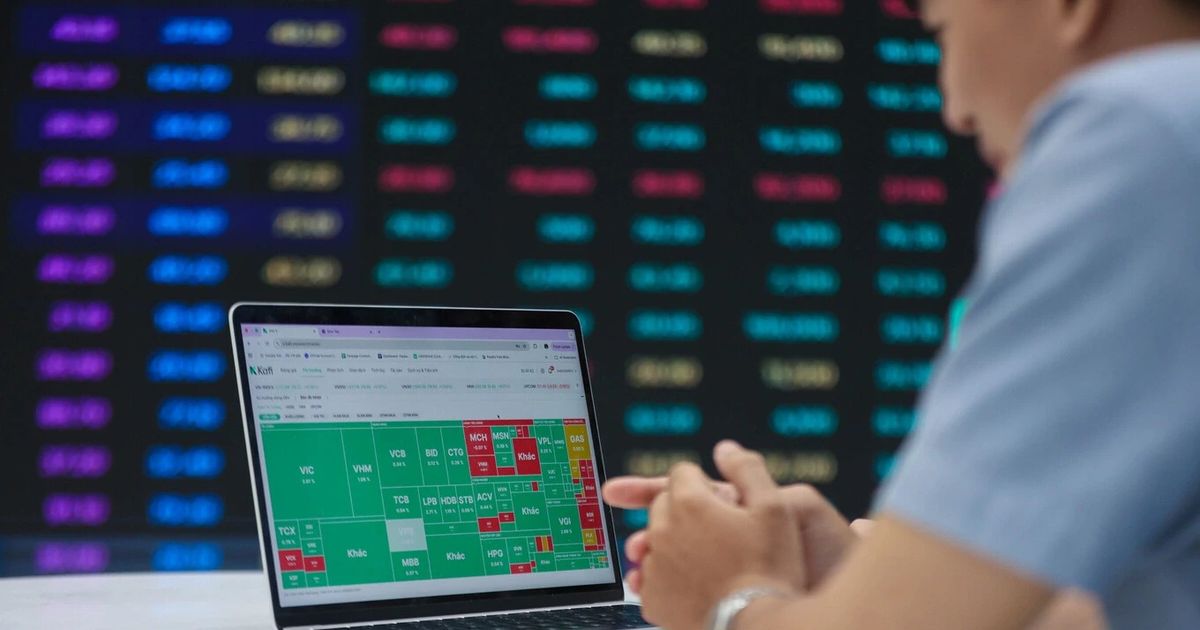
In the week leading up to the September 21 reclassification of Vietnam from Frontier to Secondary Emerging Market status by FTSE Russell, foreign investors have turned net buyers. On September 16, foreign investors recorded their third consecutive session of net buying, purchasing approximately 260 billion VND (approx. $10.4 million), marking a psychological shift after three years of consistent net selling. This trend was reinforced on September 15 and 16, where foreign funds accumulated over 30 million shares, the highest volume since April. The VN-Index closed at 1,800–1,810 points range (specifically noted as recovering to support levels around 1,800) as the "buying the news" phase begins ahead of the official inclusion date.
Indonesia: JCI Drops as Foreigners Dump Bank Stocks
The Jakarta Composite Index (JCI) closed down 0.38% at 6,436.00 on September 16, driven by heavy foreign selling of Rp624.72 billion ($39.8 million). The selling pressure was concentrated in major banking stocks, including BMRI, BBRI, BBNI, and BBCA, which had previously supported the index. This follows a turbulent week where the JCI fell 1.7% on September 14 amid geopolitical tensions and US inflation concerns, with foreigners selling Rp664 billion in that single session. The cumulative foreign outflow for the week of September 7–11 reached Rp3.36 trillion, indicating persistent risk-off sentiment despite some domestic retail accumulation in specific mining stocks like AMMN.

Thailand: SET Rebounds on Fed Rate Relief
Thailand’s SET Index surged 20.61 points (+1.32%) to close at 1,583.34 on September 16, breaking a six-day losing streak that had erased over 55 points earlier in the week. The rally was fueled by broad-based buying in banking and electronics sectors after investors reassessed the likelihood of further aggressive rate hikes by the US Federal Reserve. Prior to this rebound, the SET had dropped to 1,562.73 on September 15 due to selling pressure in energy and tourism stocks, with foreigners net selling Rp7.2 trillion (approx. $200 million) that day. The Thai baht strengthened slightly to 33.36 per USD on September 16, reflecting reduced immediate currency pressure.
Regional Divergence: McKinsey Highlights Growth Split
A new McKinsey report released on September 16 highlights a growing divergence in ASEAN economic performance, with Vietnam and Malaysia gaining momentum through tech and export sectors, while Thailand and the Philippines face headwinds from weaker domestic demand. This macro backdrop is influencing stock performance, with Vietnam’s upgrade narrative providing a specific catalyst distinct from the broader regional slowdown concerns affecting Philippine and Thai equities.
Local view
Vietnam: Local financial media such as Vietbao and Investing.com VN emphasize the strategic importance of the current foreign inflows, describing them as "accumulation" ahead of the FTSE index rebalancing. Analysts suggest that while the VN-Index has recovered from its dip below 1,800 points, investors should remain cautious of potential profit-taking after the September 21 effective date.
Indonesia: CNBC Indonesia and Kompas Money report that the foreign exodus from blue-chip bank stocks (BMRI, BBCA) is the primary drag on the JCI. There is local debate regarding whether this selling is temporary or structural, with some analysts pointing to the recent change in the Finance Minister as a source of short-term uncertainty that has not yet been fully priced in.
Thailand: Bangkok Biznews notes that the sharp rebound in the SET was led by domestic institutional buyers who stepped in after the initial Fed-related sell-off subsided. The Prachachat business daily highlights that the six-day decline prior to the rebound was largely driven by global geopolitical fears, which have now temporarily receded.
Context & numbers
- VN-Index: Closed near 1,800–1,810 points (exact close varies by session, but held above 1,800 support). Foreign net buy: ~260 billion VND on Sept 16; >30 million shares accumulated in the week prior to Sept 15.
- JCI (Indonesia): Closed at 6,436.00 (-0.38%) on Sept 16. Foreign net sell: Rp624.72 billion on Sept 16; Rp3.36 trillion for the week ending Sept 11.
- SET (Thailand): Closed at 1,583.34 (+1.32%) on Sept 16. Prior low: 1,562.73 on Sept 15. Foreign net sell: 7,192.29 million THB on Sept 15.
- PSEi (Philippines): No fresh daily close data available for the specific dates post-Sept 10 in the provided sources, but context indicates continued foreign selling pressure similar to previous weeks (e.g., Sept 3 data showed net foreign selling).
- KLCI (Malaysia): No specific fresh daily close data available for the past 7 days in the provided sources.
On the radar
- September 21, 2026: FTSE Russell officially implements the upgrade of Vietnam to Secondary Emerging Market status. This is expected to trigger passive fund inflows estimated at $3 billion, contrasting with the $3.5 billion of foreign selling seen in 2026 so far.
- Indonesian Banking Sector: Watch for continued foreign selling in BMRI and BBRI, which are currently weighing on the JCI despite broader market attempts to stabilize.
- Fed Policy Impact: Thai and Indonesian markets remain highly sensitive to US Federal Reserve rhetoric. Any new hawkish signals could reverse the recent SET rebound and deepen JCI selling.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
