
Battery Metals and Rare Earths: Lithium, Nickel, Cobalt — 2026-10-03
Lithium carbonate prices in China have collapsed to 12-year lows, falling 21.8% since August to ¥122,400/tonne as supply outpaces demand and downstream battery production slows ahead of October. Heavy rare earth prices (dysprosium, terbium) have split into two divergent trading systems ex-China, with extreme scarcity premiums, while cobalt prices declined 31% in Q3 as DRC exports accelerated under new quota controls.
Battery Metals and Rare Earths: Lithium, Nickel, Cobalt — 2026-10-03
Top developments
Lithium Carbonate Plunges Past ¥122,400/Tonne Amid Supply Glut
Battery-grade lithium carbonate spot prices in China have fallen to ¥122,400/tonne as of late September—a 21.8% drop since August 31 (when prices stood at ¥157,000/tonne)—marking 2026's lowest level as downstream battery producers cut October production. Futures on the Dalian Commodity Exchange fell 5.69% on September 28 alone, piercing the ¥120,000 psychological support level. The collapse extends Q3's broader price reversal that began in June; both lithium feedstock and chemical prices dropped notably through July, rallied briefly in August, then reversed sharply in September.
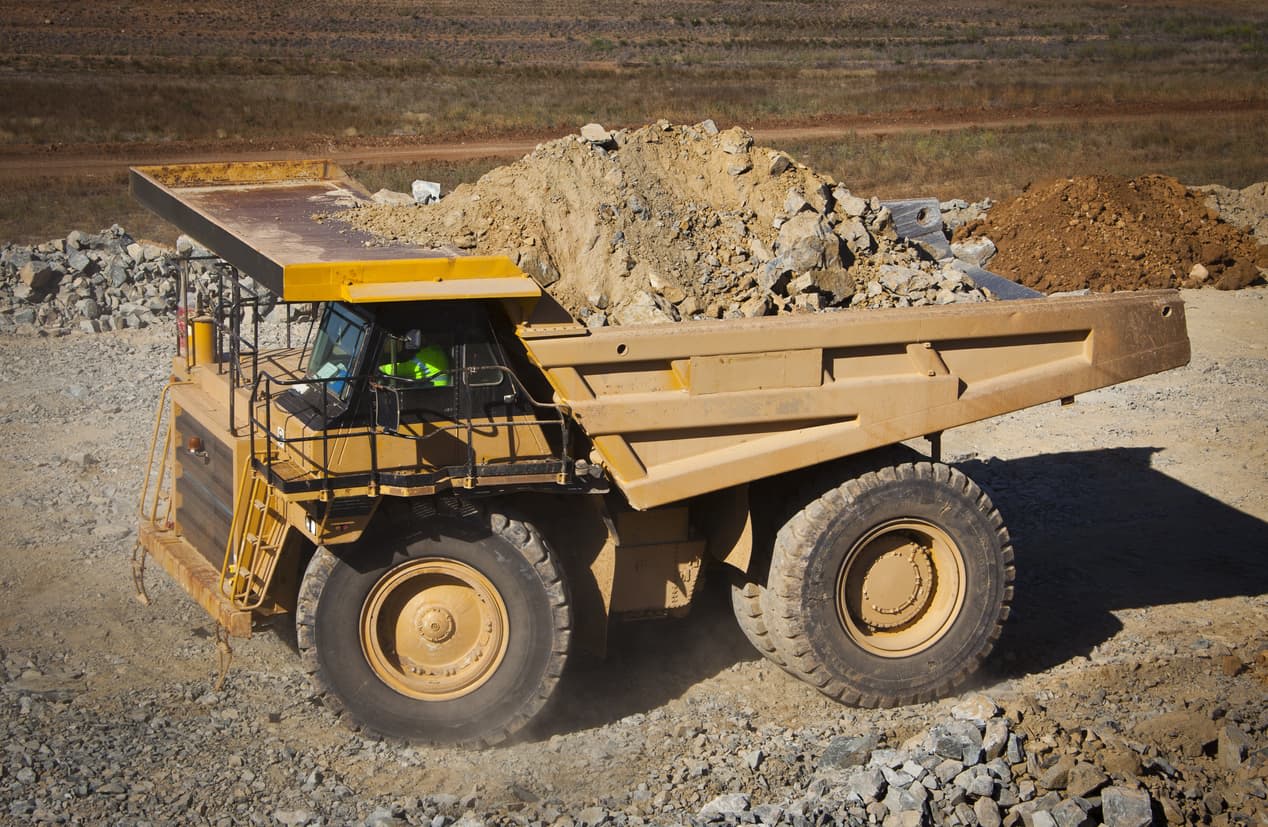
Cobalt Hydroxide Falls 31% in Q3 as DRC Export Quotas Flood Market
Cobalt hydroxide prices (CIF Asia) declined 31% across Q3 2026 to $17.25/lb ($38,030/tonne), while cobalt sulphate (EXW China) dropped nearly 30%, according to Benchmark Mineral Intelligence. The decline reflects increased exports from the Democratic Republic of Congo under strict new export quota regimes that are designed to manage but ultimately boosting supply to the market. Cobalt's spectacular rally—which tested Kinshasa's price control efforts—is now reversing as actual shipment volumes pick up.
Heavy Rare Earths Split Into Incompatible Pricing Systems; Dysprosium Hits $3,250/kg
Dysprosium (heavy rare earth) prices have reached $3,250/kg ex-China while terbium topped $12,000/kg in the past 24 hours, as the rare-earth market bifurcates into two separate trading ecosystems—one inside China and one outside—with extreme scarcity premiums on materials unavailable through official channels. Light rare earth prices (praseodymium-neodymium oxide) eased only 1% DDP China in Q3, but ex-China prices (CIF North America/Europe) fell more sharply, signaling geographic arbitrage pressures and disrupted global flows.
Indonesia Controls 41% of Global Refined Nickel; RKAB Imposes Production Limits
Indonesia now accounts for 41% of global refined nickel output, driven by aggressive hilirisasi (downstreaming) policy, yet domestic producers are now importing nickel from the Philippines—imports jumped 82% in January–July 2026—due to production cuts from the annual Raw Material Work Plan (RKAB). The government is balancing nickel supply management to support prices while maintaining feedstock for domestic smelters. Officials signaled continued push toward battery ecosystem development and advanced industrialization beyond simple smelting.
Indonesia Nickel and Cobalt Hit 2026 Lows; HMA at $16,322/Tonne
Nickel prices in Indonesia have fallen to 2026 lows with the Indonesian Nickel (HMA) spot rate at $16,322.67/tonne, while LME cobalt has slipped under $40,000/tonne. A new pricing mechanism now ties cobalt downside directly to miner payout schedules, intensifying producer exposure to spot volatility.
Local view
Chinese battery industry sources (Sina Finance, 21 Jingji) attribute the lithium collapse to persistent oversupply, weak downstream demand ahead of October holidays, and continued margin compression across the battery supply chain. Traders cite slowing EV sales growth and battery maker inventory corrections as demand headwinds.
Indonesian media (SEANTERONEWS, Suara.com, Detik.com) emphasize government success in scaling refined nickel capacity but flagged RKAB production quotas as a double-edged sword—price support versus operational constraints for smelters dependent on domestic ore. Ekonom sources call for next-phase hilirisasi focused on battery materials and EV components rather than raw ore export.
Spanish-language coverage (Ambito, Mejor Informado) noted Argentina's push to accelerate lithium production capacity, projecting 573,300 tonnes annually by 2035, positioning the country to rival Chile's output as global prices remain under pressure. The 15th annual Panorama Minero conference in Jujuy (October 7–8) will address production, investment, pricing, and geopolitical dimensions of South American lithium.
Context & numbers
| Metric | Current | Prior | Change |
|---|---|---|---|
| Lithium carbonate (China, CNY/tonne) | 122,400 | 157,000 (Aug 31) | −21.8% |
| Cobalt hydroxide (CIF Asia, $/lb) | 17.25 | ~25/tonne basis | −31% (Q3) |
| Dysprosium (ex-China, $/kg) | 3,250 | n/a | High scarcity premium |
| Terbium (ex-China, $/kg) | 12,000 | n/a | Extreme premium |
| Indonesia HMA nickel ($/tonne) | 16,322.67 | 2026 high ~18,500 | 2026 low |
| Indonesia refined nickel share | 41% | n/a | Global output |
| DRC cobalt output share | ~74% | 54% (2016) | Concentrated supply |
Supply concentration risk: The DRC's 74% share of global cobalt output underscores geopolitical vulnerability; export quota manipulation can rapidly reprrice the global market. Indonesia's 41% refined nickel dominance mirrors this risk asymmetry.
On the radar
-
November rare-earth export controls: China's previously announced but suspended export controls on rare earths, lithium batteries, and technologies remain in abeyance until late 2026. Market participants are monitoring MOFCOM announcements closely for renewal or modification of restrictions that could further fragment global pricing.
-
Q4 battery-production seasonality: Chinese battery makers typically cut production in September–October ahead of holidays; demand revival in November may re-stabilize lithium prices, though only if oversupply narratives shift.
-
Indonesia RKAB renewal cycle: Annual nickel and cobalt production quotas reset in Q4; industry watchers expect tight allocations to continue, with spillover imports from Philippines and Russia likely to persist.
-
Lithium Futures Technicals: Dalian LC2701 contract trading near ¥122,400 after breaking below ¥120,000 support; watch for capitulation or short-covering rallies if prices breach ¥115,000 levels.
Data freshness note: All prices and figures current as of October 2–3, 2026. Chinese-language sources (Sina, 21 Jingji, Mysteel) cited for same-week lithium assessments. Indonesian and Spanish-language coverage reflect latest regional production/policy signals.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
