
Battery Metals and Rare Earths: Lithium, Nickel, Cobalt — 2026-10-29
Lithium carbonate prices in China have plunged to a 10-month low amid demand concerns, while Indonesia finalized revised nickel production quotas and announced record export values. Meanwhile, the West continues to navigate the regulatory uncertainty surrounding China’s rare-earth export pause, which legally concludes on November 10, 2026.
Battery Metals and Rare Earths: Lithium, Nickel, Cobalt — 2026-10-29
Top developments
Lithium prices hit 10-month low as Chinese demand outlook weakens
Lithium carbonate prices in China fell to approximately CNY 98,000–107,000 per tonne in late October, marking a nearly 55% drop from early 2026 highs. This decline is driven by a "strong reality, weak expectation" dynamic, where current inventory drawdowns are offset by pessimistic forecasts for 2027 EV demand.

Indonesia finalizes 2026 nickel quotas and hits record export values
Indonesia’s Ministry of Energy and Mineral Resources (ESDM) reported nickel exports reached $25.96 billion by August 2026, with downstream processed exports hitting IDR 472 trillion. The government has officially approved revised 2026 production quotas (RKAB) at 290–300 million metric tons, aiming to stabilize prices and boost value-added exports.
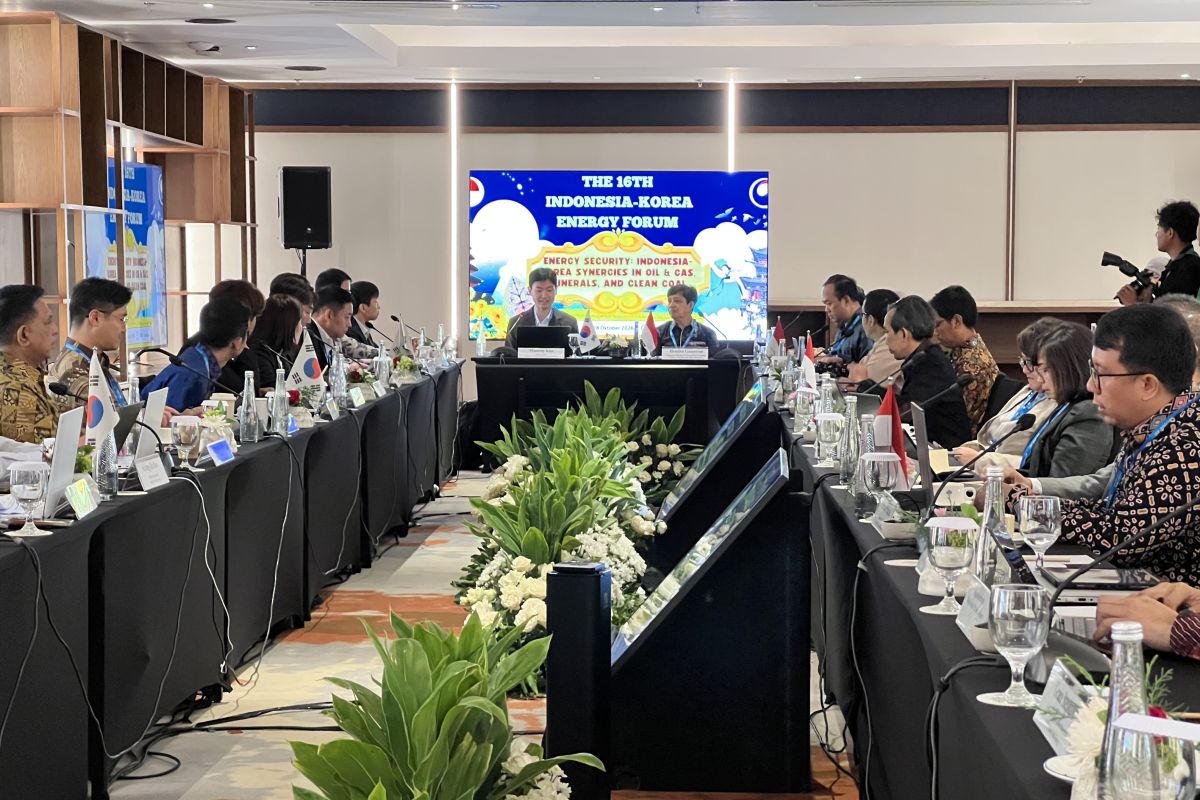
Rare-earth trade flows remain constrained ahead of policy deadline
Silverado Policy Accelerator reports that rare-earth trade flows into the U.S. were significantly impacted by China’s export controls through September 2026. With the temporary pause on certain controls legally expiring on November 10, 2026, Western producers are accelerating diversification efforts to mitigate supply risks.

Latin American lithium sector sees mixed signals
While Chile’s lithium spot price fell to US$16,050/tonne on October 20, the lowest since January, regional production is expanding. Salta Province in Argentina now hosts nine major projects aiming to multiply exports by 2035, and Rio Tinto announced a $4.4 billion investment in Argentine lithium operations.
Local view
In Indonesia, local media like CNBC Indonesia and Media Nikel Indonesia are highlighting the tension between production cuts and revenue growth. Analysts note that despite RKAB production cuts, nickel export values rose 28% due to higher processed product prices. However, spot prices for nickel ore have weakened due to the shutdown of several RKEF smelter lines, creating short-term volatility for miners.
In China, financial outlets like 21jingji and Huxiu are focusing on the "profit redistribution" across the lithium supply chain. They report that while lithium salt producers like Ganfeng Lithium and Tianqi Lithium saw massive profit increases in Q3 due to earlier price highs, downstream battery makers are benefiting from the current raw material cost collapse.
Context & numbers
- Chinese Lithium Carbonate: ~CNY 98,000–107,000/tonne (battery grade), down ~55% from early 2026.
- Chile Lithium Price: US$16,050/tonne (Oct 20), lowest since January.
- Indonesia Nickel Exports: $25.96 billion through August 2026; IDR 472 trillion in downstream exports.
- Indonesia Nickel Quota (RKAB): Revised to 290–300 million metric tons for 2026.
- Cobalt Market: Deficits loom despite DRC export quotas easing shortages; Indonesia’s nickel policies add supply risk.
On the radar
- November 10, 2026: The legal expiration of China’s temporary pause on specific rare-earth export controls.
- Q4 Supply Adjustments: Watch for further RKEF smelter restarts in Indonesia, which could impact nickel ore spot prices.
- DRC Export Backlogs: Monitor the shipment of previously un-exported cobalt material as the DRC’s quota system stabilizes.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
