
Battery Metals and Rare Earths: Lithium, Nickel, Cobalt — 2026-09-30
Lithium carbonate prices are accelerating downward in China, breaking through critical support levels as pre-holiday trading winds down. Indonesia has cemented its position as the world's largest refined nickel producer at 41% global output, while nickel import pressures from the Philippines surge due to domestic production quotas. Rare earth export controls remain suspended through November 2026, easing immediate supply concerns.
Battery Metals and Rare Earths: Lithium, Nickel, Cobalt — 2026-09-30
Top developments
Lithium carbonate crashes through support in China ahead of holidays
Battery-grade lithium carbonate prices in China accelerated their decline this week, falling through the 130,000 yuan/tonne and 125,000 yuan/tonne support levels as pre-holiday liquidation dampened trading activity. The Shanghai Metals Market (SMM) reported that by late September, lithium carbonate prices hit their lowest points in recent weeks, with sluggish market transactions as traders squared positions before the break. The weakness reflects ongoing oversupply concerns despite earlier hopes for market stabilization.
Indonesia surges to 41% of global refined nickel, pressuring domestic imports
Indonesia now commands 41% of the world's refined nickel production, having displaced China as the largest producer, according to reports from September 28–29. However, this dominance masks a growing internal contradiction: nickel imports from the Philippines jumped 82% in the January–July 2026 period due to production quotas (RKAB) that constrained domestic raw ore availability. The supply crunch forced Indonesian smelters to source ore abroad even as the country's refining share expanded globally. Economists stress that quota-setting must balance producer controls with smelter feedstock needs.
Nickel and cobalt payables decline sharply; black mass pressures mounted
Benchmark Mineral Intelligence's Q3 2026 black-mass review showed that NCM (nickel-cobalt-manganese) black mass payables in China fell 4.9% from Q2 to Q3, dropping to 73.3%. LCO (lithium-cobalt-oxide) black mass payables contracted even more steeply, with lithium carbonate payables and cobalt sulphate both declining 7.5% and 13.2% quarter-on-quarter respectively. The compression reflects lower spot prices for battery metals and increased recycling supply competing with primary ore.
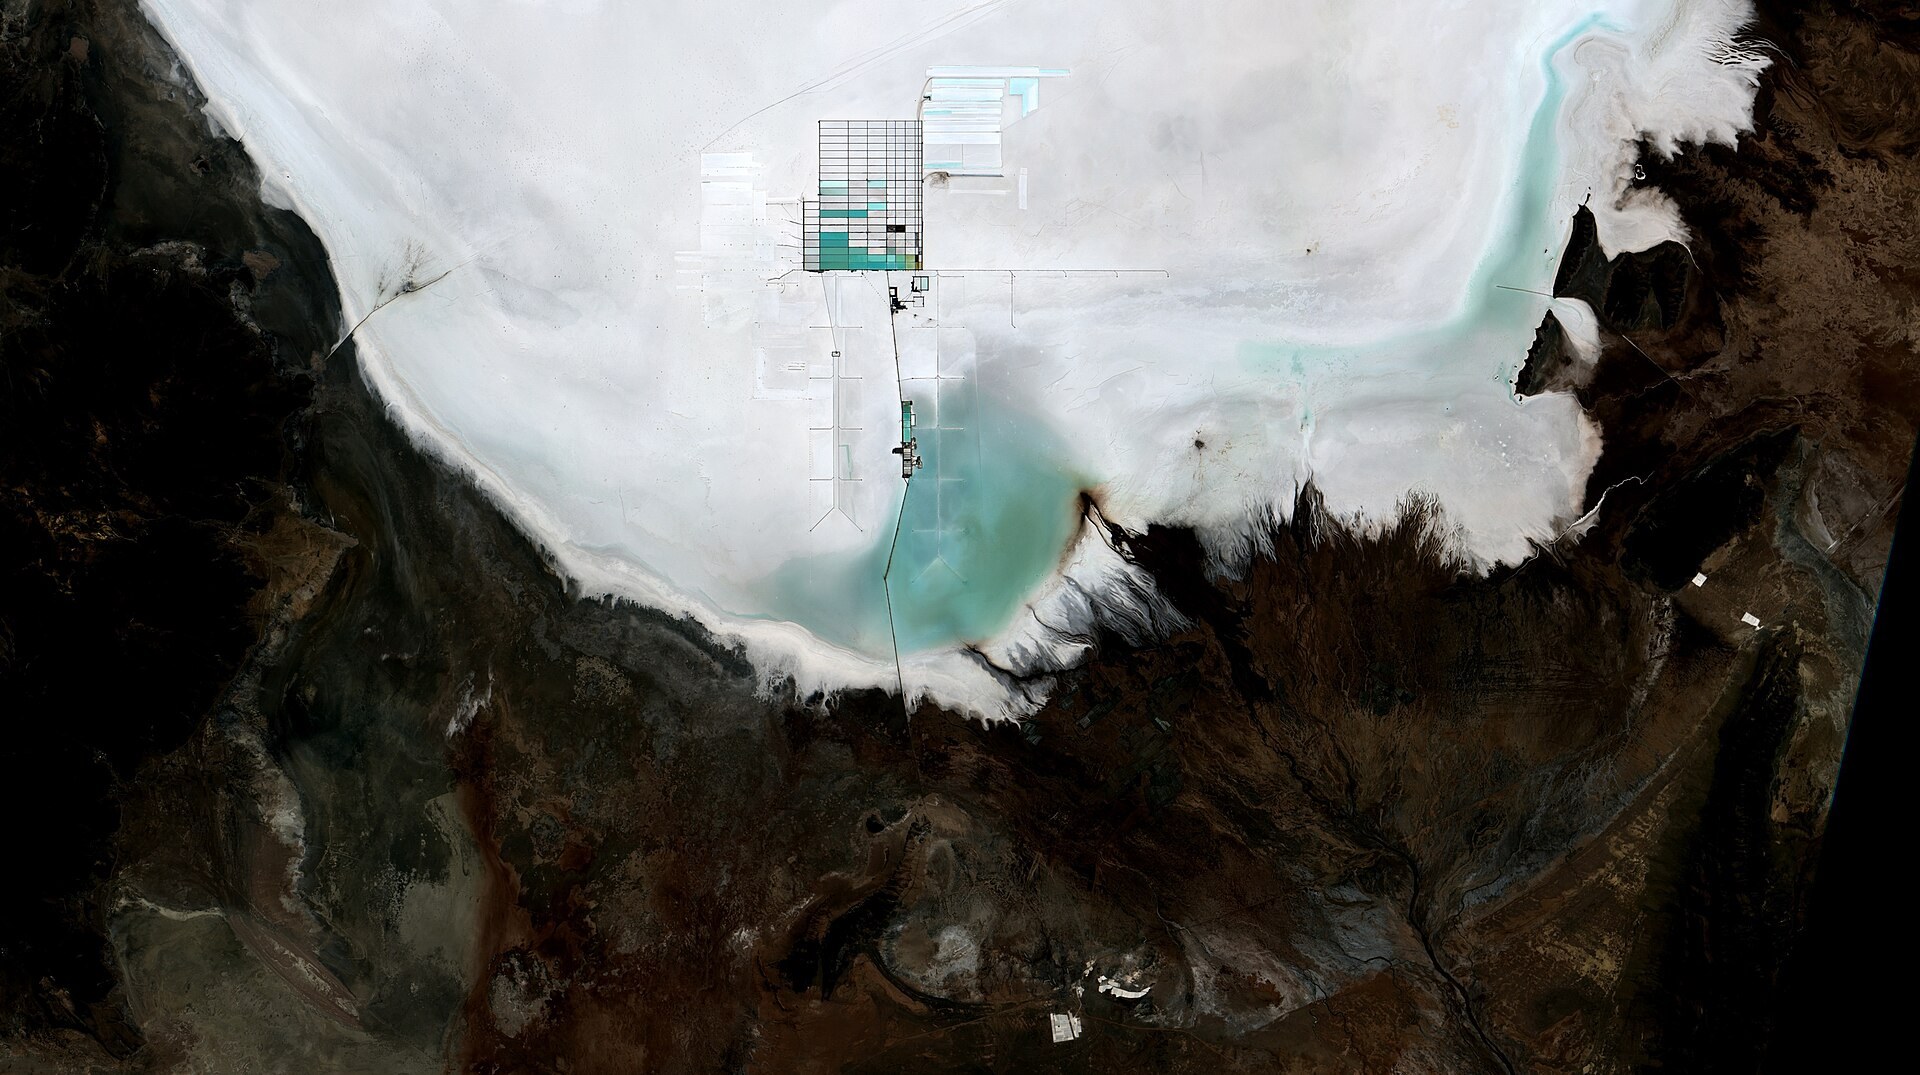
Chile's lithium markets split: SQM gains while carbonate futures falter
SQM rose 1.41% on September 30, reaching US$66.08, even as China's lithium carbonate futures extended declines. The divergence reflects regional market dynamics: Latin American producers are adjusting to lower-for-longer carbonate pricing, while global equity markets price in longer-term demand recovery from EV sector strength.
Local view
Chinese sources (Mysteel, Shanghai Metals Market, 21财经): Mysteel and SMM reporting on September 28–30 emphasized that lithium carbonate's collapse below 125,000 yuan/tonne marks a transition into "accelerated bottoming" mode, with pre-holiday traders avoiding risk. A 21财经 (21Finance) report on September 28 noted that LC2701 futures fell 5.69% to break the 120,000 yuan/tonne barrier, the year's low, blamed on long liquidation rather than fundamental deterioration. Chinese market participants attributed weakness to soft EV demand signals from domestic battery makers ahead of the October Golden Week holiday.
Indonesian media (Suara, ANTARA, IDN Times): Indonesian outlets from September 28–29 celebrated the nation's 41% global nickel refined output share as a victory for hilirisasi (downstream processing) policy. However, they also flagged the RKAB (quotas) as creating perverse incentives: smelter operators are forced to import Philippine ore because domestic raw-ore production is capped, even though Indonesia dominates refining. The Center of Reform on Economics (CORE) and other economists quoted in ANTARA News and other outlets warned that policymakers must calibrate quotas to avoid starving downstream capacity.
LatAm sources (Rio Times, Mineriaenlinea): Rio Times' daily lithium wraps (Sept. 28–30) tracked SQM and Albemarle stock moves in tandem with China futures, emphasizing that spot-price declines are not translating into equity weakness for major producers. This suggests market confidence in long-term demand recovery once surplus inventory clears.
Context & numbers
Lithium carbonate (China, EXW basis):
- Late September: ~125,000–130,000 CNY/tonne (accelerating downward)
- Weekly moves: Breaking support levels on holiday liquidation
- Q3 trend: Eased ~1% over the quarter per Benchmark Mineral Intelligence; spot weakness vs. futures long liquidation
Nickel sulphate (EXW China):
- Late September: ~28,500 CNY/tonne (~US$4,247)
- Q3 change: Down 13% from Q2 end per Benchmark
- Driver: DRC nickel export resumption and softening battery demand
Indonesia's nickel position:
- Refined nickel production: 41% of global output (2023 baseline: 1.4+ million tonnes annually)
- Philippine imports: +82% YoY (Jan.–Jul. 2026) due to RKAB quotas squeezing domestic raw ore supply
- Status: Now world's largest refined nickel producer (displaced China)
Rare earth export controls:
- Current status: Suspended through November 10, 2026 (announced November 7, 2025)
- No immediate export restrictions in effect; deadline for re-evaluation: 10 November 2026
- Market implication: Relief for non-China buyers; pricing normalizing ex-China
LIT ETF & majors (Sept. 28–30):
- LIT (Global X Lithium ETF): US$69.02 (small gains despite China price declines)
- SQM: US$66.08 (+1.41% on Sept. 30)
- Albemarle: Mix of small gains and losses; outperforming on diversified commodity exposure
On the radar
- November 10, 2026 deadline: Rare earth export controls suspension review date. Market participants should watch for Chinese policy statements in early November indicating whether controls will be re-imposed or extended.
- October EV battery production data: Chinese lithium recyclers and cathode makers reported only 4% month-on-month production growth expected for October 2026, down sharply from prior months—watch for October production reports (typically released mid-November) to signal demand inflection.
- DRC cobalt export regime: While supply has resumed, the Democratic Republic of Congo's new export quota system remains a price-management experiment; watch for Q4 shipment data in late October/November to assess whether Kinshasa's controls are effective or market-distorting.
- Indonesian nickel ore export ban enforcement: RKAB quotas are scheduled for review in Q4 2026; rumors suggest pressure from smelters to relax caps. Monitor Ministry of Energy and Mineral Resources (ESDM) communications for any mid-year adjustments.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
