
Brazil Rates and the BCB: Selic, DI Curve, Fiscal — 2026-09-26
Brazil's Copom inflation report trimmed 2026 GDP growth to 1.8% while flagging inflation near target at the key horizon, as the IPCA-15 preview surprised to the upside at 0.70%. The DI curve whipsawed around election headlines before easing on Friday, and the government's revised primary deficit forecast plus a pre-election R$15 billion debt buyout plan kept fiscal risk in focus. Attention now shifts to October's vote and November's Copom decision.
Brazil Rates and the BCB: Selic, DI Curve, Fiscal — 2026-09-26
Top developments
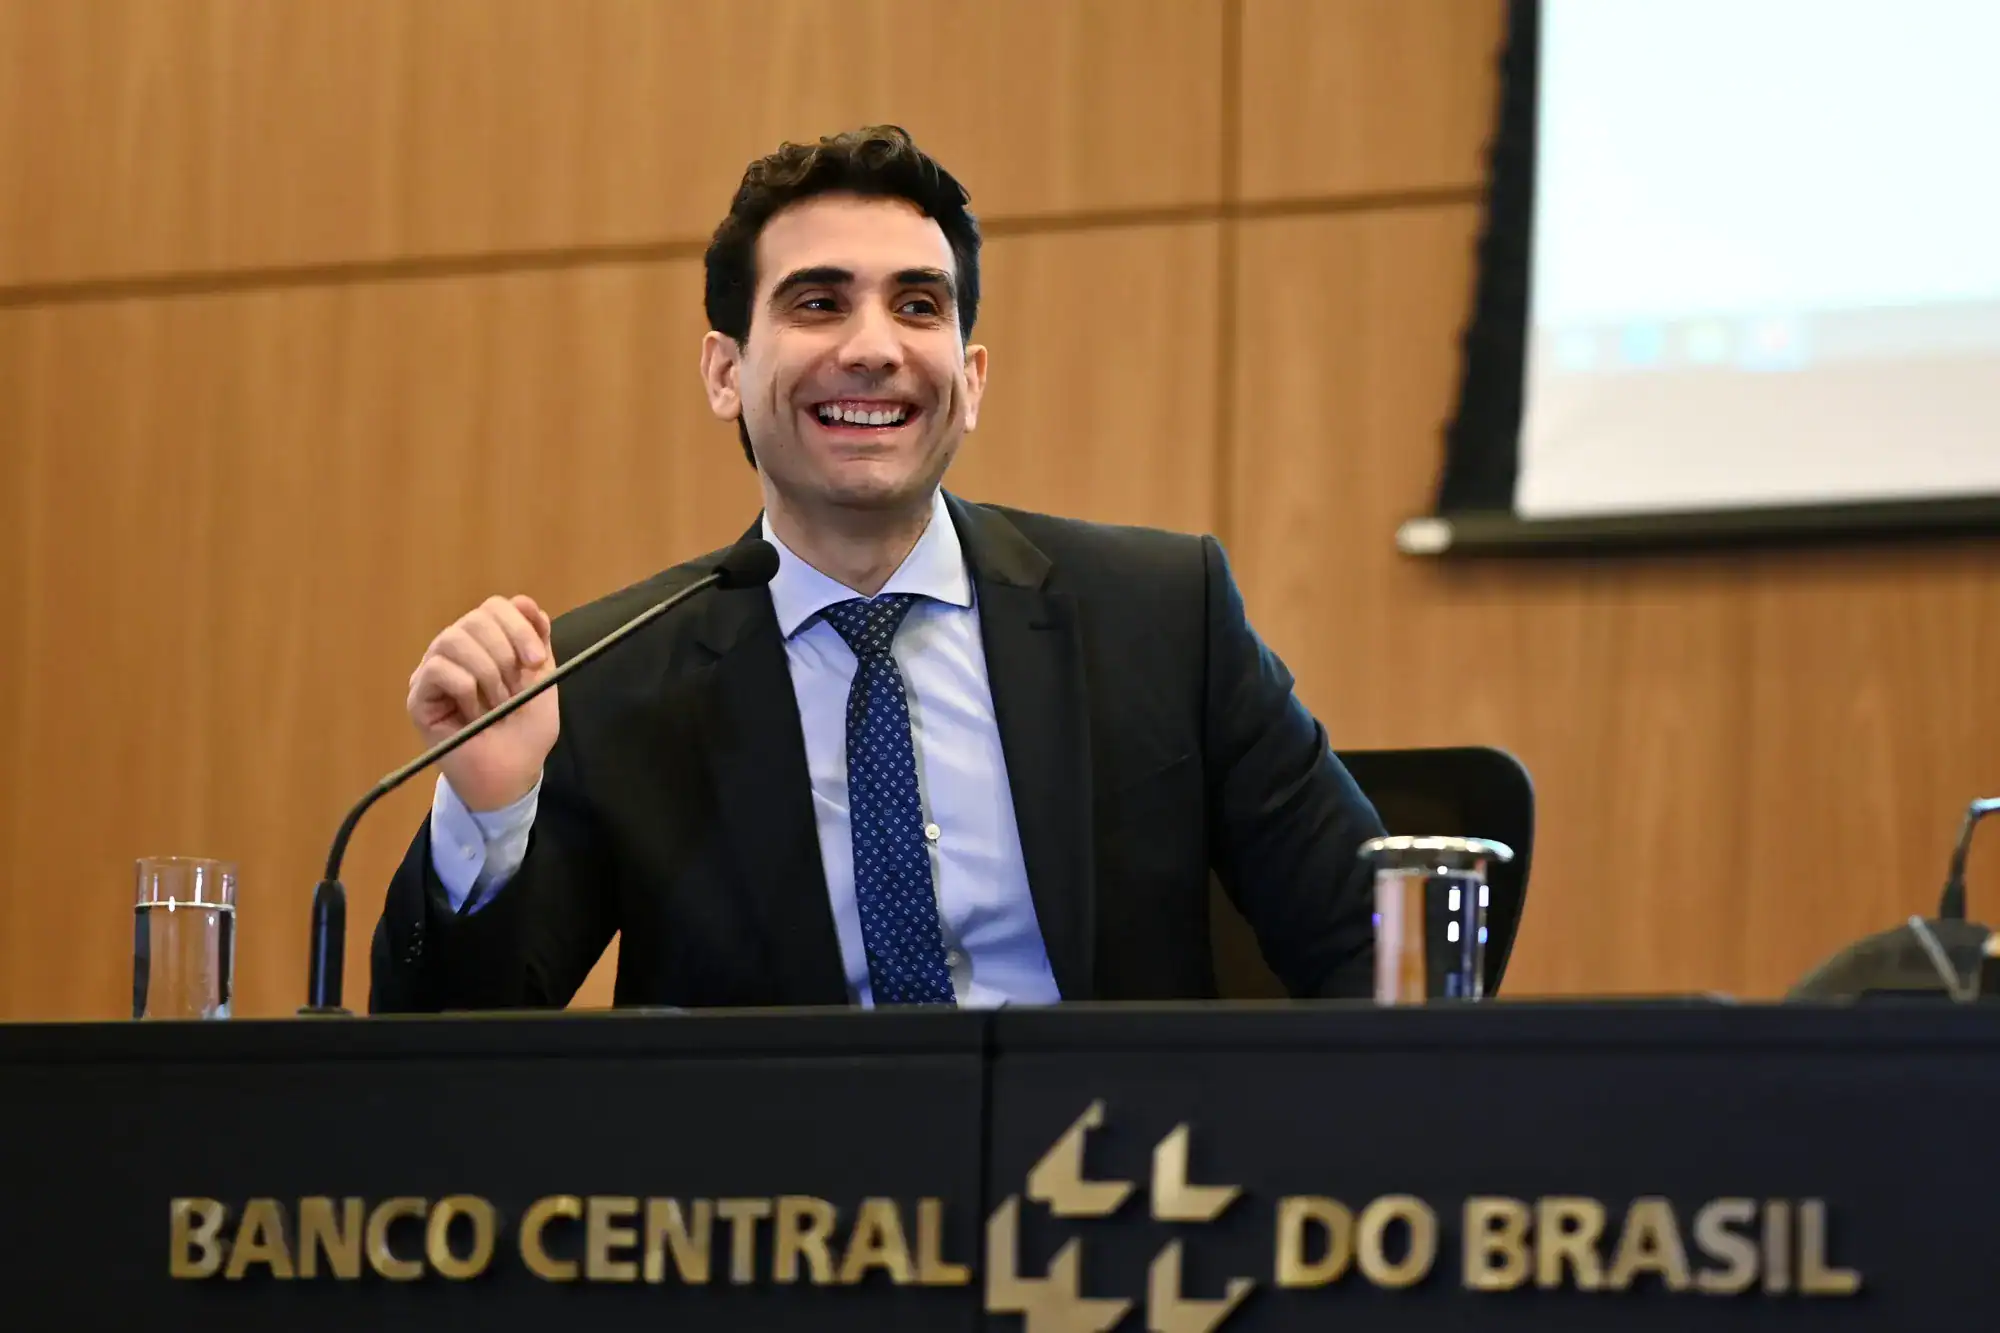
Copom inflation report: inflation near target, growth trimmed
BCB's quarterly inflation report, released September 24, projects 2026 growth at 1.8% with 2027 slowing to 1.4% as rate cuts continue, while seeing 12-month inflation near target at the relevant horizon. The softer growth picture reinforces the case for continued easing, though the committee kept the next move data-dependent.
IPCA-15 beat on electricity
September's IPCA-15 preview rose 0.70%, above the 0.55% consensus, driven by a 7.42% jump in electricity tariffs; 12-month inflation sits at 4.47%, close to the target. The upside surprise complicates the November cut narrative for Copom.
DI curve swings with election headlines, then eases
Front-to-long DI futures rose through the week on firmer Treasuries, oil and a "technical tie" in presidential polls — the January 2028 contract hit 13.585% (up 10 bps) on September 23. On September 25 the curve retreated: DI January 2027 slipped from 13.56% to 13.55% and January 2031 fell from 14.015% to 13.935% on poll optimism and lower oil. Earlier sessions also saw new reporting linking candidate Flávio Bolsonaro to ex-banker Daniel Vorcaro pressuring rates.
Government widens 2026 primary deficit forecast
The Planning Ministry revised its 2026 primary result from a R$10.8 billion surplus to a R$13.6 billion deficit, with the effective result (net of expenditures deducted from the target) at a R$80.9 billion deficit, versus a prior R$52 billion shortfall. The government kept R$16.1 billion of the 2026 budget frozen to meet the primary target.
Lula plans pre-election debt buyout
The government plans to spend R$15 billion to buy up to R$150 billion (~$28 billion) of delinquent consumer debt from banks, announced September 25 ahead of the October 4 vote; household defaults are at a record 5.8%. Spending measures with unclear financing ahead of the vote are the kind of slippage the Copom minutes warned could lift the neutral rate.
Local view
Local coverage centers on the election: Forbes Brasil notes polls showing a technical tie are already priced into Ibovespa, the real and rate futures, with markets betting on a fiscal-friendlier outcome but warning of the risk if it doesn't materialize. UOL highlights that the latest Focus bulletin projects one more 25 bp cut to 13.50% by year-end, while O Globo notes the Focus trajectory points to 12% by end-2027.
Context & numbers
- Selic: 13.75% after the Copom's fifth consecutive 25 bp cut in its 281st meeting
- DI Jan 2027: 13.55%; DI Jan 2031: 13.935% (Sept 25 close)
- IPCA-15 September: +0.70% m/m; 12-month: 4.47%
- BRL was around 5.15 per USD earlier in the week
- Government projects public debt near 89.6% of GDP by 2029, above 90% if the lower bound of the fiscal target is pursued
On the radar
- Presidential election on 4 October 2026 — too close to call, the main near-term rate and BRL driver
- Next Copom meeting in November: decision remains open after the September cut; WATCH: oil and electricity effects on near-term inflation
- Weekly Focus bulletin: next Selic path revision toward the projected 13.50% year-end rate
- Details on the R$15bn consumer debt buyout (cost, eligibility, start date) remain unannounced
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
