
China and Hong Kong Stocks: CSI 300 and Hang Seng — 2026-09-25
Hong Kong and mainland equities ended the week lower as a global bond-market selloff — with US 10-year yields near 5.2%, the highest since 2007 — pushed the Hang Seng down more than 400 points on Friday. Southbound Stock Connect participation was absent, leaving Hong Kong turnover thin, while attention now shifts to the Trump–Xi summit outcome and potential property stimulus ahead of National Day. A-share turnover topped 2 trillion yuan earlier in the week before pre-holiday risk appetite faded.
China and Hong Kong Stocks: CSI 300 and Hang Seng — 2026-09-25
Top developments
Global bond rout hits Hang Seng for 400+ points on Friday
A global "Black Thursday" in bond markets spilled into Hong Kong on Friday, with the US 10-year Treasury yield rising to about 5.2%, its highest since 2007. The Hang Seng fell over 400 points intraday to 24,356 (down 1.63%), the HSCEI slid 1.76% and the Hang Seng Tech Index dropped as much as 2.4%, with Alibaba down around 3%. The pressure at the close left the index 1.01% lower on the day.

Southbound "North Water" missing — Hong Kong turnover thin
Friday's session saw southbound Stock Connect flows absent (a holiday in mainland A-share participation), leaving Hong Kong trading subdued with the Hang Seng down 1.01% by the close. Lenovo (00992) rose more than 3% to lead blue chips. The loss of southbound buying removes one of the key stabilizing forces for the Hang Seng heading into next week.
Shanghai's 1.23% drop marked a sharp divergence from Hong Kong
In the previous session, Hong Kong held most of its ground into the close (down just 0.3%) while Shanghai dropped 1.23% — the widest split between the two markets in that session. Mainland selling was doing the heavy lifting, and analysts flagged whether Beijing's response to the selloff will determine the next move.
Thursday: Trump-Xi summit signals weighed, oil majors cushioned losses
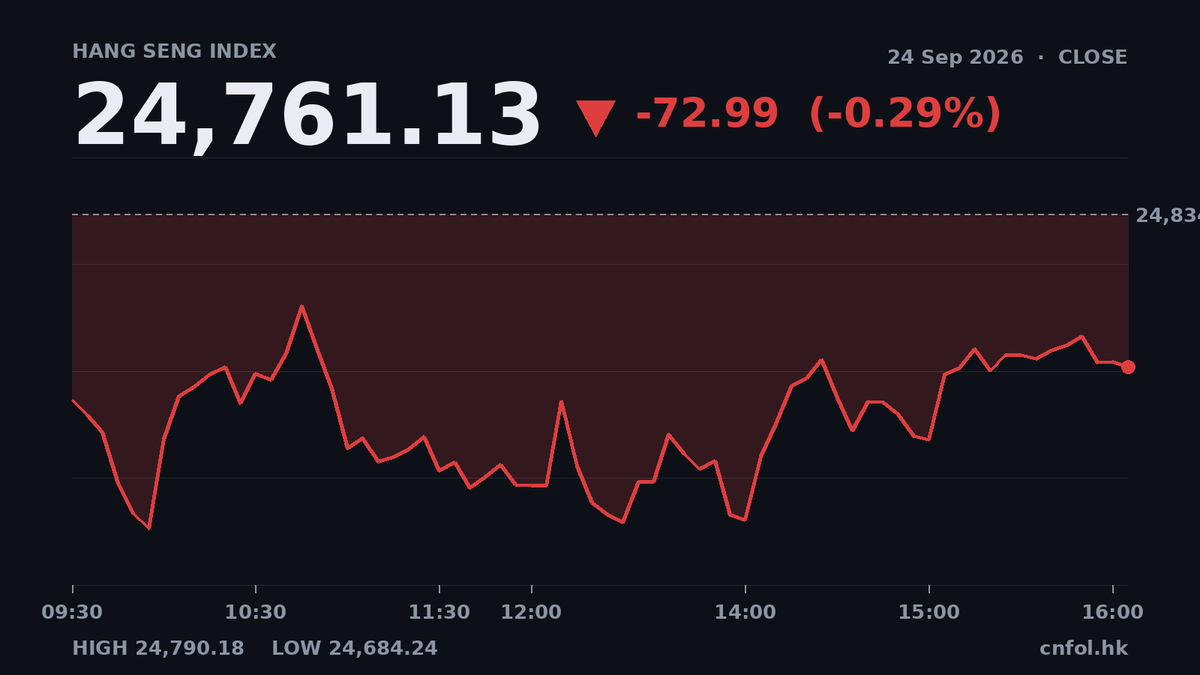
On Thursday the Hang Seng closed down 0.29% at 24,761.13 (down 72.99 points), narrowing intraday losses as investors weighed early signals from the US-China summit in Washington. PetroChina and CNOOC rallied on oil backing above $105 (Brent), cushioning technology weakness. Turnover shrank 14.4% to HK$111 billion, with advancing/declining shares at 198:365.
Property stocks rally on policy bet ahead of National Day
On September 23, Hong Kong-listed Chinese developers surged: mainland property shares opened broadly higher, with China Vanke (02202.HK) jumping more than 11% and Ronshine China (03301.HK) also spiking. This followed JPMorgan's view that Chinese developers may roll out mortgage subsidies before National Day, with the sector expected to stay resilient on policy expectations.
Local view
Chinese-language financial media framed the week around the "冲高回落" (surge-then-retrace) pattern: mainland outlets noted A-share turnover topped 2 trillion yuan for two straight sessions (Sept 18 saw 2.09 trillion yuan, up 256.4 billion from the prior day, with over 4,200 stocks rising and semiconductors and real estate leading), while domestic commentary ahead of the National Day holiday warned of shrinking volumes and risk-off positioning — "地量慢挖坑,潜伏三季报" — with three trading sessions left before the holiday.
In Hong Kong, local reports pointed out Friday's squeeze from the missing southbound flow, and HK-area media zeroed in on regulatory news: Hong Kong SFC executive director Michael Duignan said the HK$10 billion settlement paid by Evergrande's auditor came from PwC rather than Evergrande's assets, in comments made September 24 at a conference in Hong Kong, and that creditor claim priorities were unchanged.
Context & numbers
- Hang Seng weekly pattern: recovered 25,000 on Monday, then "冲高回落" into the close on Friday, sinking below 25,000 (Futu/cailianshe, Sept 25).
- Sept 24 close: HSI 24,761.13 (-0.29%), turnover HK$111 billion (-14.4%).
- Sept 23: Shanghai Composite fell to 3,938.08 (-0.36% at midday) with all three A-share indexes down by mid-session; Beijing 50 rose 2.19%.
- US 10-year Treasury yield ~5.2% on Friday, the highest since 2007; Brent back above $105.
- Two years after the "924" stimulus package, A-share total market cap has grown past 51 trillion yuan, though 47% of stocks lag the index.
On the radar
- JPMorgan's expectation of developer mortgage subsidies before National Day — watch for concrete policy announcements from Beijing in the coming window.
- Continued fallout from the global bond selloff: if US 10-year yields consolidate near 5.2%, high-flying Chinese tech shares remain most vulnerable.
- Goldman Sachs maintains a "Buy" rating on SMIC (00981) with a 12-month HK$153 target price, expecting Q3/Q4 2026 revenue to hold near Q2 levels — a read-through for the chip stock complex.
- Deepzero (深演智能, 02723.HK) goes ex-rights on October 16 with a 10-for-1 stock split; the stock closed at HK$438.4 on Sept 24 before the adjustment.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
