
China and Hong Kong Stocks: CSI 300 and Hang Seng — 2026-10-30
China’s benchmark CSI 300 index closed October with a significant decline, marking its steepest monthly drop since 2016 and entering bear-market territory, while the Hang Seng Index bucked the regional trend with a Friday rebound. Despite state-fund interventions and "national team" buying efforts, mainland equities struggled against a global AI stock selloff and weak domestic consumption data. Meanwhile, Chinese investors accelerated their exit from Hong Kong stocks, with southbound flows recording their longest consecutive streak of net outflows.
China and Hong Kong Stocks: CSI 300 and Hang Seng — 2026-10-30
Top developments
CSI 300 Enters Bear Market on Worst Monthly Drop in a Decade
On Friday, October 30, the CSI 300 index closed at 3,985.50, down 1.39%, capping a month that saw the index fall approximately 15% from its June peak. This decline confirms the index's entry into bear-market territory, defined by a 20% drop from recent highs. The Shanghai Composite also slipped 1.44% to 3,599.02, marking its first month-end close below the 3,600-point psychological threshold in recent memory. The selling pressure was broad, with 4,602 stocks falling against just 893 rising, reflecting deep-seated concerns over profitability in the tech sector and weak domestic demand.

Hang Seng Buckes Regional Trend with Friday Rebound
In contrast to mainland weakness, the Hang Seng Index rose 1.46% on Friday to close at 23,294.42, driven by gains in technology, financial, and energy sectors. The Hang Seng Tech Index added 0.29%, while the State-Owned Enterprises Index climbed 1.37%. This resilience was partly attributed to the Communist Party’s 5th Plenum emphasis on unlocking domestic consumption potential, which boosted consumer-facing stocks and positioned Hong Kong as a relative haven for regional capital. Despite the Friday rally, the Hang Seng still recorded its third consecutive monthly decline, shedding 1,318 points over October.
Mainland Investors Exit Hong Kong at Fastest Pace in Five Years
Bloomberg reported that Chinese investors are pulling back from Hong Kong stocks at the fastest pace in over five years, accelerating a trend that threatens to deepen the selloff in the territory. The Ming Pao noted that southbound funds saw a net outflow of 3.6 billion yuan on Friday, marking the longest consecutive streak of outflows and the largest monthly outflow in five years. This exodus contrasts with earlier data showing sovereign wealth funds increasing their exposure to China, highlighting a divergence between institutional foreign capital and domestic retail sentiment.
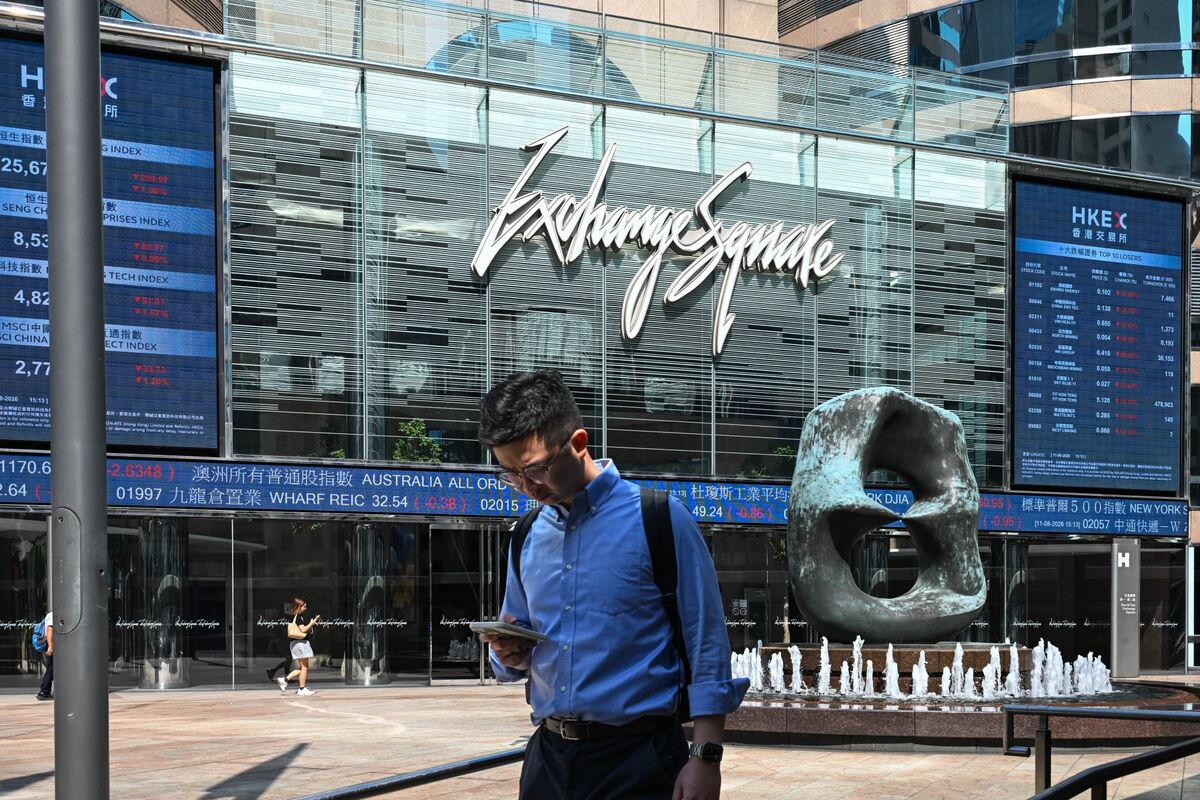
Local view
Local media outlets highlighted the divergence between mainland and Hong Kong performance, attributing the mainland's weakness to profit-taking in AI and tech sectors following disappointing earnings reports from major players like Wuliangye and Alphabet. 21st Century Business Herald reported that Shanghai market turnover remained high, with daily trading volumes exceeding 1.6 trillion yuan, indicating that while prices fell, liquidity did not dry up. In Hong Kong, Ming Pao emphasized the "resilience" of the Hang Seng, noting that consumer stocks benefited from policy signals at the 5th Plenum, which prioritized domestic demand over export-led growth.
Context & numbers
- CSI 300: Closed at 3,985.50 (-1.39%) on Oct 30; down ~15% over 12 weeks and ~20% from June peak.
- Shanghai Composite: Closed at 3,599.02 (-1.44%), breaking below 3,600.
- Hang Seng Index: Closed at 23,294.42 (+1.46%) on Oct 30; down 1,318 points for the month.
- Trading Volume: Mainland A-share daily turnover reached approx. 1.67 trillion yuan on Oct 30, an increase of ~118 billion yuan from the previous day.
- State Intervention: Reports indicate continued support from Central Huijin and other state funds, yet market sentiment remains fragile as investors question the efficacy of these measures against structural economic headwinds.
On the radar
- Rare-Earth Policy Deadline: Investors are watching the November 10 expiration of China's rare-earth export pause, which could impact tech supply chains and trigger renewed volatility in semiconductor and materials sectors.
- November Adjustment Pressure: Analysts from Stheadline warn that despite the Friday rally, the Hang Seng may face further correction pressure in November as global AI valuation adjustments continue.
- Central Bank Meetings: Market participants are awaiting further clarity on monetary policy easing following recent central bank meetings, hoping for stimulus measures to counter the property and consumption slump.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
