
China and Hong Kong Stocks: CSI 300 and Hang Seng — 2026-10-16
Chinese mainland stocks hit a 14-month low on Thursday as AI sector weakness and mixed inflation data deepened the selloff, though Hong Kong's Hang Seng rebounded sharply Friday on bargain-hunting in tech and financials. Mainland and offshore markets are diverging sharply, signaling a growing disconnect between domestic and international investor sentiment amid slowing growth concerns.
China and Hong Kong Stocks: CSI 300 and Hang Seng — 2026-10-16
Top developments
CSI 300 closes at 2026 low as AI selloff deepens; Shanghai Composite falls 1.94%
China's blue-chip CSI 300 index closed at its lowest level of 2026 on Thursday, October 15, as technology and AI-related hardware shares came under sustained selling pressure. The Shanghai Composite Index fell 1.94% while the broader market saw 7.65% of stocks rise—the second-narrowest advance of the year—with 97% of stocks opening lower. The selloff was triggered by global AI hardware concerns and mixed inflation data that heightened concerns over domestic demand weakness.
Hong Kong rebounds 1.03% as Xiaomi and Tencent lead tech recovery; Hang Seng tests 24,000-point support
The Hang Seng Index erased Thursday's 1.4% loss and rebounded sharply on Friday, October 16, closing at 24,062.72 (+1.03%), as bargain hunters returned to beaten-down technology and financial stocks. The Hang Seng Tech Index surged 3.1% from close to a two-year low, with Xiaomi and Tencent leading the recovery. However, internally the index remains fragile: three major state-owned banks hit new highs while tech stocks remained under pressure at lower levels, and southbound funds turned to net selling for the first time after seven consecutive weeks of inflows.
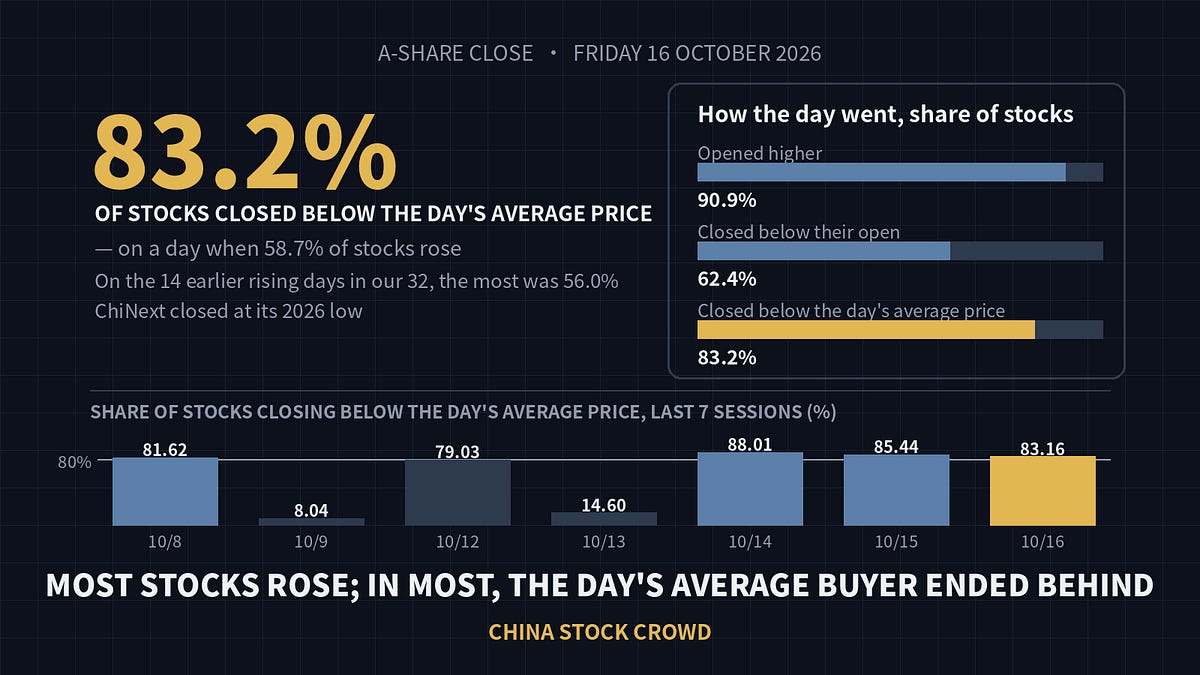
A-share market reversal: 58.7% of stocks rose Friday as margin debt falls; northbound flows weaken
On Friday, October 16, 58.7% of Chinese stocks rose after the severe Thursday decline, with 90.9% opening higher—the most in 46 sessions. However, 83.2% of stocks closed below what the day's average buyer paid, signaling profit-taking among those who caught the bottom. Thursday's margin debt fell ¥31.36 billion, indicating retail investors were reducing leverage. The Shanghai Composite recovered to close at 3,716.28 (+0.24%), successfully reclaiming the 3,700-point level.
Offshore vs. onshore split deepens: Hong Kong holds flat while Shanghai slides—money flows diverge
On October 14, Hong Kong's Hang Seng finished nearly flat while the Shanghai Composite fell 0.89%, signaling that China-exposed foreign capital is choosing Hong Kong over mainland exposure. The next day (October 15), Hong Kong finished +0.39% while Shanghai closed in the red—a pattern that suggests offshore investors are rotating into Hong Kong as a hedge while avoiding mainland risk. This divergence reflects growing concerns about domestic growth and the adequacy of stimulus measures announced so far.
Local view
Chinese financial media outlet Sina Finance reported that on October 14, the Shanghai Composite opened 0.27% lower with weak sentiment in precious metals, alcohol stocks, and short-form video concepts, while cold-chain and dye-coating themes found support.
Hong Kong's Mitrade research team observed that Thursday's sharp two-way divergence—with mainland banks hitting new highs while the Hang Seng Tech Index touched multi-month lows—revealed a "torn market" (撕裂的港股). The commentary noted that after seven weeks of net southbound buying, foreign funds switched to net selling on Thursday, suggesting a shift in offshore investor risk appetite.
Context & numbers
Index closes (as of October 16, 2026):
- Shanghai Composite: 3,716.28 (+0.24%)
- CSI 300: at 2026 low (exact close pending)
- Hang Seng: 24,062.72 (+1.03%)
- Hang Seng Tech: rebounded +3.1% from two-year lows
Breadth & sentiment:
- 7.65% of Chinese A-shares rose Thursday (second-narrowest of 2026)
- 58.7% rose Friday, but 83.2% closed below the session's average price
- 97% of stocks opened lower Thursday
- Margin debt fell ¥31.36 billion Thursday
International backdrop: The IMF warned October 15 that China's recent stimulus package "lacks ambition" and leaves the yuan undervalued in real terms given the flagging domestic economy. The Fund signaled that current measures fall short of what is needed to address underlying demand weakness. Goldman Sachs noted investors are seeking "profitable" Chinese business growth overseas, reflecting sluggish domestic consumer demand pushing companies like EV makers to accelerate international expansion.
On the radar
-
Hang Seng support test at 24,000: Technical analysts flagged the 24,000-point level as critical. Hong Kong market commentary warned that without fresh policy stimulus, the index could test 23,500 and below.
-
Tech sector divergence widening: Hang Seng Tech Index flirted with fresh multi-month lows mid-week before Friday's rebound, while mainland ChiNext index closed at 2026 lows. Watch for sector rotation signals.
-
Southbound flows reversed: After seven consecutive weeks of net inflows, southbound (Hong Kong→mainland) funds turned to net selling Thursday—a potential warning signal if sustained.
-
Q3 GDP data and stimulus adequacy: Reuters polls expect Q3 growth to pick up on stimulus, but IMF skepticism suggests the market may be waiting for more ambitious measures before a sustained rally can take hold.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
