
China Rates and Credit: PBoC, CGBs, Property Debt — 2026-10-13
China's 10-year government bond yield held steady at 1.7% amid a global surge in yields, driven by domestic liquidity support and deflationary pressures. The Ministry of Finance accelerated debt swaps with 550 billion yuan in new quota allocations, while home sales showed only a modest recovery despite recent stimulus measures.
China Rates and Credit: PBoC, CGBs, Property Debt — 2026-10-13
Top developments
10-Year CGB Yield Holds at 1.7% Amid Global Divergence
On October 9, China’s 10-year government bond yield remained at 1.7%, significantly below the equivalent U.S. Treasury yield which saw volatility due to global stagflation concerns. This divergence highlights the resilience of Chinese debt markets, supported by the People's Bank of China (PBoC) maintaining accommodative liquidity conditions and weak domestic inflation data.

MOF Allocates 550 Billion Yuan for Local Debt Resolution
The Ministry of Finance announced on October 8 that it would allocate 550 billion yuan from local government debt settlement limits to enhance general public budget capacity and support effective investment. This move is part of the ongoing "one-bundle" debt resolution plan aimed at accelerating the replacement of implicit local government debt, with 1.73 trillion yuan in replacement bonds already issued by the end of July 2026.
Home Sales Show Only Modest Recovery Post-Stimulus
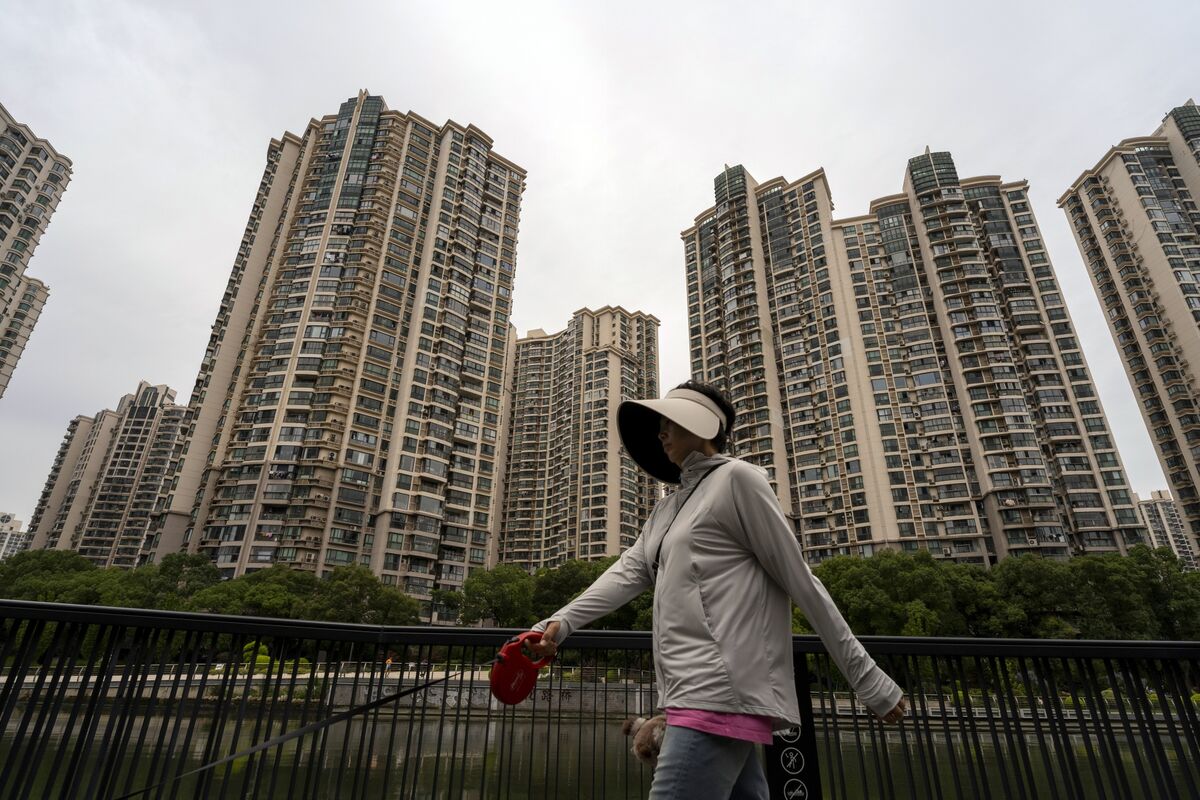
Despite the rollout of new property sector measures in late September, national home sales during the October holiday period showed only a modest recovery. Analysts note that the stimulus has had limited impact on buyer confidence, raising concerns about the effectiveness of current policies in stabilizing the sagging real estate market.
PBoC Supports Yuan at Four-Year High Against Basket
The yuan reached a four-year high against a basket of trading partner currencies as the PBoC defended its exchange-rate management and rejected claims of undervaluation. On October 13, the PBoC set the USD/CNY reference rate at 6.7298, slightly stronger than the previous fix of 6.7313, signaling continued stability in currency policy amidst global trade tensions.
Local view
Local financial media highlight the "structural strengthening" of ultra-long-end bonds and stable liquidity conditions following the National Day holiday. According to 21st Century Business Herald, the PBoC used a combination of overnight reverse repos and outright reverse repos to ensure smooth liquidity, keeping the funding environment "stable and slightly loose." The report notes that while the 10-year yield remained flat, the ultra-long end (30-year) showed slight strength due to structural demand.
Sina Finance reports that the credit bond market saw mixed performance, with issuance volumes rising but trading volumes declining week-on-week. The commentary emphasizes that while broad credit concerns have eased slightly post-holiday, the market remains cautious about long-term yield compression given the persistent deflationary backdrop.
Context & numbers
- 10-Year CGB Yield: 1.7% (as of Oct 9, 2026).
- USD/CNY Reference Rate: 6.7298 (set on Oct 13, 2026).
- Replacement Bond Issuance: 1.73 trillion yuan issued by end of July 2026.
- New Debt Quota: 550 billion yuan allocated on Oct 8, 2026.
- CPI Inflation: 0.8% YoY (August 2026).
On the radar
- LPR Announcement: The next Loan Prime Rate (LPR) decision is scheduled for October 20, 2026. Markets will watch for any adjustments in light of the recent 550 billion yuan fiscal injection.
- Property Sector Stabilization: Investors are monitoring whether the "modest" recovery in holiday sales translates into sustained transaction volumes in major tier-1 cities throughout Q4.
- Global Yield Spreads: Continued divergence between Chinese and U.S. bond yields may attract further foreign inflows into CGBs, potentially tightening liquidity in the interbank market if not offset by PBoC operations.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
