
China Rates and Credit: PBoC, CGBs, Property Debt — 2026-10-29
The People's Bank of China (PBoC) injected a record 1 trillion yuan in overnight liquidity, driving China's five-year government bond yield to a record low of 1.340%. Simultaneously, the government plans to accelerate bond sales by at least 2.2 trillion yuan in the final two months of the year to stimulate growth, while distressed real estate developers accelerate debt restructuring efforts.
China Rates and Credit: PBoC, CGBs, Property Debt — 2026-10-29
Top developments
PBoC Liquidity Injection Drives Yields to Record Lows
On October 28, the PBoC injected a record 1 trillion yuan in overnight liquidity into the banking system to maintain ample liquidity. This massive cash injection drove China’s five-year government bond yield down to a record low of 1.340%, reflecting intense demand for safe assets amidst a tech stock correction. The move underscores the central bank's commitment to keeping borrowing costs low despite global yield pressures.
Accelerated Bond Issuance to Stimulate Growth
China’s central and local governments are set to raise at least a net 2.2 trillion yuan ($330 billion) through bond sales in November and December. This represents the second-highest issuance volume on record for this period, as authorities step up fiscal support for the sluggish economy. The increased supply is expected to focus market attention on how the PBoC will manage liquidity to accommodate the heavier debt issuance.
30-Year CGB Yields Slump Below 2.05%
The 30-year government bond yield fell to 2.046% in the interbank market, slipping below the 2.05% mark to set a new year-to-date low. This decline was fueled by a flight to safety following a correction in tech stocks and the PBoC's expansive liquidity stance.
Property Developers Accelerate Debt Restructuring
October has seen a concentration of debt restructuring announcements from distressed real estate developers. Key developments include Rongsheng Development proposing "debt-for-asset" swaps for 3.8 billion yuan in domestic bonds, while Agile Group disclosed significant progress on its offshore debt restructuring. Additionally, Road King Infrastructure announced it will hold a creditor meeting on November 23 to discuss its $2.4 billion offshore debt restructuring.
Local view
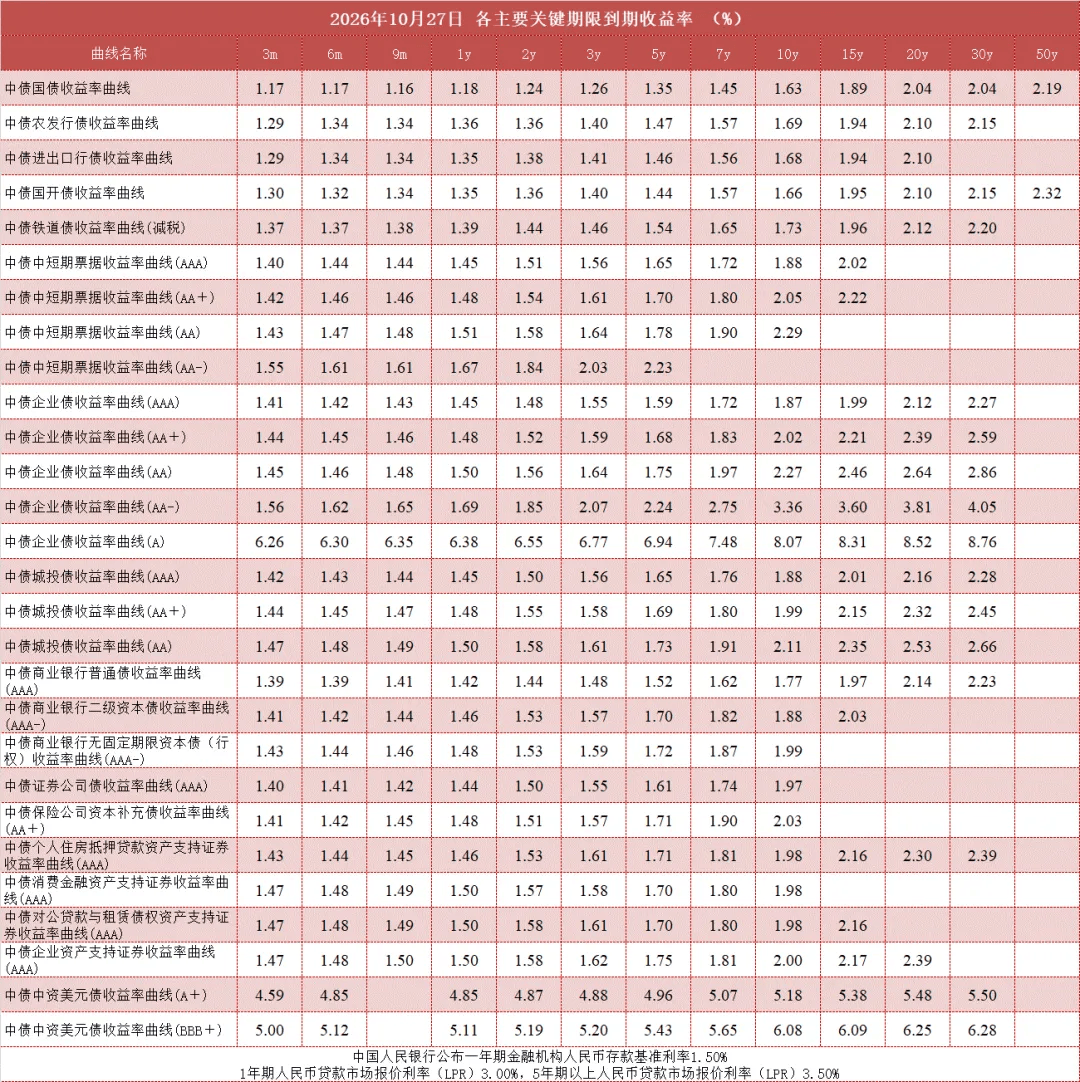
Local financial media, including 21st Century Business Herald, highlight the divergence in the bond market, where short-to-medium term yields fell due to ample liquidity, while long-end yields adjusted on rumors of regulatory restrictions on long-bond trading. Analysts from Southern Fund noted that the yield curve has flattened significantly, with the spread between 30-year and 10-year government bonds compressing to 42 basis points, reflecting a cautious outlook on domestic demand and property sector recovery.
Context & numbers
- LPR Rates: As of October 20, the 1-year Loan Prime Rate (LPR) stood at 3.0%, and the 5-year or longer LPR remained at 3.5%, both unchanged from the previous month.
- Yuan Fixing: The PBoC set the USD/CNY central reference rate at 6.7147 on October 29, slightly stronger than the previous day's fix of 6.7165.
- Q3 Growth: China's third-quarter economic growth accelerated to 4.5%, driven by a surge in exports of technological goods that offset sluggish consumer demand.
On the radar
- November 23: Road King Infrastructure creditor meeting to discuss $2.4 billion offshore debt restructuring.
- Q4 Issuance: Monitor the pace of the 2.2 trillion yuan bond issuance in November and December and the PBoC's corresponding liquidity operations.
- Property Sector: Watch for further "debt-for-asset" swaps and restructuring updates from mid-tier developers facing maturity walls.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
