
Copper and Base Metals: LME Daily — 2026-09-17
Copper prices stabilized near three-week lows as LME inventory tightness eased and Chinese demand showed mixed signals, with August imports hitting a six-year low. Meanwhile, Chilean authorities warned of a "copper recession" due to aging mines, while Codelco delayed its recovery plan until late 2026. Aluminum prices consolidated at highs in China despite a US Fed rate hike, supported by accelerating ingot destocking.
Copper and Base Metals: LME Daily — 2026-09-17
Top developments
Copper stabilizes as LME tightness eases and China demand wobbles
On September 15-16, three-month copper on the London Metal Exchange (LME) gained 1.1% to $14,231 a metric ton, bouncing from recent lows as lower prices encouraged physical buying in China. However, the rebound was tempered by data showing China’s copper imports fell to 382,000 tonnes in August, its weakest August in six years. This demand softness contrasts with earlier record highs, suggesting the market is recalibrating after a speculative surge driven by tariff fears.

Chilean "Copper Recession" declared as mine production struggles
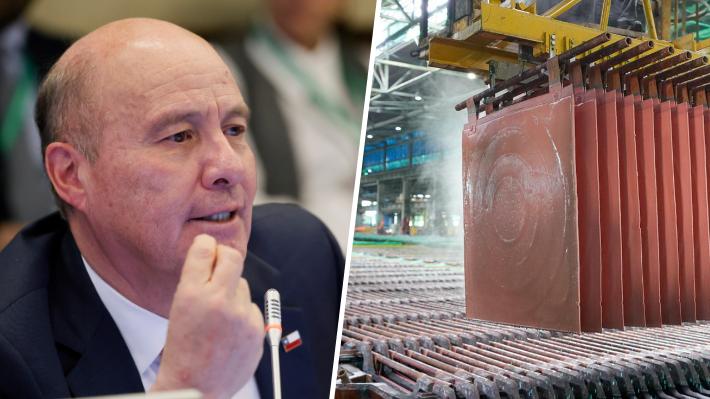
Chile’s Finance Minister Jorge Quiroz labeled 2026 a "year of great recession in copper," attributing nearly one percentage point of lost GDP growth to declining mining activity. The decline is driven by aging deposits and operational interruptions at major mines like Codelco and Escondida. In response to lower output and higher costs, state-owned Codelco has postponed its recovery plan until late 2026, revising investments and labor structures. This supply-side stress supports long-term price floors but creates short-term volatility for LME nickel and zinc, which are often co-produced or traded in similar regional hubs.
Smelter margins collapse as treatment charges hit negative territory
Spot treatment charges (TCs) for copper concentrate have fallen to negative levels, meaning smelters are paying miners to take their ore, a stark reversal from historical norms. This dynamic highlights a severe global shortage of concentrate relative to smelting capacity, exacerbating the "mining-smelting mismatch" noted by industry groups. For LME base metals traders, this signals that refined metal supply may remain constrained even if mine disruptions are resolved, keeping a structural bid under copper prices while potentially pressuring other base metals if smelters shift capacity.
Aluminum consolidates at highs in China despite Fed rate hike
SHFE aluminum edged up 0.51% on September 16, consolidating at high levels as domestic ingot destocking accelerated. The Shanghai Metals Market (SMM) noted that despite the US Federal Reserve’s recent quarter-point rate hike, aluminum prices remained resilient due to strong downstream consumption in China. SHFE zinc also rose 2.37% during midday trading, indicating broader strength in base metals amid easing macro fears.
Local view
In Chile, El Mercurio reported on Finance Minister Quiroz’s stark warning about the mining sector's drag on the national economy, emphasizing that the "recession" is structural rather than cyclical. Conversely, Guía Minera de Chile published an op-ed by Manuel Viera Flores, President of the Chilean Mining Chamber, who disputed the term "recession," arguing instead that the country faces a "recession of projects" due to permitting delays and lack of new investments. This local debate underscores the tension between current production declines and future supply potential, a key factor for LME investors assessing long-term supply risks.
Context & numbers
- LME Copper: Traded around $14,231-$14,233 per metric ton in mid-September, down from record highs near $14,779-$14,854 earlier in the month.
- China Imports: August copper imports stood at 382,000 tonnes, the lowest for that month in six years.
- Smelter Economics: Spot treatment charges have dropped to negative values, indicating extreme tightness in concentrate supply.
- Tariff Premium: The COMEX-LME spread, which previously reached $400–$600 per tonne, has narrowed as the US tariff decision stalls, reducing the incentive for arbitrage shipments to the US.
On the radar
- US Tariff Decision: The White House missed its June 30 deadline for a refined copper tariff decision; any announcement could re-inflate the COMEX premium and disrupt global flows.
- ICSG Forecasts: The International Copper Study Group maintains a forecast for a 150,000-metric-ton deficit in 2026, the first structural shortage since 2009, which will be closely watched in upcoming monthly bulletins.
- LME Contract Launch: A new LME contract settling against the SHFE hot-rolled coil (HRC) steel price begins trading on October 27, 2026, potentially increasing cross-market volatility in industrial metals.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
