
Corporate and Private Credit: Spreads, CLOs, Defaults — 2026-10-22
Credit spreads have widened sharply as AI-driven market volatility and rising French sovereign yields (OAT/Bund spread at 157.5 bps) pressure corporate bonds globally. Private credit faces a "legacy risk" test with redemption pressures in non-listed BDCs remaining above industry thresholds, while leveraged loan defaults are projected to remain elevated near 7.3%.
Corporate and Private Credit: Spreads, CLOs, Defaults — 2026-10-22
Top developments
High-Yield Spreads Widen to 329 Basis Points
U.S. high-yield bond spreads have widened 63 basis points since year-end to reach 329 basis points. This widening has raised significant concerns among institutional investors regarding downside potential and loss risks. The divergence between high-yield and investment-grade spreads has hit its widest level since May 2025, signaling a pronounced flight to quality as investors prefer higher-yielding bonds over riskier investment-grade assets.
Private Credit Redemptions Remain Elevated
While redemption pressure in non-listed Business Development Companies (BDCs) has eased from its peak, it remains materially above the industry standard 5% quarterly redemption threshold. Consequently, capital continues to leave the asset class, forcing managers to address liquidity constraints. PIMCO analysts note that after years of borrower-friendly terms, the direct lending market is shifting, with "legacy risks" emerging from previous underwriting standards.
European Credit Spreads Widen Amid French Sovereign Stress
In Europe, credit spreads have widened to their highest levels of the year, driven by soaring interest rates and AI-related market anxieties. The primary market for corporate bonds has slowed significantly. French corporate bonds are underperforming as the spread between French and German sovereign debt (OAT/Bund) reached 157.5 basis points on October 21, 2026, the highest in nearly fifteen years.
AI Infrastructure Debt Under Scrutiny
The reliance of AI infrastructure companies like CoreWeave on private credit and bond markets is facing increased scrutiny. German media reports highlight that bonds from AI giants like CoreWeave and Oracle are under pressure due to high debt levels, posing risks to pension funds holding these assets. French analysts note that CoreWeave's debt stress tests are challenging the broader narrative of private credit's role in funding AI infrastructure.
Local view
Germany (WirtschaftsWoche): German financial media are focusing on the intersection of AI hype and credit risk. WirtschaftsWoche reports that bonds from AI companies like CoreWeave are under pressure, raising concerns for pension funds exposed to high-yield tech debt. The article draws parallels to historical infrastructure bubbles, questioning the sustainability of debt-funded AI expansion.
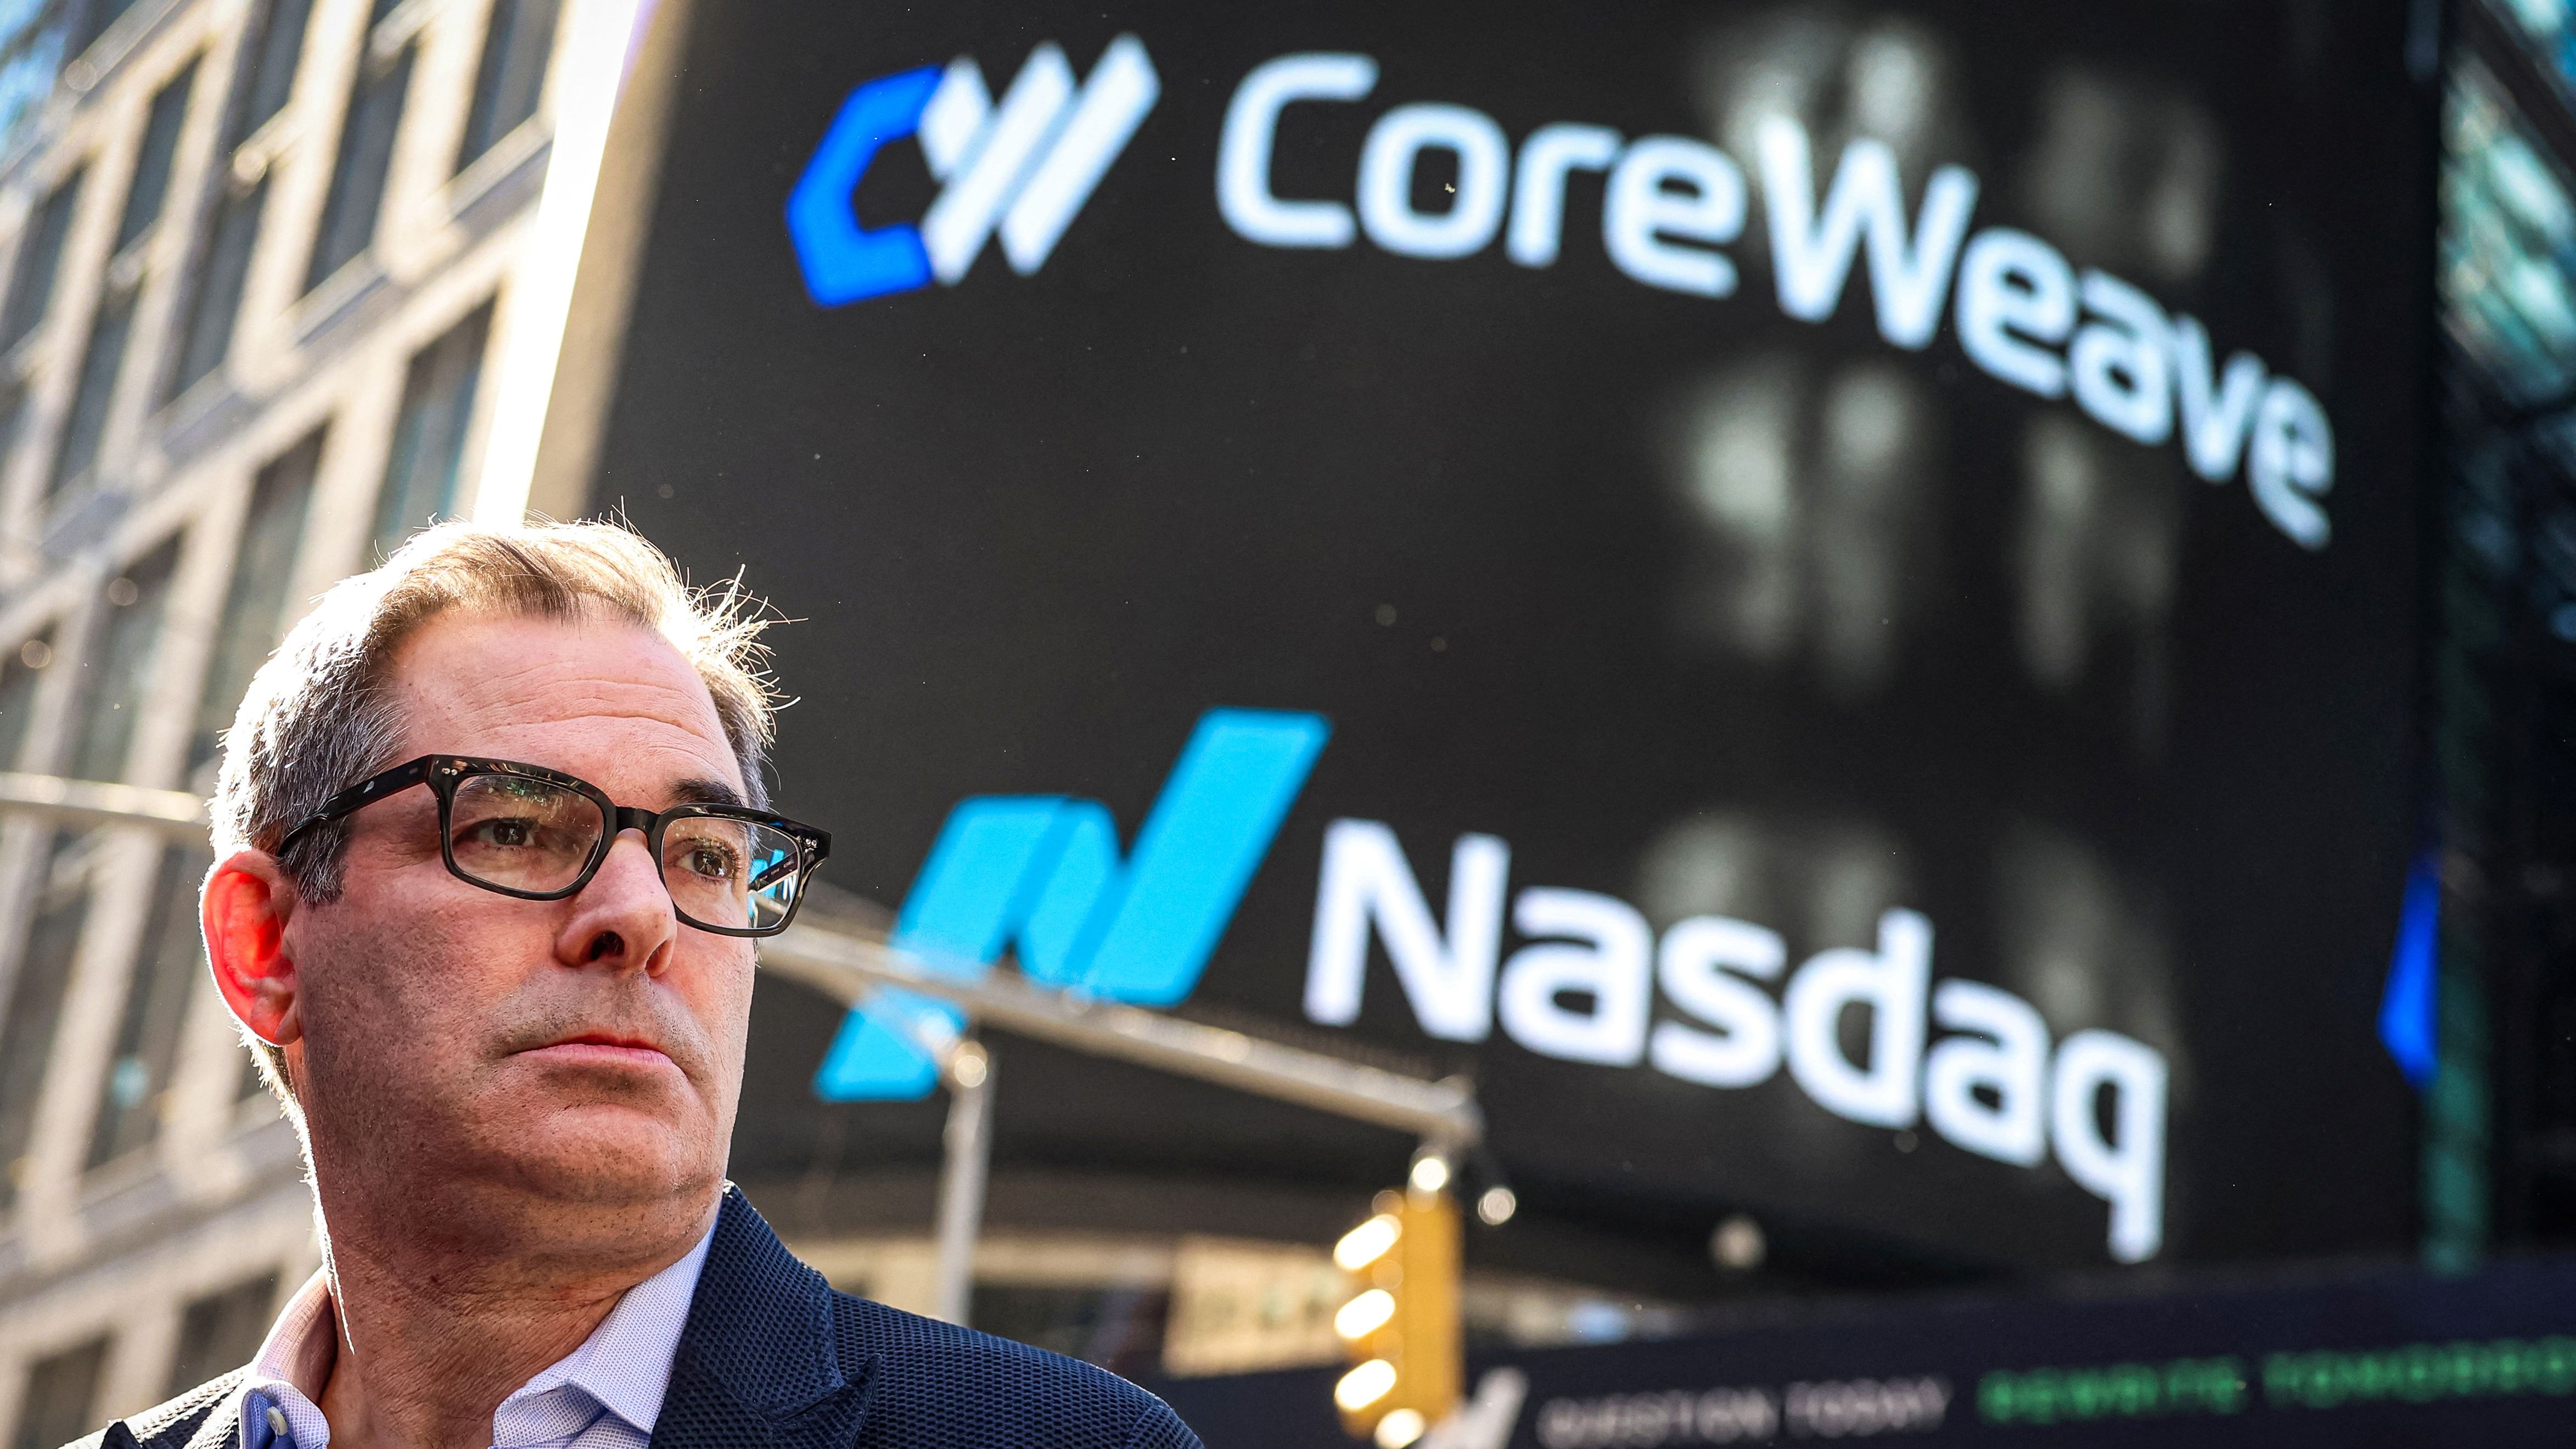
France (L'Agefi & Boursorama): French market commentators describe a "credit market derailment" where spreads have detached from previous resilience. L'Agefi reports that the "France risk" has propagated to corporate bonds, with French issuers underperforming peers due to sovereign yield spikes. Boursorama highlights that private credit's exposure to AI financing is being stress-tested, with CoreWeave's situation serving as a bellwether for the sector's liquidity and valuation assumptions.

Context & numbers
- US High-Yield Spreads: 329 bps (widened 63 bps YTD).
- France-Germany Spread (OAT/Bund): 157.5 bps (as of Oct 21, 2026).
- Leveraged Loan Default Rate: Projected to touch 7.3% in Q2 2026, following a rise to 7.9% in Q1.
- Speculative-Grade Defaults: Moody’s data suggests a potential decline toward ~2.5% over the next year, though regional analyses see global rates steady near 3.7%.
- Treasury Yields: Economists expect 10-year Treasury yields to stay above 5% well into 2027.
On the radar
- BDC Redemption Trends: Monitor quarterly reports from non-traded BDCs to see if redemptions drop below the 5% threshold, which would signal stabilization in private credit liquidity.
- AI Bond Volatility: Watch for further spread widening in tech infrastructure bonds (CoreWeave, Oracle) as pension funds reassess exposure to high-growth, high-debt issuers.
- French Sovereign Impact: Continued volatility in French OATs could force a repricing of European corporate credit, particularly for French issuers.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
