
Corporate and Private Credit: Spreads, CLOs, Defaults — 2026-09-25
Private credit redemption pressure hit a new milestone as Apollo capped redemptions from a direct lending fund for a third straight quarter after 14.7% of investors sought to exit. Meanwhile, secondary-market buyers are privately offering liquidity to fund investors at steep discounts, and the 10-year Treasury yield reached its highest level since 2007, re-pricing the entire credit curve.
Corporate and Private Credit: Spreads, CLOs, Defaults — 2026-09-25
Top developments
Apollo caps private credit fund redemptions for third consecutive quarter
Apollo Global Management is again limiting redemptions from a private credit fund after 14.7% of investors expressed an intention to exit, the third straight quarter in which it has capped withdrawals, Bloomberg reported on September 22. The move lands in a $1.8 trillion direct lending market that has seen a broad rush for exits, fueled by high-profile defaults, valuation concerns and exposure to software borrowers vulnerable to AI disruption.
Retail investors offered liquidity at steep discounts
Boursorama, carrying Reuters translated coverage on September 25, reported that buyers in the secondary market are offering liquidity to investors in some of the largest unlisted private credit funds at significant discounts. This confirms that exit pressure is no longer confined to gating announcements — holders who need cash now are accepting deep marks. It is a key signal for evergreen fund NAVs, as discount transactions can force managers to re-anchor valuations.
Treasury yields surge reshapes the risk-reward calculus
On September 25, CNBC reported the 10-year Treasury yield hit its highest level since 2007, with some investors eyeing bonds as a buy. The surge — driven by inflation fears and global bond sell-off this week — compresses the relative appeal of tight credit spreads and raises refinancing costs for leveraged issuers. French outlet Boursorama noted the same dynamic: rising oil prices and sovereign yields pressured equities and credit on September 23, and a "tumultuous week" for sovereign debt ended with Europe slightly higher on September 25.
Private credit stress in the spotlight in Spanish-language and fund commentary
Spanish-language analysis from XTB (published September 23) examined how rising junk bond yields and defaults, redemptions and AI exposure are beginning to create equity spillover risk from private credit tension. The commentary frames default and withdrawal dynamics in the direct-lending market as a macro story now entering equity risk discussions.

Local view
- France: Coverage in French-language media is dominated by the sovereign bond rout and its knock-on effects. Boursorama (September 25) flagged five indicators markets are watching in France amid doubts over public finances and political fragmentation ahead of next year's presidential election. Les Échos' Investir (September 22) argued investors are increasingly skeptical of states' ability to cut debt, complicating sovereign bond investing. French analyst firm RYDGE's September note highlighted widening OAT-Bund spreads and dispersion among corporate bonds as the "French risk premium" bill arrives.
- Spain/LatAm: Spanish-language XTB analysis of junk bond yields and private credit tension is feeding regional investor discussion.
Context & numbers
- US High-Yield OAS stood at 2.73% on September 23, per the FRED series BAMLH0A0HYM2 — spreads remain historically tight even as yields rise.
- The 10-year Treasury yield reached its highest level since 2007 on September 25.
- Apollo's fund capped redemptions after a 14.7% exit queue.
- For framing the private credit stress: the global private credit market exceeds $2 trillion, and Goldman Sachs points to software-sector exposure and valuation concerns as the redemption triggers.
- Federal Reserve H.15 daily rates were releases September 24 amid the Treasury move.
On the radar
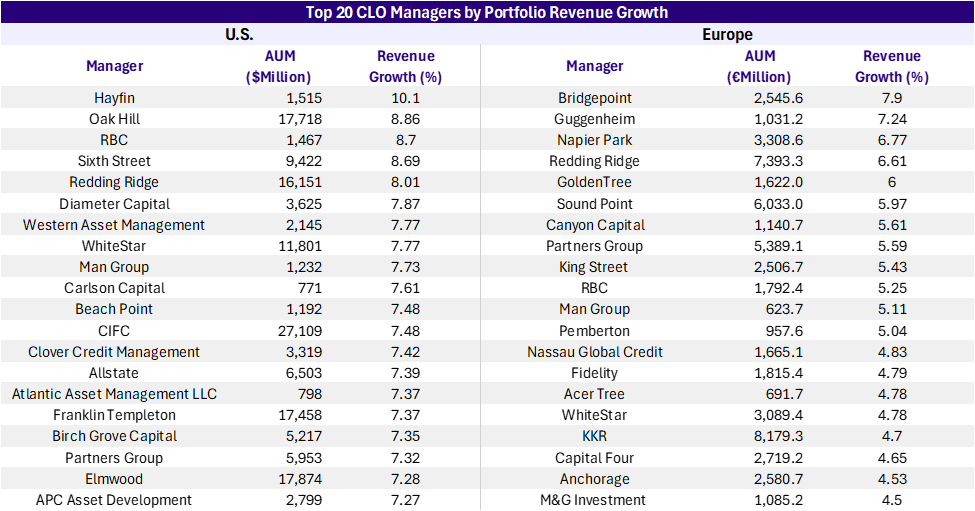
- CLO refinancing wave: Non-call expiries on 2024 CLOs could unlock a wave of resets and refinancings later in 2026, per legal-market coverage — watch whether the loan supply technicals finally ease.
- Private credit secondary discount levels: Track whether Reuters-reported "significant discounts" on secondary stakes become a regular pricing, and what that means for evergreen marks.
- French weakness: The French OAT-Bund spread and additional French indicators are worth watching ahead of the presidential election, per Boursorama/RYDGE.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
