
Europe Stocks: STOXX 600, DAX, CAC 40 and FTSE MIB — 2026-10-26
European equities closed the week of October 19–23, 2026, with significant losses driven by surging oil prices, French fiscal instability, and caution regarding AI sector valuations. The STOXX 600 fell 1.39% to 635.77, while the CAC 40 dropped 2.19% amid fears over France’s sovereign debt rating and a slump in luxury stocks like Kering.
Europe Stocks: STOXX 600, DAX, CAC 40 and FTSE MIB — 2026-10-26
Top developments
STOXX 600 closes lower on oil and AI fears
The pan-European STOXX 600 index ended the week down 1.39% at 635.77, pressured by a rise in Brent crude to $116 per barrel and persistent uncertainty about the sustainability of the AI boom. Bank stocks acted as a partial cushion, but the broader market sentiment remained negative as global yields surged and geopolitical tensions in the Middle East escalated.
DAX slips as French fiscal stress weighs on sentiment
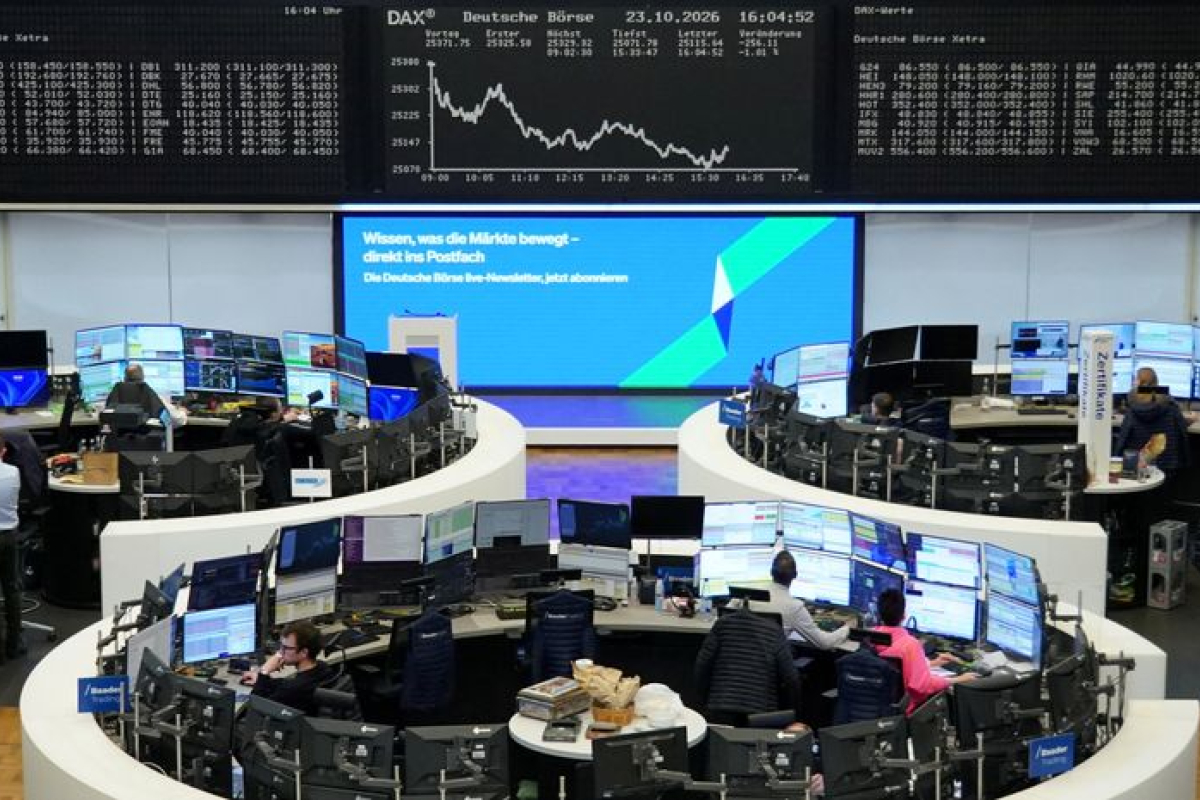
The German DAX fell 1.72% to 25,181.65, reflecting the contagion effect from French fiscal uncertainty and disappointing economic signals. Investors remained cautious ahead of central bank decisions, with the index struggling to find momentum despite some resilience in specific industrial sectors.

CAC 40 hits weekly low on Kering slump and debt fears
France’s CAC 40 suffered the largest drop among major indices, falling 2.19% to 7,782.82. The decline was exacerbated by a sharp drop in luxury giant Kering and growing anxiety over France’s sovereign debt, which saw 10-year OAT yields breach 5% for the first time since 2002.
FTSE MIB underperforms amid tech and energy volatility
Italy’s FTSE MIB faced significant pressure, closing the week with notable losses as tech stocks and energy-sensitive names struggled. On Thursday, October 22, the index fell 2.5% to 48,384 points, its lowest level since May, driven by a global tech sell-off and rising oil costs.

Local view
German media: Stabilization attempts amid high oil prices
German outlet tagesschau reported that investors were attempting to stabilize the DAX, but the mood remained fragile due to persistently high oil prices and lingering concerns about AI valuations. The focus has shifted to upcoming corporate earnings and potential support from central banks, with the Fed and ECB decisions seen as critical for the next phase of market direction.
French media: Moody’s verdict and luxury sector weakness
French financial outlets Boursorama and Investing.fr highlighted that the Paris stock exchange was constrained by the anticipation of Moody’s rating review on French debt. The luxury sector, particularly Kering, was a major drag on the CAC 40, while banks faced pressure from the widening spread between French and German government bonds.

Italian media: Spread widens and tech stocks tumble
Il Sole 24 ORE described the market movement as a "perfect storm" of tech, oil, and bond volatility, noting that the BTP-Bund spread widened to 125 points while French OAT-Bund spreads approached 173. The newspaper emphasized that disappointing results from major tech firms, particularly Tesla, weighed heavily on Milan’s tech-exposed constituents.

Context & numbers
Index Closes (Week ending Oct 23, 2026):
- STOXX 600: 635.77 (-1.39%)
- DAX: 25,181.65 (-1.72%)
- CAC 40: 7,782.82 (-2.19%)
- FTSE MIB: ~49,086 (Oct 19 close) / ~48,384 (Oct 22 low)
Key Metrics:
- Brent Crude: Rose to $116 per barrel on Friday, up 2.5%
- French 10-Year OAT Yield: Crossed 5% for the first time since 2002
- BTP-Bund Spread: Widened to 127 points on Oct 22 before stabilizing around 112-115 points
- ECB Rates: Deposit facility at 2.50%, main refinancing at 2.65%, marginal lending at 2.90% (effective from Sept 16, 2026)
On the radar
- ECB and Fed Decisions: Markets are bracing for the next ECB monetary policy decision, with current rates held at 2.50% (deposit facility) since September. Investors are watching for guidance on future hikes or cuts in response to sticky inflation and slowing growth.
- Moody’s France Rating: The outcome of Moody’s review on France’s sovereign credit rating is a key catalyst for the CAC 40 and eurozone bond markets. A downgrade could further widen OAT-Bund spreads and pressure French banks.
- Strategist Split: A Bloomberg survey indicates the largest split in STOXX 600 forecasts since 2017, highlighting deep uncertainty among analysts about the impact of inflation and AI valuations on European equities.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
