
Global Real Estate and REITs: Values, Yields, Distress — 2026-10-30
Commercial real estate delinquency rates have surged to their highest levels since 2020, with office assets facing severe distress and a "massive" wall of debt maturities creating both risk and opportunity. In Europe, Vonovia has lowered its 2028 growth targets due to high interest rates, while China’s developer debt restructuring accelerates with new creditor meetings scheduled for November.
Global Real Estate and REITs: Values, Yields, Distress — 2026-10-30
Top developments
US CMBS delinquency hits highest level since 2020
The Trepp CMBS Delinquency Rate rose 17 basis points to 8.02% in September 2026, marking its highest level since November 2020. Office assets remain the most distressed segment with a 12.33% delinquency rate, while special servicing volumes climbed to $69.53 billion, the largest volume since the post-Global Financial Crisis era. This data underscores the ongoing pressure on lenders as property values adjust to higher interest rates.
Vonovia lowers 2028 targets amid rate pressure
Germany’s largest residential landlord, Vonovia, has lowered its EBITDA and pre-tax profit targets for 2028 due to higher financing costs and slower rent growth. The company cited a sluggish transaction market and increased refinancing costs as key factors, leading to a cautious outlook for the remainder of 2026. This move signals broader challenges for European listed real estate companies navigating a high-rate environment.

China developer debt restructuring accelerates
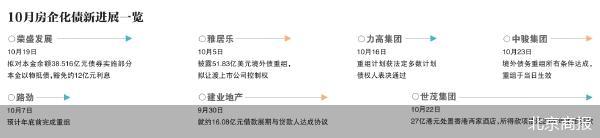
In China, debt restructuring efforts for distressed developers are entering a concentrated window in October. Road King Infrastructure announced a creditor meeting for November 23 to discuss offshore debt restructuring, while Rongsheng Development proposed a "debt-for-assets" swap for 3.8 billion yuan of domestic bonds. These moves indicate a shift from negotiation to execution in China’s property sector risk resolution.
US office distress shifts from vacancies to investor losses
Office distress is evolving from high vacancy rates to direct investor losses as CMBS maturities expose sharply reduced building values. This shift forces lenders and owners to recognize write-downs, creating a "brutal refinancing reality" for landlords and REIT investors alike. The recognition of these losses is reshaping capital flows in the US commercial property market.
Local view
South Korea: PF loan delinquency hits 10-year high
In South Korea, the financial sector's real estate project financing (PF) loan delinquency rate has risen to 4.65%, the highest level since 2016. While total PF loan balances have decreased to 115.5 trillion won, the exposure to "under observation" and "doubtful" projects has expanded to 16.4 trillion won, indicating persistent underlying risks despite aggregate reduction. Local media warn that the cleanup of distressed PF projects is slowing, raising concerns about the stability of savings banks and securities firms heavily exposed to this sector.

Context & numbers
US CRE Debt Maturities Present Opportunity
A massive wall of commercial real estate debt is coming due now and over the next two years. While this presents significant refinancing challenges, some analysts view it as a "massive" opportunity for investors with available capital to acquire distressed assets at favorable valuations. The divergence between distressed sellers and opportunistic buyers is defining current market dynamics.

Retail REITs Show Resilience
Amid broader sector stress, retail REITs are showing signs of strength. Brixmor Property Group recently raised its dividend by 7.3%, citing record occupancy numbers and double-digit rent spreads in grocery-anchored shopping centers. This highlights the sector-specific divergence within global real estate, where retail assets are outperforming office and industrial segments in some regions.
On the radar
Upcoming Creditor Meetings in China
The November 23 creditor meeting for Road King Infrastructure will be a key event to watch for signals on the pace and terms of offshore debt restructuring in China’s property sector.
Korean PF Loan Cleanup Speed
Monitor the speed of distressed PF project resolution in South Korea, as slower-than-expected cleanup could lead to further credit stress in the local financial sector.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
