
Global Real Estate and REITs: Values, Yields, Distress — 2026-10-19
Commercial real estate markets are entering a critical phase as rising Treasury yields freeze deal activity and expose vulnerabilities in debt refinancing. In Europe, Vonovia faces a sharp stock decline driven by rising financing costs and political threats of expropriation in Berlin, while South Korea’s savings banks are under scrutiny for masking non-performing PF loan exposure through fund transfers. Meanwhile, CMBS delinquency rates in the US have hit their highest levels since 2020, signaling deepening distress in the office sector.
Global Real Estate and REITs: Values, Yields, Distress — 2026-10-19
Top developments
Treasury Yield Spike Freezes US Commercial Lending
The surge in the 10-year Treasury yield to 5.3% this week has effectively stalled commercial real estate dealmaking, with lenders warning that the recovery is over. Commercial lending executives report that the volatility makes it nearly impossible for assets to trade, as buyers and sellers cannot agree on valuations in the current rate environment. This "frozen" market status is preventing necessary capital recycling and exacerbating the refinancing wall facing $1 trillion in commercial mortgages
Vonovia Plunges on Berlin Expropriation Plans and Jefferies Downgrade
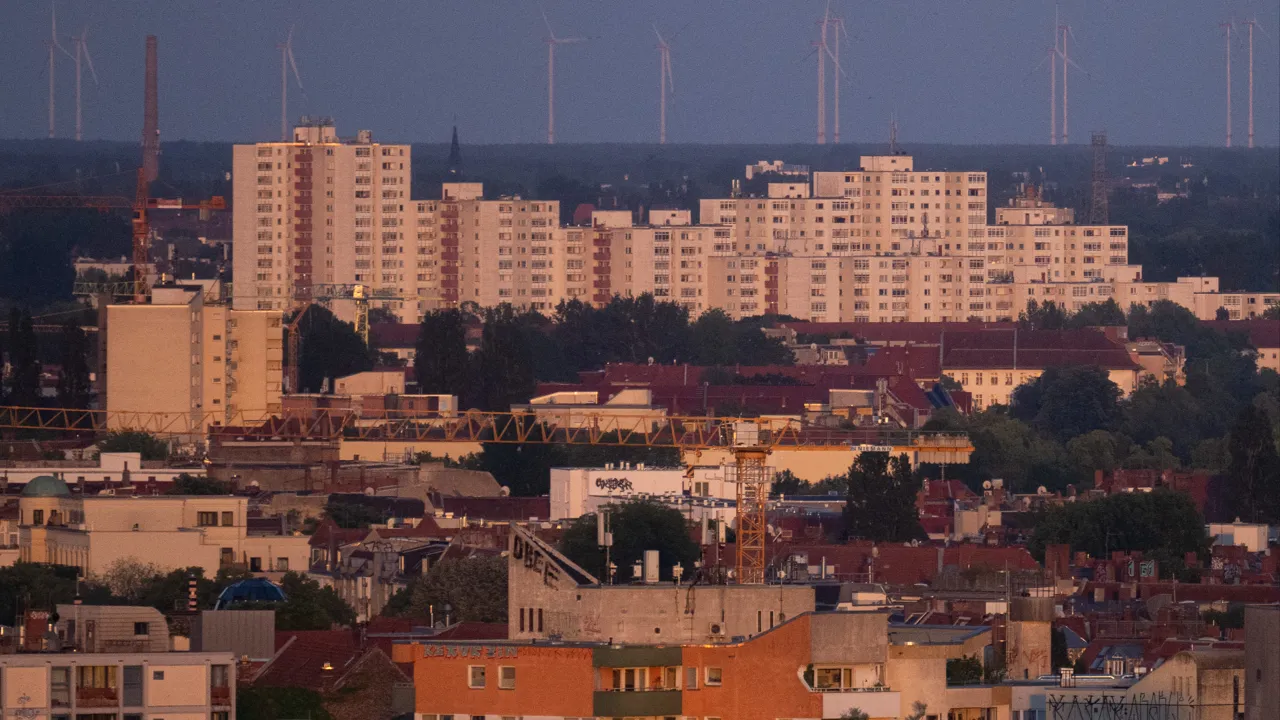
Vonovia’s shares dropped significantly this week after Berlin’s coalition parties (Linke, Greens, and SPD) agreed to push forward with plans to expropriate large housing companies. This political risk coincided with Jefferies cutting its price target for Vonovia from €28.50 to €23.00, citing higher financing costs and potential asset write-downs. The stock is down roughly 32% year-to-date, reflecting the dual pressure of rising interest rates and legislative uncertainty in Germany’s largest landlord’s key market
Korean Savings Banks Under Fire for "Illusion" of PF Health
South Korean media and regulators are questioning the integrity of savings banks’ balance sheets, warning that they are creating an "illusion" of improved asset quality. Banks are selling non-performing real estate Project Financing (PF) loans to normalization funds to lower reported delinquency rates, but the underlying assets remain distressed, and liquidation is delayed. This accounting maneuver masks the true extent of risk, as the actual workout of these properties is stalling, threatening future losses and potential disruptions to housing supply

CMBS Delinquency Hits Highest Level Since 2020
The Trepp CMBS Delinquency Rate rose 17 basis points to 8.02% in September 2026, marking its highest level since November 2020. The increase is driven primarily by the office sector, where building values have sharply reduced, forcing lenders and owners to recognize losses as loans mature. This trend underscores that office distress is shifting from mere vacancy issues to tangible investor losses and balance sheet impairments
Singapore REITs Benefit from AI-Driven Office Demand
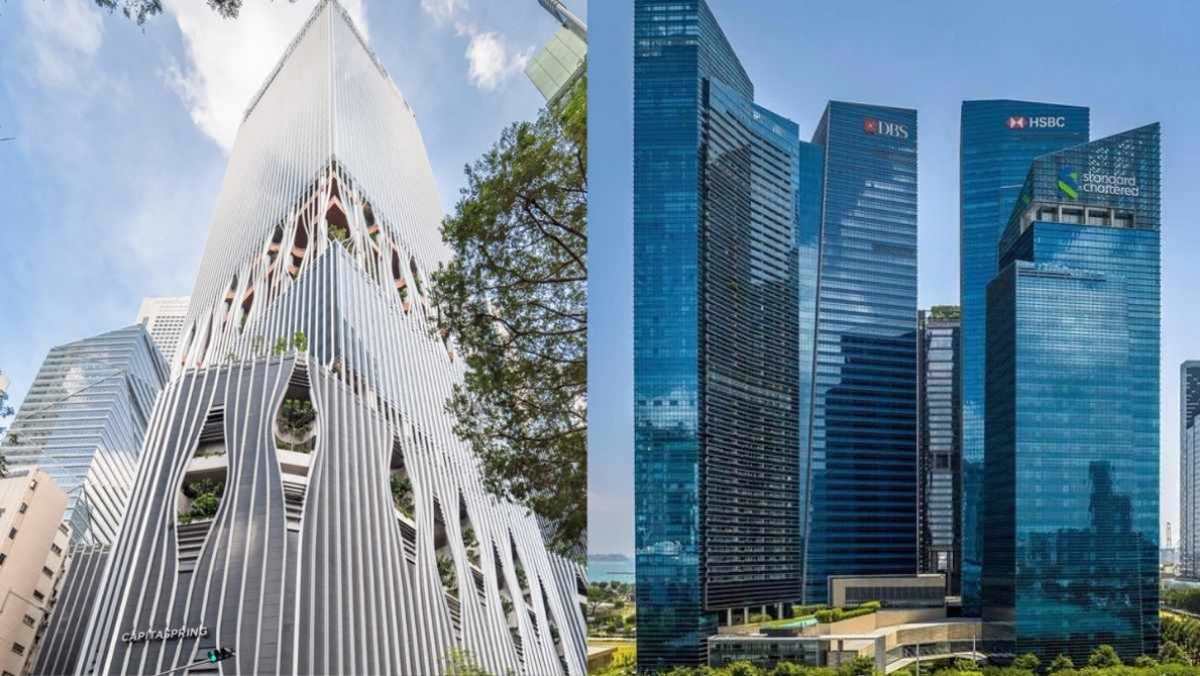
Amid global rate uncertainty, Singapore REITs with office exposure are seeing dividend yields of up to 7% supported by rising rents driven by the AI boom. Investors are focusing on four specific REITs that offer strong financial strength and income sustainability, benefiting from the divergence between office demand in tech hubs versus distressed markets elsewhere. This highlights a bifurcation in the global REIT market, where high-quality assets in specific growth corridors continue to attract yield-seeking capital
Local view
Germany: Local German financial media, including Börse Express and WallstreetONLINE, emphasize the "dramatic underperformance" of Vonovia, noting that the stock is down over 30% since the start of the year. Stakeholders are particularly concerned about the "Berlin expropriation math," which combines political risk with the operational challenge of new construction being "on ice" nationwide due to high financing and construction costs
South Korea: Financial News and Seoul Economic Daily are highlighting a disconnect in official statistics regarding PF loans. They argue that the reported "new PF issuance" figures are misleading because they include "maturity extensions" of existing loans, masking the fact that the market is essentially closed for new deals ("open for business" but actually inactive). This statistical distortion obscures the severe liquidity crunch facing smaller construction firms and the broader supply chain
Context & numbers
- CMBS Delinquency: The Trepp CMBS Delinquency Rate reached 8.02% in September 2026, up 17 basis points month-over-month.
- Special Servicing: The CMBS special servicing rate rose to 11.20% in June 2026, though this is from slightly older data (Q2 report), it sets the baseline for current distress levels.
- Korean PF Outflows: Over 61 trillion KRW has net outflowed from the real estate PF market over the last two years, concentrating remaining capital in large builders and prime Seoul sites.
- Vonovia Stock Performance: Shares are down 32% year-to-date, with Jefferies lowering the target price to €23.00 on October 14, 2026.
- US Treasury Yield: The 10-year Treasury yield hit 5.3% this week, directly impacting commercial mortgage rates and deal viability.
On the radar
- Vonovia Q3 Earnings: Investors are bracing for Vonovia’s Q3 and nine-month results on November 4, 2026, which will provide the first concrete data on how rising financing costs are impacting EBITDA and asset valuations.
- Korean Regulatory Watch: The South Korean National Assembly’s oversight hearings are scrutinizing the DIP (Debtor-in-Possession) finance delinquency rate, which has spiked to 15.6%, potentially leading to stricter capital requirements for policy lenders.
- REIT Dividend Sustainability: With the 10-year Treasury at highs, watch for dividend cut announcements from highly leveraged net lease REITs that have previously relied on cheap debt to maintain payout ratios.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
