
Gold, Silver and Precious Metals Daily — 2026-09-30
Gold rebounded 1.4% to $4,185 on weak U.S. economic data that cut Fed rate-hike bets, while silver held near $61.50. Physical buyers returned ahead of China's Golden Week, though higher bond yields and a firm dollar continue to cap gains. Central bank buying and China's massive gold imports remain structural supports.
Gold, Silver and Precious Metals Daily — 2026-09-30
Top developments
Gold Rebounds $4,185 as Fed Hike Bets Cool
Gold spot price rose 1.39% to $4,184.97 on September 30 as weak U.S. economic data reduced expectations for additional Federal Reserve rate hikes. Silver climbed 1.18% to $61.52 over the same period. However, high Treasury yields and a strong U.S. dollar limited the rebound's upside, keeping both metals well below their January highs.
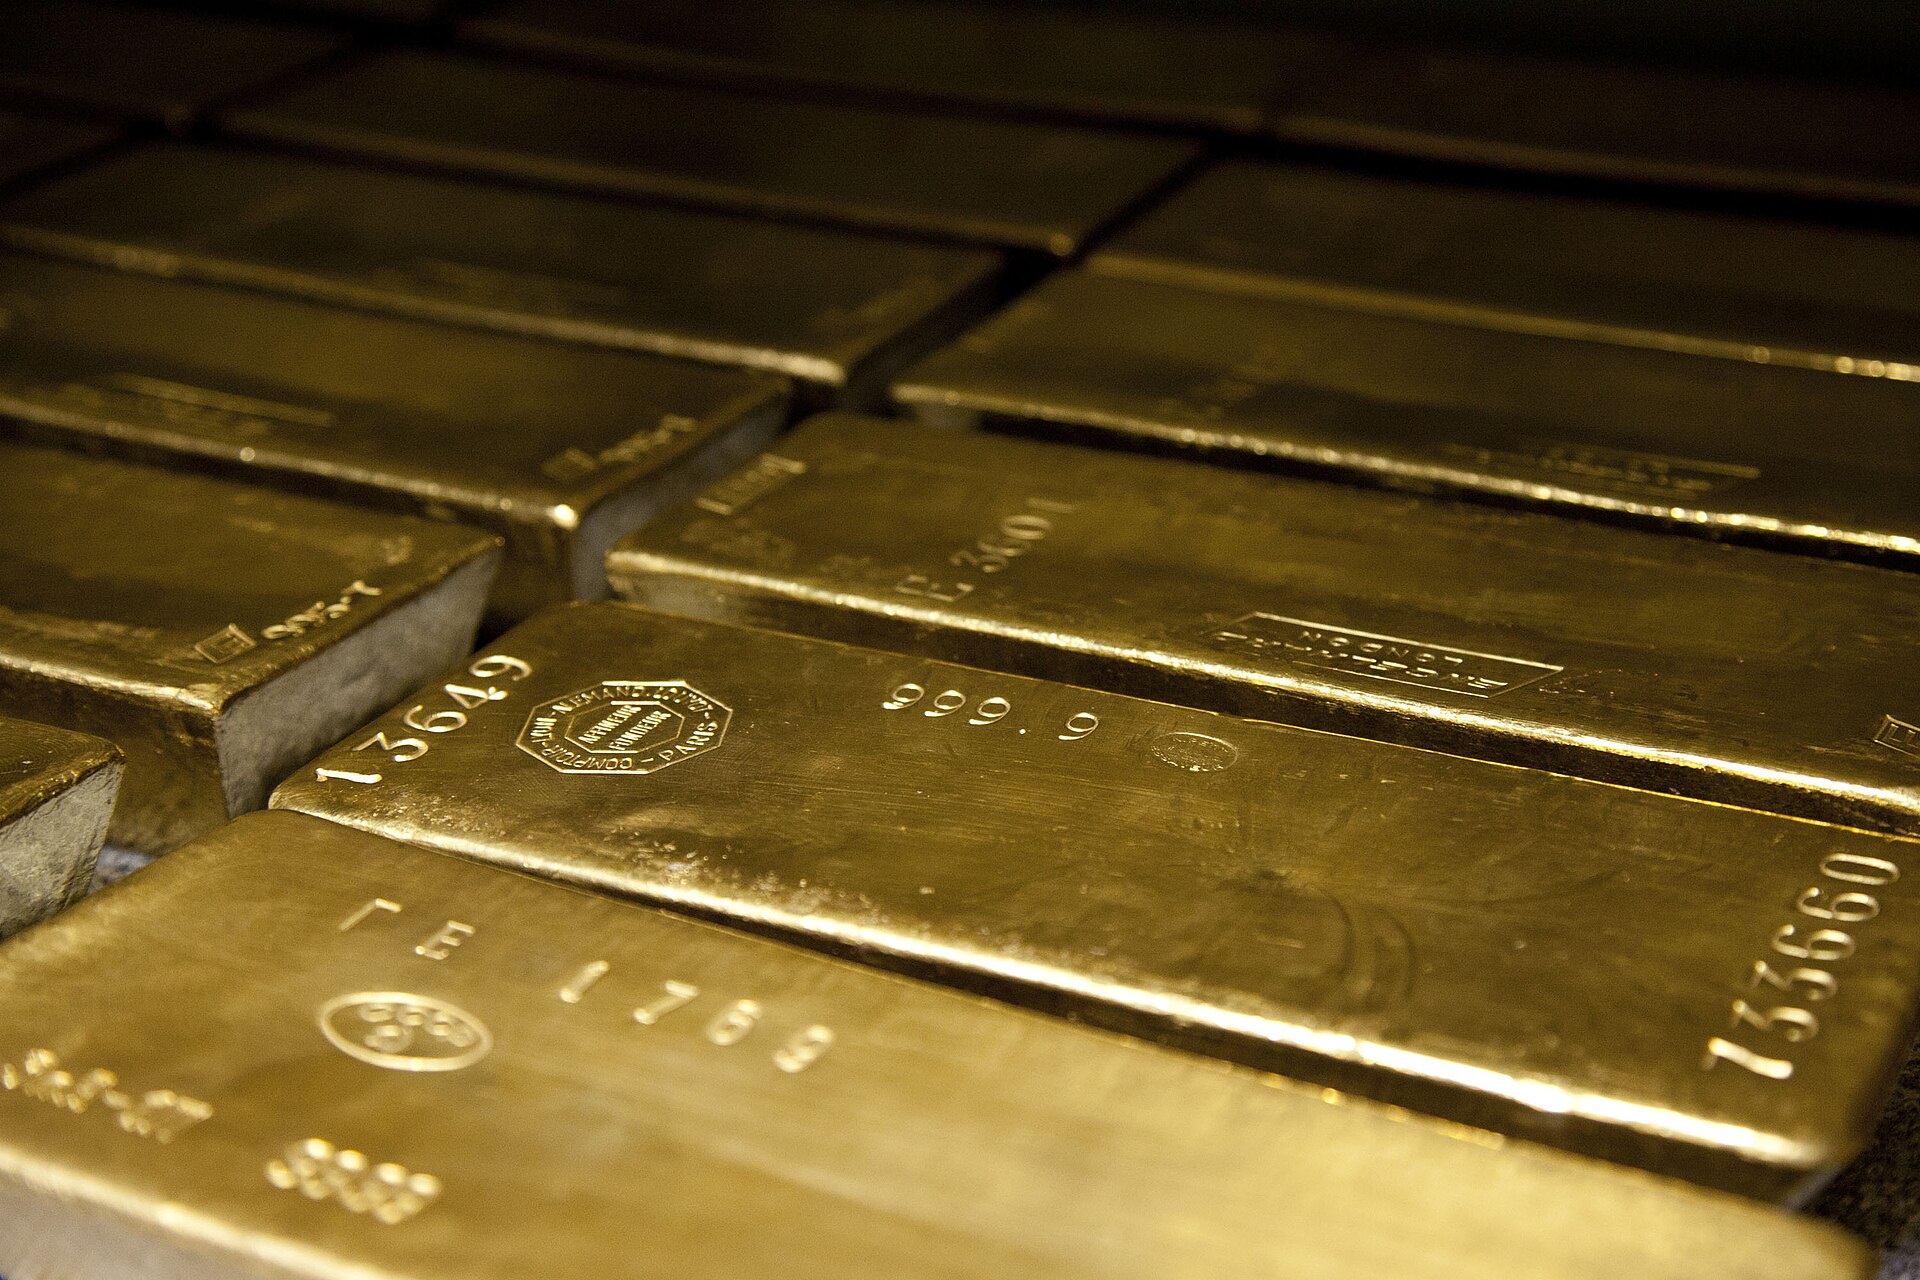
Physical Demand Returns Ahead of China's Golden Week
Physical gold buyers returned to the market on September 29, with spot prices at $4,162.84 and silver holding steady at $61.05 as traders positioned ahead of China's Golden Week holiday season—a period historically associated with elevated jewelry and retail demand in the world's largest bullion consumer. This seasonal strength could provide a floor for prices despite macro headwinds.
Yield Pressure Persists After Two-Day Selloff
Gold and silver prices fell 3.7% and 5.4% respectively on September 29, marking the lowest closes since August 4, hitting levels not seen in nearly two months. Rising U.S. bond yields and dollar strength were the primary drivers, offsetting safe-haven flows. This pullback has tested the $4,100 support level critical to sustaining the 2026 bull market narrative.
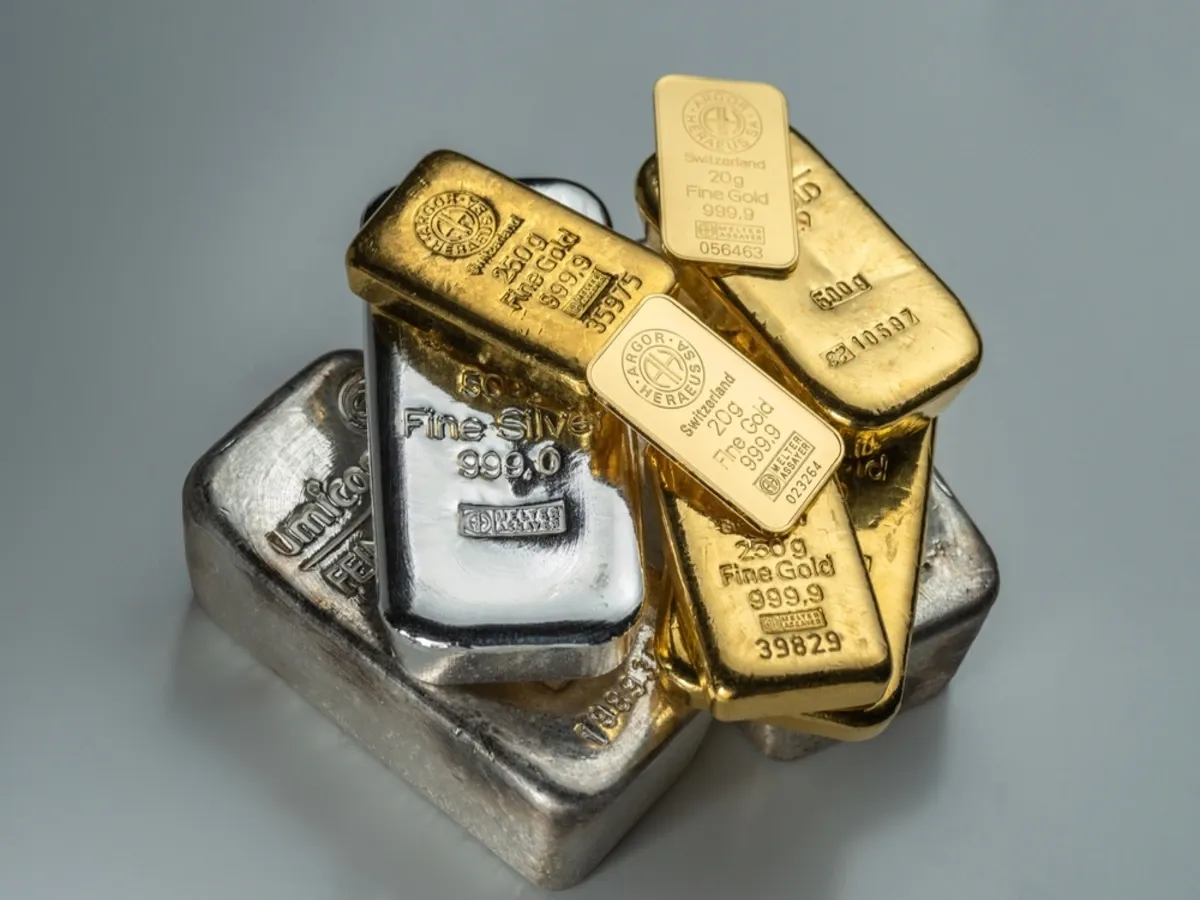
China's 2026 Gold Imports on Pace for 1,700 Tonnes
Heraeus analysts project China will import approximately 1,700 tonnes of gold in 2026, potentially double 2025 levels and the highest in the decade. This non-official sector demand—distinct from the People's Bank of China's official reserve accumulation—underscores sustained bullion appetite independent of price levels. Silver prices face a key test near $60/oz that could determine near-term direction.

Local view
India (Hindi-language market): Gold prices in Delhi fell below ₹150,000 per 10 grams for the first time in two months on September 29, reflecting weak local demand and U.S. dollar strength. Multiple Hindi outlets report gold under "extreme pressure" with analysts such as Praveen Singh of Mirae Asset ShareKhan advising that rallies should be viewed as sell opportunities given macro headwinds.
China (Chinese-language analysis): 21 Jingji reported on September 30 that while gold faces near-term pressure, foreign asset managers maintain a bullish long-term view, arguing that the central bank gold-buying logic remains intact. Official PBOC reserve accumulation continues as a structural floor, with October Q4 outlook tilted positive despite recent weakness.
Context & numbers
Spot prices (as of September 30, 2026):
- Gold: $4,184.97/oz (+1.39% on the day)
- Silver: $61.52/oz (+1.18%)
- COMEX December gold futures: closed near $4,321 on September 26
Central bank buying momentum:
- Central banks purchased 244 tonnes of gold net in Q1 2026, up 3% year-over-year despite higher prices.
- H1 2026 net official purchases estimated at 350–450 tonnes aggregate, implying an annualized run-rate significantly above 2025's 700–800 tonne total.
ETF flows:
- Gold-backed ETF inflows reached $11.5 billion year-to-date by end of February 2026, highlighting normalized investor participation.
India local rates (September 30, 2026):
- Delhi 24-karat gold: approximately ₹149,000–150,000 per 10g (down sharply from ₹155,000+ levels in early September)
On the radar
-
Q4 2026 price targets: Goldman Sachs maintained a year-end target of $4,900/oz, citing strong sovereign demand and estimated China central bank purchases 75% higher than officially reported figures. (Note: This source predates the coverage window but reflects forward guidance still relevant to current positioning)
-
Silver $60 support: Heraeus flagged silver's test near $60/oz as a critical technical level to watch; a break could signal either deeper consolidation or a new directional move into October.
-
ETF positioning divergence: Central banks accumulating while some Western ETF investors trim positions—watch for any shift in this divergence as September quarter closes.
-
China Golden Week effect: October 1 marks the start of a week-long holiday period historically associated with peak Chinese retail gold and jewelry demand; physical premiums and import flows could accelerate through early October.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
