
Mumbai Stocks: Nifty 50 and Sensex Daily — 2026-09-30
Indian markets closed their worst September in 25 years on Wednesday, with the Sensex ending near 72,480 and Nifty at 22,620—down roughly 6% for the month. Crude oil surges, heavy FII selling of ₹9,980 crore, and global geopolitical tensions kept investors on edge as the quarter and fiscal half-year drew to a close.
Mumbai Stocks: Nifty 50 and Sensex Daily — 2026-09-30
Top developments
Sensex and Nifty end September quarter under pressure
On 30 September 2026, the Sensex closed down 48 points at 72,480, while Nifty 50 fell 95 points to 22,620 after three consecutive days of losses. The month of September saw the benchmarks decline approximately 6%, marking the worst quarter-end close in 25 years. Elevated crude oil prices, persistent foreign investor outflows, and elevated US Treasury yields weighed heavily on sentiment. This extends a challenging period for domestic equities as the fiscal half-year closes.
Foreign institutional investors net sellers of ₹9,980 crore
FIIs remained significant net sellers on 29 September 2026, offloading ₹9,980 crore in the cash segment, extending a week-long exodus of foreign capital. This persistent selling pressure—driven by higher global bond yields and geopolitical risks—has been a primary drag on the Indian market. DIIs (domestic institutional investors) have partially offset outflows but have not fully stabilized the market.
Crude oil surge and Iran tensions amplify selloff
Brent crude prices surged amid unresolved US-Iran tensions, with no imminent peace deal in sight. This sharp rise in oil costs has inflated import costs and margin pressures for Indian corporates, contributing to a 1,124-point crash on 28 September and continued weakness through the week. The Iran-US uncertainty is expected to remain a key market trigger into early October.
IPO market resilience amid equity weakness
Despite the broader market downturn, India's IPO market raised $9 billion in the July–September quarter 2026, with over 200 companies still in the pipeline. The Nifty IPO index surged 19.5% for the year, outperforming standard indices, and the primary market filing pipeline exceeded ₹3.86 trillion. This reflects strong investor appetite for new listings even as secondary market sentiment weakens.
Sectoral splits: metals and pharma lead declines
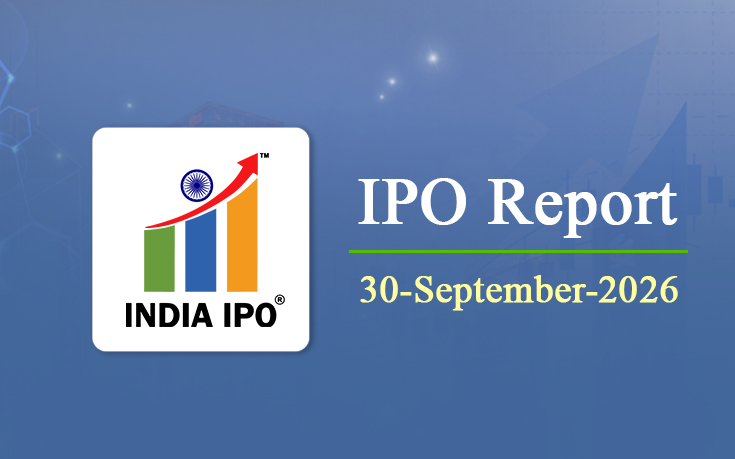
On 30 September, metal and pharma indices fell over 1% each, while PSU Bank, Private Bank, Realty, and Media sectors posted modest 1–2% gains. Top Nifty gainers included ICICI Bank, Kotak Mahindra Bank, and Wipro (Tech), while Apollo Hospitals, Max Healthcare, and SBI Life Insurance dragged. Bank Nifty declined 0.39%, with 17 of 50 Nifty stocks advancing.
Local view
Hindi-language media flagged September's month-end crisis. ETV Bharat highlighted the third consecutive day of losses, noting that pharma stocks saw sharp selling despite modest rupee strength (₹95.81 per USD). Times Now Navbharat called the quarter-end a "25-year worst closing," emphasizing FII positioning and global cues as October expiry triggers. AajTak reported that the Sensex has fallen over 13,000 points in 2026, with the Nifty down 14%, and urged investors to review allocation against market correction risk. Local brokers and fund advisors warned that SIP investors should remain disciplined despite volatility, citing long-term historical recoveries.
Context & numbers
30 September 2026 close (provisional):
- Sensex: 72,480 (−48 pts / −0.07%)
- Nifty 50: 22,620 (−95 pts / −0.42%)
- Bank Nifty: Down 0.39%
- India VIX: 13.32 (subdued volatility despite macro stress)
- Rupee: ₹95.81 per USD (modest 13-paise intra-day recovery)
Monthly (September 2026):
- Sensex: −6% (worst quarter-end in 25 years)
- Nifty: −6% approx.
- YTD losses: Sensex −13,000+ pts; Nifty −14%
FII/DII activity (29 Sept):
- FII net sell: ₹9,980 crore (cash)
- DII activity: Partial offset; insufficient to stabilize indices
- Cumulative Sept FII outflow: Multi-day heavy selling trend
IPO market:
- Q3 2026 (Jul–Sep): $9 billion raised
- Nifty IPO Index YTD: +19.5%
- Pipeline: 200+ companies; ₹3.86 trillion filing queue
On the radar
- October 2026 series F&O expiry: Market typically volatile on expiry days; watch for unwinding of September shorts/longs and fresh positioning into Q3 earnings season.
- RBI policy and US Fed cues: Global bond yields and domestic liquidity remain critical; any dovish Fed pivot or RBI rate guidance could ease pressure.
- Crude oil and Iran-US escalation: Any breakthrough in peace talks could reverse oil surge; watch official channels and news wires for geopolitical updates.
- SIP and mutual fund inflows: August 2026 data showed 10.75 crore active SIP accounts (+13 Lakh net new), with average ticket size ₹3,003—discipline among retail investors may cushion further declines into October.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
