
Iron Ore, Coal and Steel: SGX, Dalian, Newcastle — 2026-09-24
Iron ore slipped this week as Chinese steel demand showed no recovery, with Vale falling 2.61% on Wednesday and Dalian futures hovering near one-month lows around CNY 710/t. The bright spot is coking coal: analysts now see China's supply squeeze lingering into 2027, sustaining import demand and coke prices. Pre-National Day restocking gave only temporary support before fading against weak mill margins.
Iron Ore, Coal and Steel: SGX, Dalian, Newcastle — 2026-09-24
Top developments
Iron ore proxies fall as Chinese steel demand stalls
On Wednesday, September 23, iron ore proxies declined with Vale losing 2.61% to US$13.82 and Rio Tinto down 2.30%, as Chinese steel demand showed no recovery. Earlier in the week, Singapore futures were near US$97 with Vale ADRs flat even as Chinese mills lifted output — a divergence that underscores how rising crude steel output is not translating into stronger margins or ore demand.
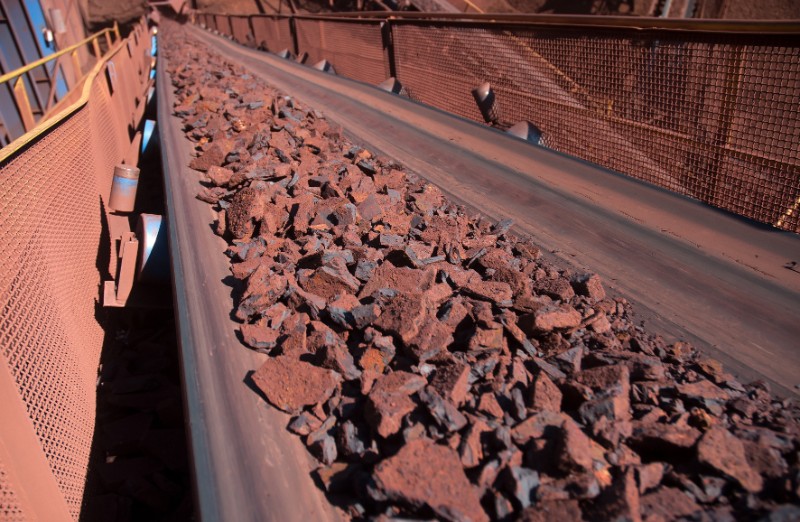
China's coking coal squeeze seen persisting into 2027
Bloomberg reported on September 23 that China's coking coal supply squeeze is set to persist into next year, supporting strong import demand even as domestic output revival efforts start to cool prices. GMK Center adds that the May mining accident in Shanxi Province will have serious, lasting consequences for supply. This is the key bullish undercurrent for ferrous benchmarks even as iron ore softens.
Dalian futures pinned near one-month lows at ~CNY 710
The most-traded Dalian iron ore contract is oscillating near a one-month low around CNY 710 per tonne, pressured by comfortable supply, rising port inventories and widening steelmill losses, per IndexBox on September 24. Chinese-language daily wraps note the January contract (i2701) closed at 715.5 yuan/tonne, with Qingdao PB fines at 678 yuan/tonne (-5) and Eurofer data showing combined Australia–Brazil port stocks at seven major ports of 11.954 million tonnes for Sept 14–20, up 258,000 tonnes week-on-week. domestically, arrivals remain high, keeping the supply side ample and capping rallies.
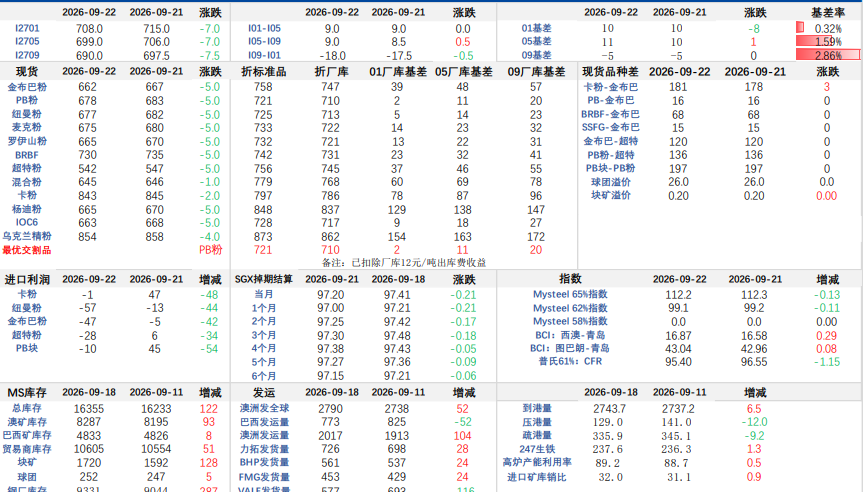
Pre-holiday restocking lift fizzles despite firm Australia/Brazil fundamentals
Iron ore firmed briefly on September 21 as traders hoped Chinese steelmakers would step up raw-material purchases ahead of the National Day holiday (Reuters via UOL), and Dalian rose 0.28% on September 17 on restocking. But analysts say demand remains moderate, end-user consumption is low and steelmakers are broadly loss-making, feeding expectations of production cuts — limiting how far SGX and Dalian can rally. Reuters also flagged a slight uptick supported by El Niño risk to Brazilian shipments.
Local view
Chinese futures desks are notably balanced-to-bearish. Hongyuan Futures (via Sina Finance) describes the market as "多空交织" — bulls and bears in contention — with reduced port arrivals plus pre-holiday restocking offset by ample overall supply; it expects range-bound trading (震荡运行). Everbright Futures' September 23 daily similarly expects short-term prices to trade in a narrow range, noting overseas port stocks remain at the second-lowest level since Q3, so overseas inventory pressure is limited. Chaos Tiancheng Research's September 23 ferrous morning note frames supply-side conditions as the deciding factor.
In Brazil, Valor Econômico reported Dalian steady in the September 24 session and notes analysts still expect a new record year for Brazilian iron ore exports after a record 2025 and 2.4% first-half export growth.
Context & numbers
- Dalian most-traded contract: near CNY 710/t, a one-month low (Sept 24).
- Singapore futures near US$97; 62% Fe benchmark slipping (Sept 22–24).
- Newcastle 6000 thermal coal benchmark last observed at US$144.00/t on 2026-09-19.
- Vale: US$13.82 after a 2.61% drop (Sept 23); Rio Tinto -2.30%.
- Australia/Brazil seven-port ore stocks: 11.954 Mt (Sept 14–20), +258 kt w/w.
- Australia's June outlook projects iron ore export earnings falling from A$116.6bn in 2025–26 to A$77.2bn, per ASPI's The Strategist.
On the radar
- China's National Day holiday restocking window: watch for a demand vacuum after the holiday as mills digest purchases.
- El Niño-related weather risk to Brazilian iron ore shipments — flagged by Reuters as a modest price supportinto October.
- Expected Chinese steelmill production cuts as losses widen — a downside risk for iron ore but supportive of coking coal margins.
- Weekly SMM commentary notes ferrous divergence with raw materials (coking coal, coke) outperforming finished steel — monitor whether coke spot holds at high levels.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
