
Iron Ore, Coal and Steel: SGX, Dalian, Newcastle — 2026-10-13
Iron ore prices in Dalian and Singapore have rebounded slightly on hopes of post-holiday restocking by Chinese steelmakers, though they remain near multi-year lows due to thin margins and high port inventories. Meanwhile, Fortescue Metals Group reported a 6% drop in sales volumes amid an ongoing pricing standoff with China’s state-backed buyer, CMRG, while Australian giants BHP and Rio Tinto are forecast to maintain strong shipment volumes despite the price slump.
Iron Ore, Coal and Steel: SGX, Dalian, Newcastle — 2026-10-13
Top developments
Dalian Iron Ore Rebounds on Restocking Hopes
On Monday, October 12, the most-traded iron ore contract on the Dalian Commodity Exchange (DCE) rose 0.15% to 684.5 yuan ($102.27) per metric ton, marking a slight recovery from an 18-month low hit earlier in the week. This uptick is driven by expectations that Chinese steel mills will increase purchases after the National Day holiday break, although gains were capped by persistent oversupply concerns. For SGX, this volatility keeps short-term hedging costs elevated as traders weigh immediate demand against structural supply gluts.
Fortescue Sales Fall 6% Amid CMRG Standoff
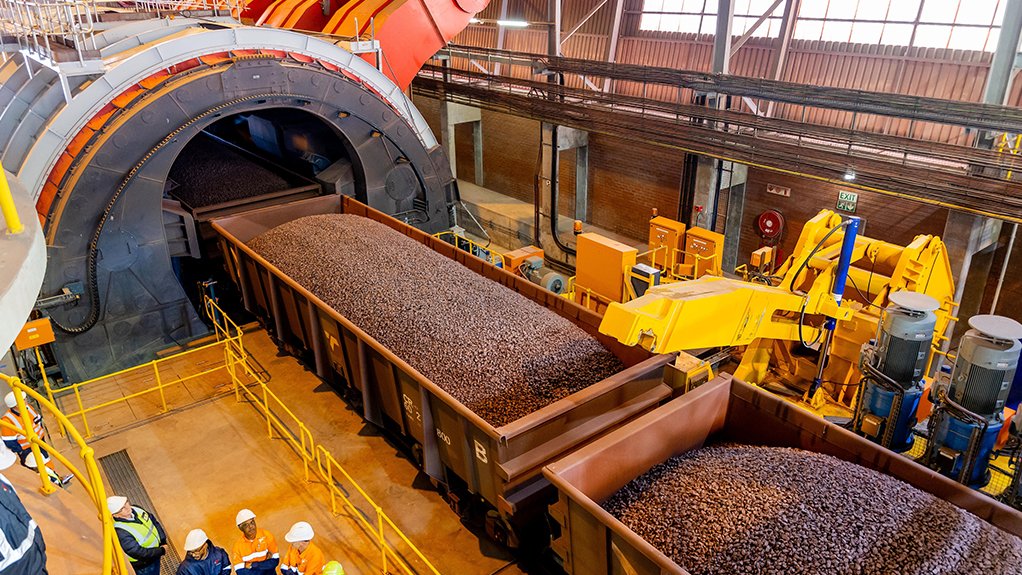
Australian miner Fortescue Metals Group (FMG) reported a 6% decline in iron ore sales for the quarter ended September 30, with volumes falling to 46.8 million tonnes. The company attributed the drop to an unresolved dispute with China Mineral Resources Group (CMRG), the state-backed buyer that has been pressuring miners to accept lower prices and yuan-denominated settlements. Realized prices also dropped to $80 per tonne, significantly below market benchmarks, reflecting the leverage China is exerting in current negotiations.
BHP and Rio Tinto Forecast Strong Shipments Despite Price Lows
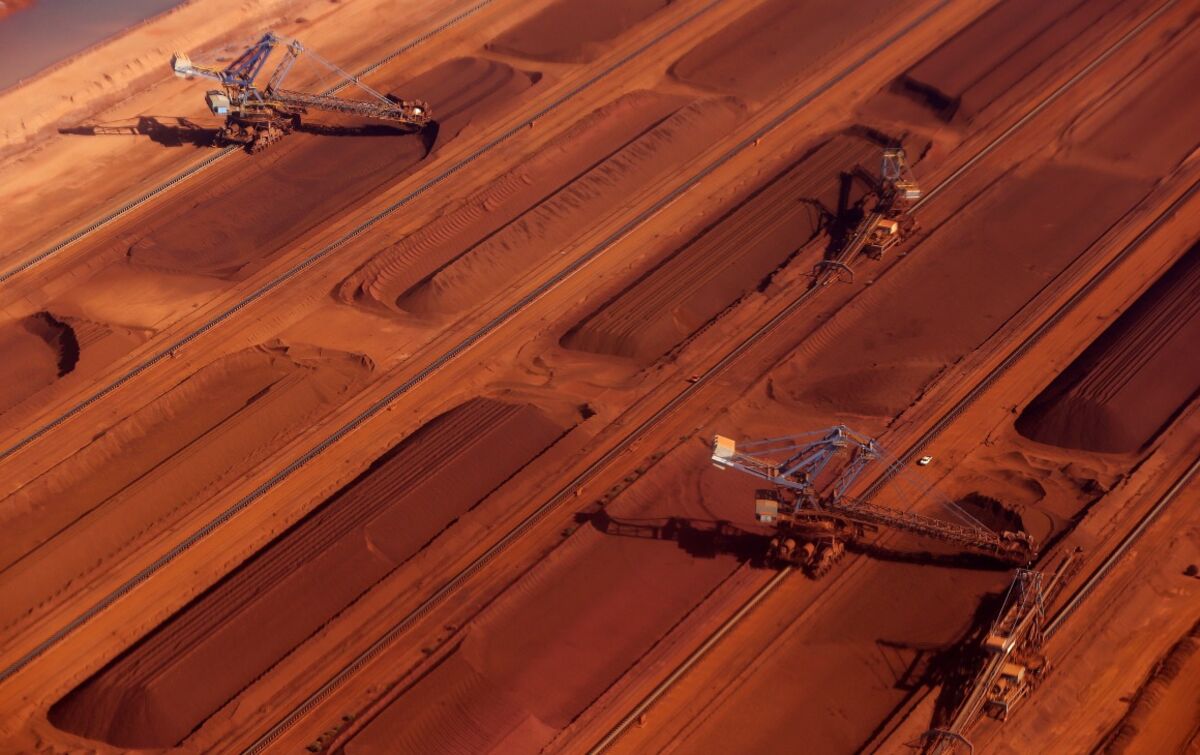
UBS analysts expect BHP and Rio Tinto to deliver stronger iron ore shipments in the September quarter, with BHP projected to ship 75 million tonnes and Rio Tinto 86 million tonnes. This volume growth contrasts sharply with the price environment, where spot prices have hovered near $91 per tonne, levels not seen in over a decade. The divergence underscores a "volume over price" strategy by major miners to maintain market share against lower-cost competitors and to meet contractual obligations despite weak Chinese steel demand.
Chinese Steel Margins Hit Critical Lows
Only 7% of Chinese steelmakers were operating at a profit by the end of September, while average daily crude steel output slid to a six-month low. This collapse in profitability limits the ability of mills to absorb higher raw material costs, creating a ceiling for iron ore prices even during restocking cycles. For Newcastle thermal coal, this weakness in the steel sector reduces coking coal demand, though thermal coal remains supported by power generation needs.
Local view
Port Inventories and Market Sentiment Local Chinese media and data providers like Shanghai SteelHome E-Commerce report that iron ore reserves in Chinese ports have increased to 152.7 million tons, exacerbating the supply-demand imbalance. Industry analysts note that the combination of high inventory and low mill profitability is forcing traders to be cautious, with many waiting for clearer signals on government stimulus before committing to large purchases. The "flooded market" narrative is prevalent in local trade circles, suggesting that without significant policy intervention, prices will remain suppressed.
Context & numbers
- Dalian Iron Ore Futures: Closed at 684.5 yuan ($102.27) per ton on Oct 12, up 0.15% from previous close.
- Fortescue Q3 Sales: 46.8 million tonnes, down 6% year-on-year.
- Fortescue Realized Price: $80 per tonne, reflecting the discount imposed during CMRG negotiations.
- Chinese Port Inventory: 152.7 million tons, contributing to downward price pressure.
- Steel Mill Profitability: Only 7% of Chinese steelmakers profitable as of end-September.
- Thermal Coal (Newcastle): Trading around $152.20 USD/T as of early October, near highs since Oct 2024.
On the radar
- CMRG Negotiations: Watch for updates on the Fortescue-CMRG contract resolution, which could set a precedent for pricing mechanisms for other Australian miners like BHP and Rio Tinto.
- Chinese Stimulus Announcements: Markets are sensitive to any new fiscal or monetary easing measures from Beijing aimed at stabilizing the property and construction sectors, which would directly impact steel and iron ore demand.
- Q3 Earnings Season: BHP and Rio Tinto are expected to release quarterly production reports soon, providing concrete data on shipment volumes versus UBS forecasts.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
