
Japan Bonds and the BoJ: JGB Yields and Taper — 2026-09-14
Japan's benchmark 10-year government bond yield surged past the psychological 3.0% threshold on September 11, driven by a global sell-off linked to rising oil prices and persistent inflation concerns. This volatility has intensified debates among Bank of Japan (BoJ) officials regarding the pace of rate hikes, while the Ministry of Finance's recent auction results indicate mixed demand dynamics as investors navigate a shifting yield curve.
Japan Bonds and the BoJ: JGB Yields and Taper — 2026-09-14
Top developments
10-Year Yield Breaches 3.0% on Oil-Driven Inflation Fears
On Friday, September 11, the benchmark 10-year JGB yield climbed to 3.000%, marking its first close above 3% in approximately one week. The surge tracked a broader global bond sell-off, where escalating Middle East tensions drove up oil prices, reigniting inflation concerns that pressured sovereign debt markets worldwide. This move underscores the sensitivity of Japanese yields to external energy shocks amidst domestic fiscal worries.
BoJ Officials Signal Faster Rate Hikes
Earlier in the week, around September 10, the 10-year yield rose by 5 basis points to 2.93% after a Bank of Japan official publicly made a case for accelerating interest rate hikes. This commentary shifted market expectations toward tighter monetary policy sooner than previously anticipated, contributing to upward pressure on yields despite earlier relief from yen strength. The shift highlights the internal tension within the BoJ between managing currency stability and controlling inflation through rate normalization.
Short-End Yields Ease on Yen Strength
In contrast to the long-end volatility, shorter-term yields declined earlier in the coverage period (around September 9) as a stronger yen reduced immediate expectations for aggressive BoJ tightening. The two-year yield dropped to 1.835%, while the five-year yield fell to 2.22%. This divergence suggests that while the long end is driven by inflation and fiscal concerns, the short end remains sensitive to currency movements and near-term policy expectations.
Repatriation Risk Debates Intensify
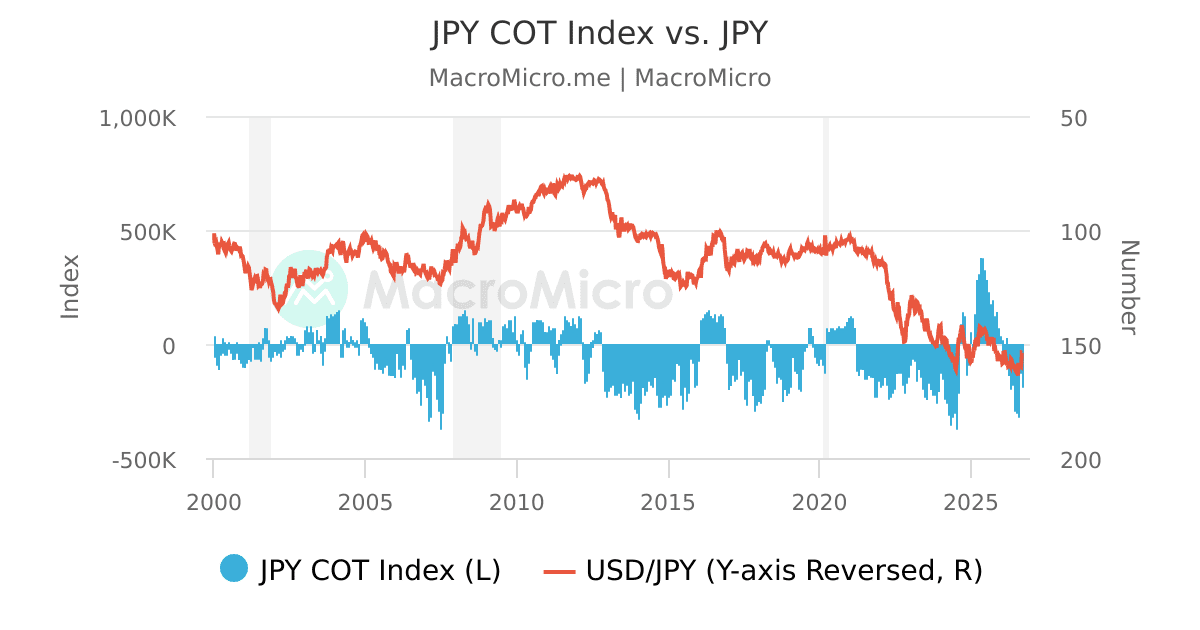
As yields approach 30-year highs, discussions about the "repatriation risk" have gained prominence. Investors are increasingly concerned that higher domestic yields in Japan will incentivize life insurers and other institutional investors to bring capital back home, potentially causing significant outflows from foreign bond markets like US Treasuries. This dynamic adds a layer of complexity to global asset allocation strategies as Japan exits its era of ultra-loose monetary policy.
Local view
Nikkei Shimbun reports that the return of the 10-year yield to the 3% level has caused significant unease in the domestic bond market, with participants questioning who will absorb the supply as yields rise. The outlet notes that while short-term dips occurred due to yen appreciation, the underlying trend remains upward due to persistent inflation fears and fiscal deficit concerns.
Bloomberg Japan highlights that the recent spike is not just a domestic phenomenon but part of a global re-pricing of sovereign risk, with Japanese yields moving in tandem with US Treasuries due to shared exposure to oil-driven inflation shocks. The Japanese-language coverage emphasizes the fragility of the current rally in bonds, noting that any further escalation in geopolitical tensions could push yields even higher.
Context & numbers
- 10-Year JGB Yield: Reached 3.000% on September 11, up 9 basis points from the previous day.
- Short-Term Yields (Sept 9): 2-Year yield fell to 1.835%; 5-Year yield declined to 2.22%.
- Recent Auction Data: The Ministry of Finance conducted a 5-Year JGB auction on September 8, 2026. Detailed bid-to-cover ratios for this specific auction were not explicitly detailed in the fresh snippets, but the context suggests continued scrutiny on demand levels.
- Market Size: Japan’s bond market remains valued at approximately $7.5 trillion, with the shift away from BoJ dominance creating a vacuum that private investors are struggling to fill at lower yields.
On the radar
- Upcoming Auctions: Market participants are closely watching the next scheduled super-long (20/30/40-year) auctions for signs of life insurer demand recovery or further deterioration, which will be critical for assessing the sustainability of current yield levels.
- BoJ Outlook Report: Attention turns to any interim assessments or speeches from BoJ Governor Ueda regarding the timeline for reducing JGB purchases, particularly as the taper plan targets ~2 trillion yen/month by Q1 2027.
- Oil Price Volatility: Continued fluctuations in crude oil prices remain a primary driver for inflation expectations, directly impacting the long end of the JGB curve.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
