
Natural Gas and LNG: TTF, JKM, Henry Hub Daily — 2026-10-17
European natural gas prices have surged to their highest levels since December 2022, driven by a collapse in Middle East LNG flows through the Strait of Hormuz and below-average EU storage levels. Meanwhile, the widening spread between European and Asian benchmarks has tilted LNG arbitrage economics toward Asia, while U.S. supply faced temporary disruption from Hurricane Isaias.
Natural Gas and LNG: TTF, JKM, Henry Hub Daily — 2026-10-17
Top developments
TTF Hits Four-Year High as Hormuz LNG Flows Lag
European benchmark TTF front-month contracts traded around €86/MWh (approx. $96.50/MWh) in mid-October, approaching levels last seen at the end of 2022. This rally is attributed to Persian Gulf LNG flows remaining significantly below pre-war levels, with traffic through the Strait of Hormuz still more than 75% down compared to previous years. The supply squeeze is exacerbated by EU storage standing at 74.02% full as of October 15, trailing the five-year average and raising concerns about winter adequacy.

Arbitrage Economics Shift Toward Asia
The sharp rise in European TTF prices has altered the JKM-TTF spread, tilting LNG arbitrage economics in favor of deliveries to Asia. According to Spark Commodities data, the TTF December 2026 contract increased markedly, making U.S. LNG cargoes more attractive for Asian buyers who have been facing high spot prices. This shift indicates that while Europe is paying a premium for scarce supply, the relative value gap is now encouraging flows toward Northeast Asia to balance global markets.
Korea Doubles North American LNG Imports Amid Middle East Collapse
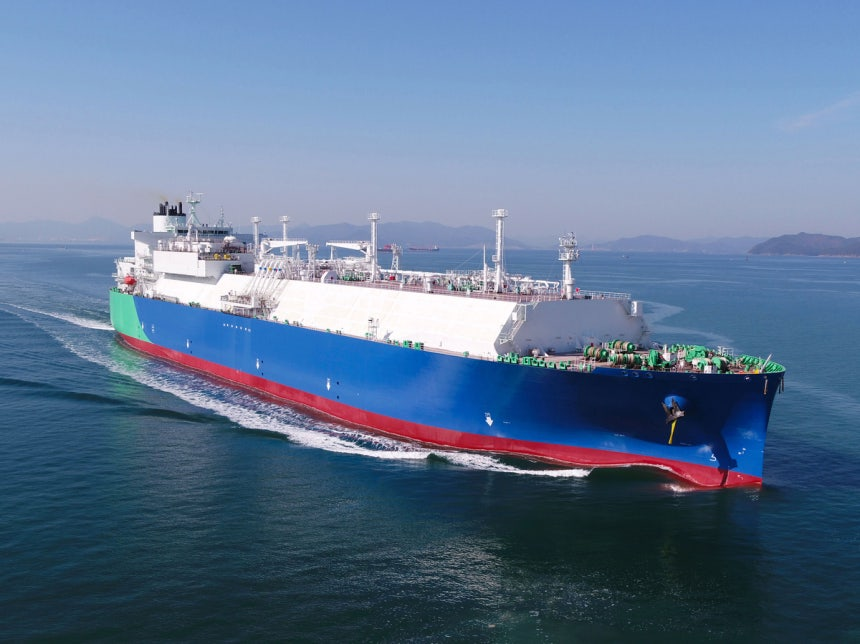
South Korea’s LNG imports from the Middle East plummeted by 66.2% in the first nine months of 2026 due to regional conflicts and supply disruptions. In response, Korean buyers more than doubled their LNG imports from North America to secure supply security. This pivot highlights the structural shift in Asian procurement strategies, moving away from traditional Middle East sources toward U.S. and other non-Hormuz suppliers to mitigate geopolitical risk.
US Supply Disrupted by Hurricane Isaias
U.S. natural gas supply faced temporary disruption due to Hurricane Isaias, the first Atlantic hurricane of the 2026 season. Offshore production in the Gulf of Mexico fell sharply as producers shut in operations ahead of the storm’s October 9 landfall. Production has since begun to recover, but the event introduced volatility into Henry Hub prices and highlighted the vulnerability of U.S. supply chains during peak hurricane season.
Local view
German media outlets are focusing on the "Gaspreis-Schock" (gas price shock), with reports noting that European reliance on LNG is driving TTF to record levels. Industry observers note that Germany’s storage levels are notably low at approximately 60.1%, contributing to heightened anxiety about winter heating costs and industrial energy security. Local analysts warn that the decoupling from Russian gas has left the market exposed to global LNG volatility, particularly with Middle East flows compromised.

Context & numbers
- TTF Price: Front-month TTF futures settled at €87.2/MWh for November delivery, up from €72.5/MWh on September 30.
- EU Storage: Overall EU gas storage was 74.02% full on October 15. Germany is at 60.1% and the Netherlands at 63.3%.
- Hormuz Flows: LNG flows through the Strait of Hormuz remain more than 75% below pre-war levels.
- JKM Trends: The Japan Korea Marker (JKM) for November delivery rose to the low $26/MMBtu range in early October, up from the high $24/MMBtu range in late September, reflecting tight Asian supply.
- US Production: Hurricane Isaias caused a sharp, temporary decline in Gulf of Mexico offshore production in early October.
On the radar
- El Niño Impact: A potential "super El Niño" is being watched as a factor that could warm key Asian winters through January 2027, potentially softening LNG demand in Japan, South Korea, and China. This could free up cargoes for Europe, which is currently facing a storage deficit.
- Coal Substitution: Global coal demand is rising as LNG prices remain high, with coal being roughly 80% cheaper than LNG. Asian and European buyers are increasingly switching to coal for power generation ahead of winter.
- India’s Demand Drop: Wood Mackenzie reports that the Iran conflict and resulting high spot prices have cut India's LNG demand by approximately 1.5 million tons.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
