
Natural Gas and LNG: TTF, JKM, Henry Hub Daily — 2026-10-14
European gas prices surged to multi-year highs, with TTF futures exceeding €87/MWh as storage deficits and Middle East supply disruptions converge. In Asia, demand is contracting sharply due to prohibitive spot prices and the ongoing Strait of Hormuz closure, while US Henry Hub prices remain relatively stable despite strong LNG feedgas demand.
Natural Gas and LNG: TTF, JKM, Henry Hub Daily — 2026-10-14
Top developments
European Gas Prices Hit Highest Levels Since 2022
On October 13, Dutch TTF front-month futures rose above €87/MWh, marking the highest level since late 2022. This surge is driven by a combination of low European storage inventories, which are approximately 17 percentage points below seasonal norms, and continued disruptions to LNG flows from the Middle East. The price spike reflects acute winter supply fears, with ENTSOG warning that tight supplies could push inventories to critical levels by March 2027 if withdrawals accelerate.
Strait of Hormuz Closure Strands Middle East LNG Supply
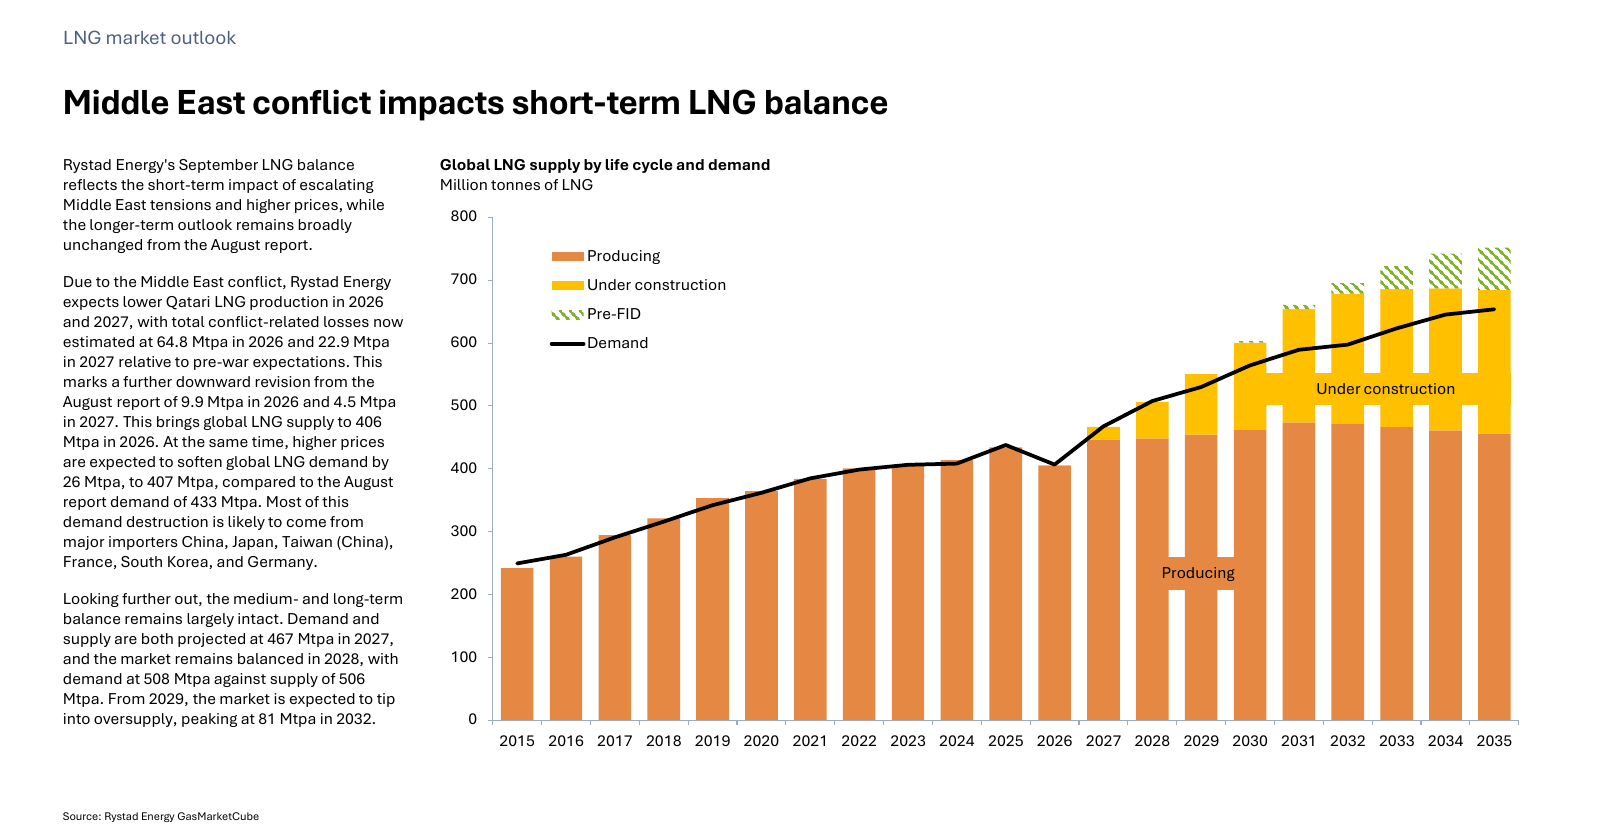
Flows of LNG through the Strait of Hormuz remain more than 75% below pre-war levels as of October 13, leaving significant volumes of Qatari and other Middle Eastern LNG stranded. This disruption has fundamentally altered global trade flows, forcing buyers in Asia and Europe to compete for non-Middle Eastern cargoes. The persistent bottleneck is a primary driver behind the bifurcation of Asian markets, where only select buyers can afford the inflated spot rates.

South Asia LNG Demand Falls by 6 Mt Due to Price Shock
Wood Mackenzie projects that South Asia’s LNG demand will fall by approximately 6 million tonnes (Mt) in 2026, largely due to the closure of the Strait of Hormuz and resulting price spikes. High fuel costs are impacting energy-intensive industries in China and reducing output, while emerging buyers in India and Bangladesh are struggling with the cost of securing spot cargoes. This demand destruction is expected to persist through the winter, easing some pressure on global supply but failing to alleviate European tightness.
Japan Strengthens LNG Security Amid Regional Conflict
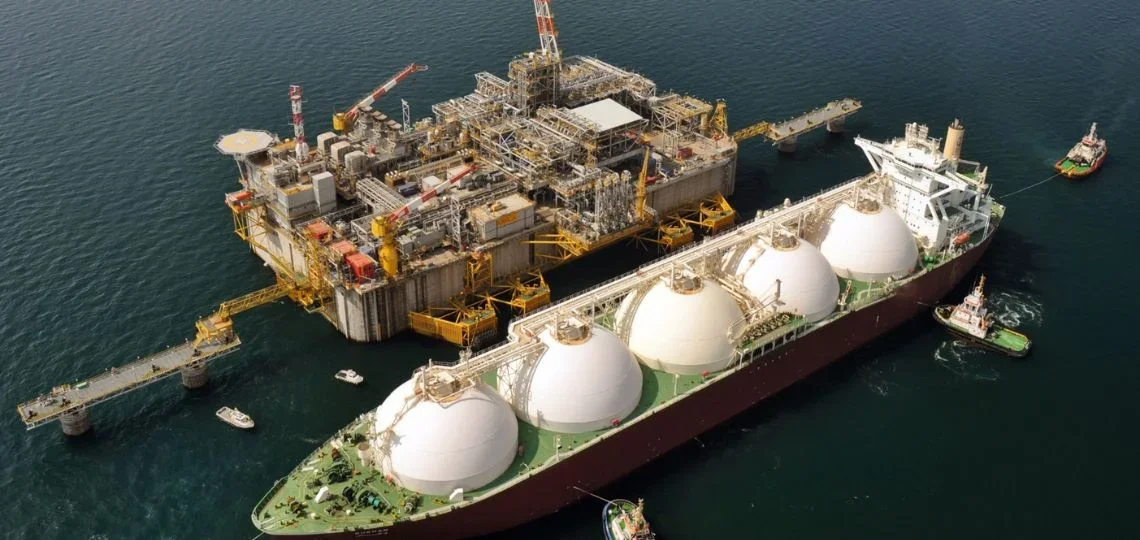
In response to the ongoing conflict involving Iran and threats to shipping lanes, Japan is actively strengthening its LNG supply security measures. Japanese utilities are diversifying procurement sources and increasing reliance on long-term contracts to mitigate the volatility of spot markets disrupted by the Middle East situation. This strategic pivot highlights the vulnerability of major Asian importers to geopolitical shocks and their efforts to secure stable winter supplies.
Local view
German media outlets report that the European gas price rise has reached a multi-year high, with onvista.de noting the TTF contract exceeding €86/MWh on Tuesday. The coverage emphasizes that low storage levels and geopolitical tensions are the primary drivers, causing concern among German consumers and industries about winter energy costs. RND.de highlights that German gas storage remains "strikingly empty" ahead of the heating season, maintaining heightened scrutiny of supply security since decoupling from Russian gas in 2022.
Context & numbers
- TTF Price: > €87/MWh (Oct 13), highest since Dec 2022.
- EU Storage: ~73.29% full as of Oct 8, refilling at +0.20 points/day, below the rate needed for the 80% November target.
- Hormuz Flows: >75% below pre-war levels.
- South Asia Demand: Expected to fall by ~6 Mt in 2026.
On the radar
- Super El Niño Forecast: A potential super El Niño could warm Asia's winter, easing regional LNG demand and potentially freeing up cargoes for Europe, though this remains a forecast-dependent variable.
- Coal Substitution: Global coal demand is rising as LNG becomes uncompetitive; coal is roughly 80% cheaper than LNG, encouraging a shift in both Asia and Europe.
- US Spot Prices: Natural gas spot prices in the US are surging as LNG terminals and industrial furnaces revive demand, potentially tightening domestic supply for export.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
