
Natural Gas and LNG: TTF, JKM, Henry Hub Daily — 2026-09-19
European TTF prices remain elevated above €80/MWh due to critically low storage levels and Middle East supply disruptions, while Asian JKM prices hit a 45-month high as buyers reduce volumes. The divergence is widening: Europe is outbidding Asia for spot LNG cargoes to fill storage deficits, pushing Asian demand down for a second consecutive year. <!-- /headline --> Europe Outbids Asia for LNG as Prices Surge 150% <!-- /headline -->
Natural Gas and LNG: TTF, JKM, Henry Hub Daily — 2026-09-19
European TTF prices remain elevated above €80/MWh due to critically low storage levels and Middle East supply disruptions, while Asian JKM prices hit a 45-month high as buyers reduce volumes. The divergence is widening: Europe is outbidding Asia for spot LNG cargoes to fill storage deficits, pushing Asian demand down for a second consecutive year.
<!-- /headline -->Europe Outbids Asia for LNG as Prices Surge 150%
<!-- /headline -->Top developments
TTF Holds Above €80/MWh Amid Storage Deficit
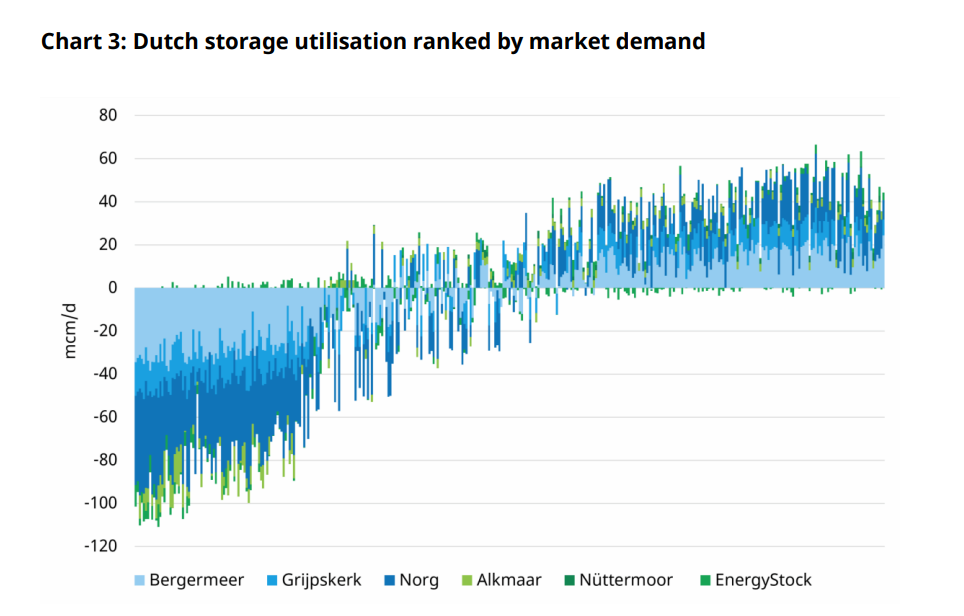
Dutch Title Transfer Facility (TTF) front-month futures held above €80/MWh in mid-September, driven by EU gas storage levels at just 68%, significantly below the 84% five-year average. Analysts warn that the current refill rate of +0.21 points per day is insufficient to meet the relaxed 80% November target, leaving the market exposed to winter price spikes.
JKM Hits 45-Month High as Asia Reduces Buying
Asian spot LNG prices (JKM) reached a 45-month high this week, with November delivery cargoes priced near $26/MMBtu. Despite the price surge, Northeast Asian importers are cutting back; September arrivals are projected at 20.09 million metric tons, the lowest for the month in eight years. This reduction is primarily due to high costs deterring buyers in China and South Asia, who are substituting fuels or reducing industrial output.
Hormuz Transits Resume with Ship-to-Ship Transfers
After months of near-total disruption, LNG carriers have begun transiting the Strait of Hormuz again, with two vessels passing through this week. Qatar and the UAE are utilizing ship-to-ship transfers near Oman to maintain supply flows amidst ongoing security concerns. This partial resumption has provided some relief to global supply fears but has not yet normalized shipping risk premiums or fully restored Qatari export volumes to pre-crisis levels.
Henry Hub Stable While Global Arbitrage Widens
U.S. natural gas prices at Henry Hub remained relatively stable compared to the volatile international benchmarks, with EIA data indicating storage inventories increased by 30 Bcf for the week ending August 28. The stability in U.S. domestic supply contrasts sharply with the 150% surge in spot market prices elsewhere, highlighting the structural arbitrage that encourages U.S. LNG exports to Europe and Asia despite domestic production records.
Local view
Germany (Telepolis & WallstreetONLINE): German media reports that national storage levels are at approximately 56%, the lowest since records began 15 years ago. Telepolis highlights that despite increased LNG imports, filling storage to historical norms remains "utopian" for this winter, with consumer prices facing continued pressure. WallstreetONLINE notes that while physical supply security is maintained, procurement costs are escalating drastically due to the "Hormus worries."
Japan (Mezha.net): Japanese-language coverage via Mezha.net indicates that Asian LNG imports will drop to an eight-year low in September. The report emphasizes that the "Qatar supply shock" is directly impacting Japanese utilities, forcing a strategic shift where Europe's aggressive bidding for remaining cargoes further squeezes Asian availability.
Context & numbers
- TTF Price: >€80/MWh (near 2022 highs).
- JKM Price: ~$26/MMBtu (45-month high).
- EU Storage Level: 68.04% (vs 84% five-year avg).
- German Storage Level: ~56% (lowest in 15 years).
- Asian Demand Forecast: Expected to fall 3%-10% in 2026 due to price sensitivity and supply constraints.
- Price Differential: Europe is paying roughly 10 times the U.S. wholesale gas price, driving the export arbitrage.
On the radar
- November 1 Storage Target: Monitor if EU storage can reach the relaxed 80% target; current trajectory suggests a miss, which could trigger emergency policy responses.
- Hormuz Shipping Normalization: Watch for further confirmation of ship-to-ship transfer reliability near Oman; any new attacks could instantly spike JKM and TTF again.
- Asian Winter Procurement: Chinese and Indian buyers may return to the spot market later in the season if prices correct, potentially competing with Europe for remaining cargoes.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
