
Southeast Asia Rates: BI, BSP, BoT, BNM and SBV — 2026-10-10
Bank Indonesia has pivoted its liquidity strategy, moving away from high-yield SRBI instruments to lower funding costs and boost banking liquidity, while foreign capital inflows into Indonesia hit Rp131.1 trillion. Meanwhile, Thai bond yields surged to 2.37% amid a "bear steepening" trend, and Vietnam’s State Bank of Vietnam adjusted its central rate downward as US Treasury yields spiked globally.
Southeast Asia Rates: BI, BSP, BoT, BNM and SBV — 2026-10-10
Top developments
Bank Indonesia Abandons High-Yield SRBI Strategy for Liquidity Relief
On October 9, CNBC Indonesia reported that Bank Indonesia (BI) Governor Destry Damayanti changed the strategy regarding Sekuritas Rupiah Bank Indonesia (SRBI) yields to reduce funding costs and strengthen bank liquidity. The move includes hedging incentives and a reduction in the Reserve Requirement Ratio (GWM), aiming to ease the pressure on domestic banks that had been absorbing higher costs from the previous high-yield SRBI auctions
Foreign Capital Inflows into Indonesia Reach Rp131.1 Trillion
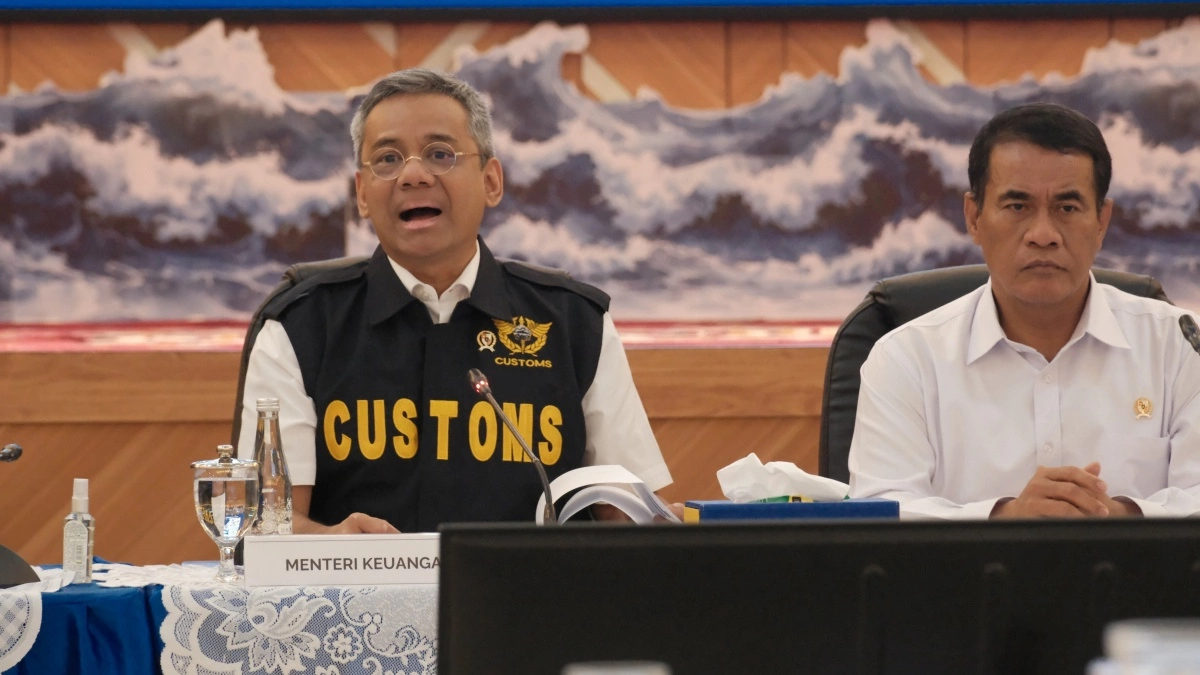
As of early October 2026, cumulative foreign capital inflows into Indonesia reached Rp131.1 trillion, driven primarily by strong demand for State Securities (SBN) and SRBI, which offset outflows in the equity market. Finance Minister Suahasil Nazara confirmed that while the stock market faced pressure, the bond market remained robust, attracting significant foreign portfolio investment
Thai Bond Yields Surge to 2.37% Amid Bear Steepening
The Thai Bond Market Association (ThaiBMA) reported that the 10-year Thai government bond yield rose to 2.37%, marking a "bear steepening" pattern over the first nine months of the year where longer-term yields increased faster than short-term ones. Despite this rise, ThaiBMA forecasts that yields will stabilize in Q4, with the Bank of Thailand (BoT) expected to maintain its policy rate at 1.00%
Vietnam’s Central Rate Adjusted as US Yields Spike
The State Bank of Vietnam (SBV) reduced the central exchange rate by 7 VND on October 8 to 25,638 VND per USD, reflecting a slight reversal in global USD strength. This adjustment comes amidst a broader trend where US Treasury yields have surged, with 10-year yields seeing their strongest quarterly increase since 2000 in Q3 2026, impacting emerging market currencies across the region

Local view
Local media in Indonesia and Thailand are focusing heavily on the divergence between bond market strength and currency pressure. In Indonesia, Kompas Money highlighted that the 10-year SBN yield jumped to 7.24% as the rupiah struggled near Rp17,900 per USD, noting that rising credit risk premiums and global bond volatility are key drivers.
In Thailand, Bangkokbiznews analysts argue that the current rise in bond yields is not a repeat of the 2022 crisis, pointing out that real yields now reflect a stronger economic backdrop rather than pure inflation fear. They suggest investment opportunities remain in Investment Grade debt despite the higher rates.
Context & numbers
- Indonesia: Foreign inflows totaled Rp131.1 trillion by early October 2026. The 10-year SBN yield stood at 7.24% as of October 10. Foreign reserves dropped slightly by $200 million to $146.3 billion in September due to rupiah stabilization efforts
- Thailand: The 10-year government bond yield reached 2.37%. The policy rate remains at 1.00%.
- Vietnam: The central exchange rate was set at 25,638 VND/USD on October 8. Government bond issuance via auction raised over 70.139 trillion VND in September alone. The 10-year government bond yield hovered around 4.43%, the highest level since 2023
On the radar
- US Treasury Yield Spike: Vietnamese media is closely watching US 10-year Treasury yields potentially hitting 6% for the first time since 2000, which could exert further pressure on EM Asia currencies and bond markets.
- Malaysia Budget: Malaysia is scheduled to table its national budget shortly, a key event for regional fiscal outlooks mentioned in recent macro monitors.
- FOMC Minutes: Indonesian market participants are monitoring upcoming FOMC minutes and US consumer confidence data as potential triggers for further rupiah volatility.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
