
Southeast Asia Rates: BI, BSP, BoT, BNM and SBV — 2026-10-17
Bank Indonesia faces intensifying pressure to hike rates after MSCI's reclassification warning triggered a 11% stock rout and pushed the rupiah past Rp18,000 per USD. Meanwhile, Asian bonds recorded their largest monthly foreign outflow since March 2020, forcing policymakers to balance defense of local currencies against rising yields.
Southeast Asia Rates: BI, BSP, BoT, BNM and SBV — 2026-10-17
Top developments
MSCI Downgrade Threat Triggers Rupiah Rout and BI Hike Speculation
On October 16, MSCI Inc. warned it may reclassify Indonesia’s stock market to standalone status, sparking an 11% drop in the Jakarta Composite Index (JCI) and pushing the rupiah to Rp17,938 per USD on October 15. Analysts now view a Bank Indonesia rate hike at the upcoming October 21 meeting as highly probable to defend the currency and prevent further capital flight. The threat of downgrade has directly pressured bond yields, with 10-year SBN yields projected to reach 7.15%–7.55% by year-end.
Asian Bonds See Worst Foreign Outflow Since 2020
Asian government bonds recorded their biggest monthly foreign outflow since March 2020 in September, driven by a stronger US dollar and the lingering effects of the Q1 energy shock. This massive capital exit has pressured policymakers across ASEAN to maintain tight monetary stances, with foreign investors pulling billions from local currency bonds. The outflow underscores the region's vulnerability to global yield shifts and risk-off sentiment.

BNM Governor Signals Readiness to Adjust Rates on Inflation Risks
Bank Negara Malaysia (BNM) Governor Abdul Rasheed Ghaffour stated on October 15 that the central bank has greater room to adjust interest rates following its recent policy guidance change. He emphasized that BNM stands ready to act if inflation pressures intensify, particularly as the Middle East conflict keeps energy prices elevated. This signal suggests BNM may pivot from a neutral stance to a more defensive posture if global inflation persists.
BoT Maintains 1% Rate Policy Despite Global Tightening
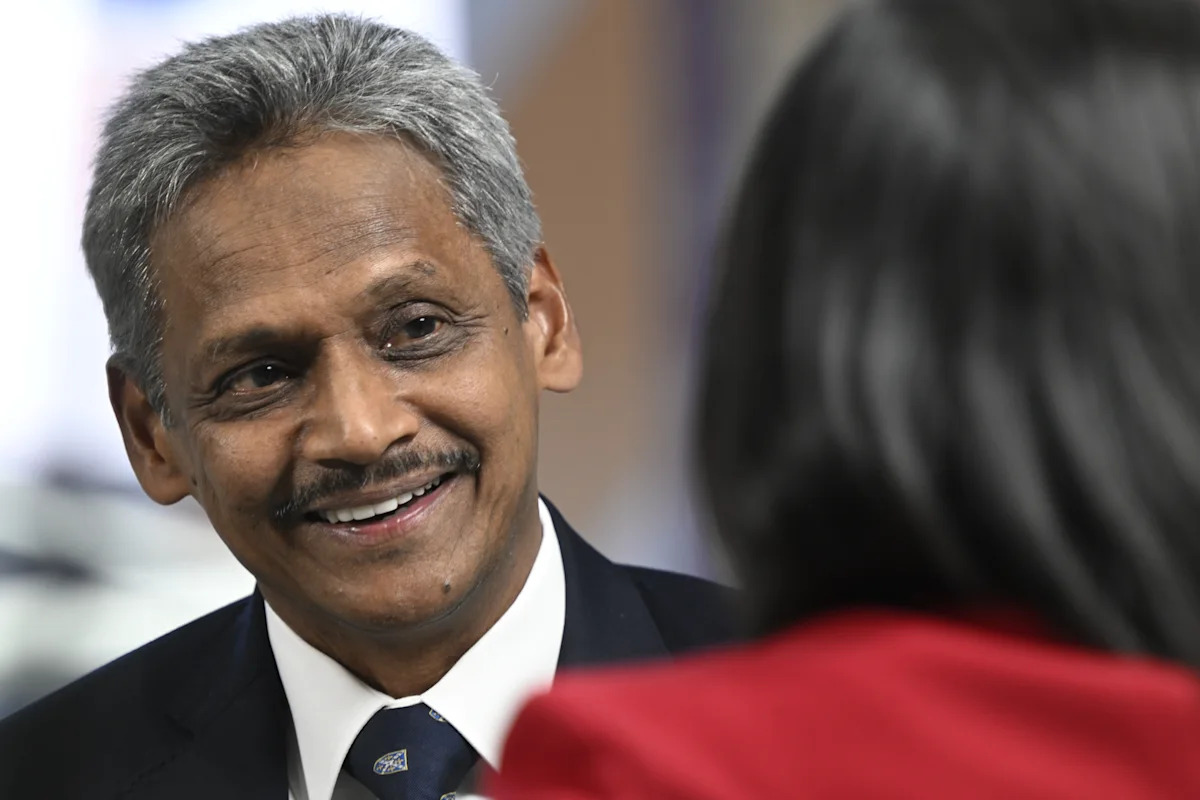
The Bank of Thailand (BoT) continues to hold its policy rate at 1.00%, with officials asserting that this level remains appropriate amid managed inflation. BoT Governor Vitai Ratanakorn noted on October 13 that there is still "policy space" to handle risks, and the committee will wait for more economic data before any decision. Thai 10-year bond yields have risen to 2.37%, but the BoT argues the rate differential with the US is not yet causing significant capital outflows.
Vietnam’s Interbank Rates Diverge as USD/VND Stabilizes
In Vietnam, interbank interest rates showed diverging trends on October 16, with VND rates falling for short-term tenors while USD rates increased. The USD/VND exchange rate has stabilized as the US dollar retreated from its 18-month peak, reducing immediate pressure on the State Bank of Vietnam (SBV) to intervene. VCBS Research forecasts that domestic factors may help limit further devaluation of the dong despite ongoing global USD strength.

Local view
Indonesian media outlets are heavily focused on the "MSCI Domino Effect," with Rikopedia Research and Kompas.id analyzing how the stock market sell-off is spilling over into bond yields and currency weakness. Kontan reports that foreign capital outflows from Indonesian assets could reach Rp60 trillion if the MSCI downgrade materializes, forcing BI to keep rates high or hike further. In Thailand, Kaohoon highlights the BoT's insistence that the 1% rate is sufficient, while Prachachat notes the central bank's view that inflation remains within a manageable range.
Context & numbers
- Indonesia (BI): Rupiah closed at Rp17,938/USD on Oct 15. 10-year SBN yield projected at 7.15%–7.55%. BI-Rate currently at 5.75%, with hike odds rising for Oct 21. Foreign reserves stand at US$146.3 billion.
- Thailand (BoT): Policy rate held at 1.00%. 10-year Thai bond yield at 2.37%. USD/THB trading narrowly around 33.57.
- Malaysia (BNM): Governor signals readiness to adjust rates. H1 2026 GDP growth was 5.7%.
- Vietnam (SBV): Interbank VND rates fell for short tenors; USD rates rose. USD/VND stabilized as global dollar weakened.
On the radar
- Bank Indonesia Meeting (Oct 21): The central bank's decision on whether to hike rates in response to MSCI pressure and rupiah weakness is the region's key event.
- MSCI Final Decision: Investors are awaiting MSCI's final verdict on Indonesia's market classification, which will determine the extent of long-term foreign equity and bond flows.
- Thai CPI Data: Thailand's upcoming inflation data will be critical for the BoT's next policy stance, as the central bank has indicated it needs more data before moving.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
