
Shipping and Freight Markets: Baltic Dry to Box Rates — 2026-10-01
The Baltic Dry Index slumped to a four-week low this week as capesize rates tumbled amid weaker iron ore demand and ample vessel supply. Container rates fell slightly on the SCFI, while the Panama Canal eased draft restrictions as water levels improved, and Premier Alliance signaled an accelerating return to Suez transits after months of Cape rerouting.
Shipping and Freight Markets: Baltic Dry to Box Rates — 2026-10-01
Top developments
Baltic Dry Index Falls 4.6% to Four-Week Low on Capesize Collapse
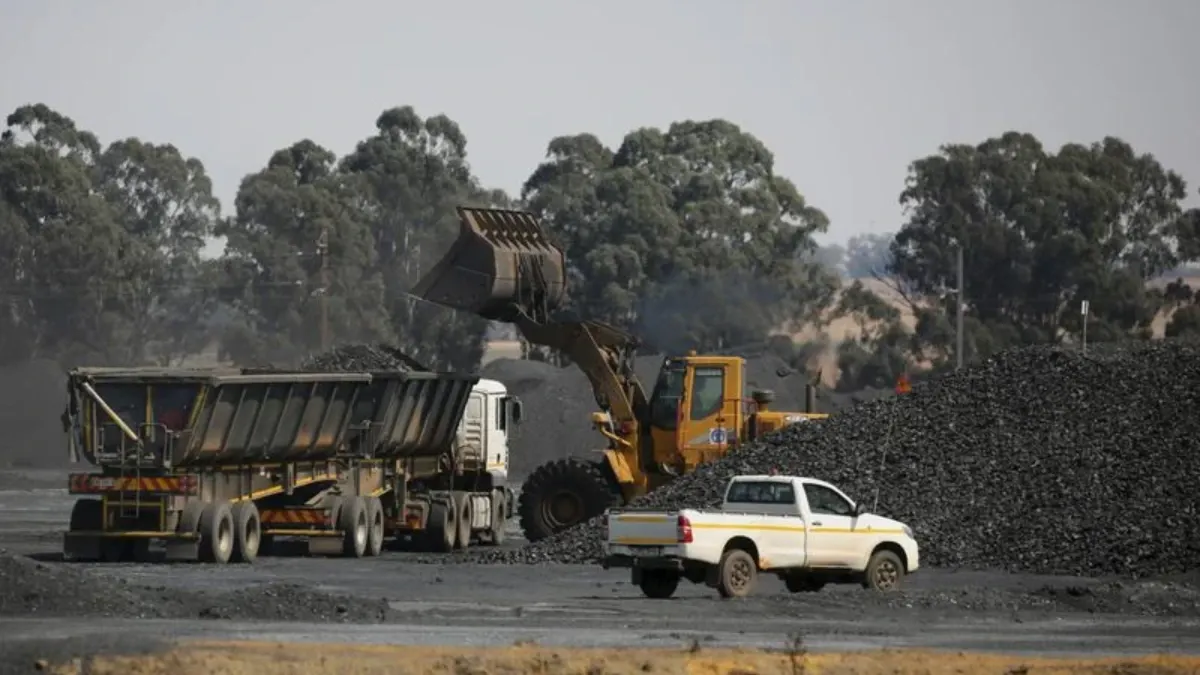
The Baltic Dry Index dropped 4.6% to a four-week low on Monday (Sept 30) as capesize rates fell sharply, dragging the global dry bulk benchmark down from higher levels earlier in the month. The capesize index, which carries 150,000-ton iron ore and coal cargoes, slipped 0.5% to 5,861 points, with average daily capesize earnings declining $286 to $53,155/day. The weakness reflects lower iron ore prices due to ample global supply and softer Australia-China trade activity, exacerbated by China's mid-autumn and October national holidays dampening near-term shipment volumes.
Container Rates Decline 0.65% Week-on-Week as SCFI Retreats
The Shanghai Container Freight Index (SCFI) fell for a second consecutive week, dropping 24.32 points to 3,662.3 points on September 30—a 0.65% weekly decline that marks the end of an eight-week rally. North America and Europe routes weakened, with U.S. lines declining 0.78–1.28% and Europe routes sliding 3.69–3.88%. Industry analysts attributed the retreat to softer demand around Chinese holidays (mid-autumn and National Day break, Sept 24–Oct 8), though North America lines were expected to hold firm into late October as trade negotiations develop. Drewry's World Container Index also fell 1% to $4,434 per 40ft container on October 1.

Panama Canal Raises Draft Limits and Adds Transit Slot as Water Levels Recover
The Panama Canal Authority reversed course on transit restrictions as September rainfall improved water outlook. The canal raised draft limits for the largest container vessels and added one additional daily transit slot, easing congestion after months of tight capacity constraints. This recovery came as El Niño-related water scarcity had previously limited transits to 32 per day. The easing of restrictions removes a significant bottleneck that had pushed carriers toward Cape of Good Hope rerouting during the Red Sea disruptions.

Premier Alliance Joins Accelerating Suez Return, Signaling End of Cape Diversion Era
The Premier Alliance container alliance announced plans to send one of its Asia-Europe service strings back through the Suez Canal this month (October 2026), joining a growing wave of carriers abandoning Cape of Good Hope diversions. This acceleration reflects improving Red Sea security assessments and relief over six months of extended voyage times from the alternate routing. The return to Suez—though still marked by Houthi activity near the Bab el-Mandeb Strait—offers significant time and fuel savings; Cape routing adds roughly 12–14 days and extra fuel burn compared to Suez transit. Container traffic through Suez reached 72.1 million net tons in the first eight months of 2026, confirming steady recovery.

Iron Ore Freight Routes Diverge Sharply; Atlantic Holds While Pacific Weakens
Iron ore freight costs diverged in September: the Tubarao-Qingdao route gained 5.4% to $43/ton, while the key Western Australia-Qingdao route fell 11.1% to $15.95/ton. The split reflects shifting trade patterns as Chinese mills face weaker domestic iron ore output balanced against ample seaborne supply. Capesize overcapacity in the Pacific, combined with lower ore prices and holiday-driven cargo deferral, pressured Pacific rates more than the Atlantic, which saw steadier demand from European mills.
Local view
Greek shipping media reported that bulk carrier spot market rates remain strong despite recent declines, with the fourth quarter traditionally entering a seasonally dynamic period. Nautika Chronika noted that spot rates for dry bulk vessels are holding "particularly strong" levels even as capesize weakness has spread, suggesting resilience in smaller segments (panamax and supramax). The publication highlighted a geographic split: sharp contraction in Black Sea trade (depressing those routes) is being offset by Baltic activity, which remains a counterbalance to broader weakness.
Chinese and Taiwanese analysts flagged that the SCFI retreat is temporary and tied to holiday seasonal patterns rather than structural demand collapse. Chinatimes and UDN analysts predicted North America lines will hold elevated rates through October 31 as trade negotiations extend, with expectations for continued tariff discussions under a potential Trump-Xi trade pause. Oil tanker markets, meanwhile, continue to exhibit "sustained strength," suggesting that energy shipping remains a bright spot.
Context & numbers
| Metric | Latest Value | Change | Source |
|---|---|---|---|
| Baltic Dry Index | ~3,178 points | −4.6% (week) | IndexBox, BusinessUpturn (Sept 30) |
| Capesize Index (BCI) | 5,861 points | −0.5% | Handybulk (Sept 28) |
| Capesize Daily Earnings | $53,155/day | −$286 (−0.5%) | Handybulk |
| Panamax Index (BPI) | 2,333 points | +1.5% (week) | Handybulk |
| SCFI (Shanghai Container Index) | 3,662.3 points | −0.65% (week) | UDN (Sept 30) |
| Drewry World Container Index | $4,434/40ft | −1% (week) | Drewry (Oct 1) |
| East-West (Far East–Europe) | $2,313/TEU | −$112 / −4% | UDN (Sept 30) |
| West-East (US–Asia) | ~7,300–10,500/FEU (range) | Varied | UDN |
| Tubarao–Qingdao (iron ore) | $43/ton | +5.4% (month) | IndexBox (Sept 2026) |
| WA–Qingdao (iron ore) | $15.95/ton | −11.1% (month) | IndexBox |
BDI Composition: Capesize 40%, Panamax 30%, Supramax 30%
Capesize Profitability Context: At $53,155/day current earnings, capesize operators remain well above breakeven (~$20,000/day operating cost) but have retreated from the $60,000+/day highs of September.
On the radar
- October 8 end date of China's National Day holiday: Watch for normalization of booking patterns and cargo flow through Shanghai and other Asian ports; expect SCFI to stabilize or recover modestly after holiday pent-up demand releases.
- North America trade-rate persistence: Market consensus expects U.S. route premiums to hold into late October pending outcomes of Trump-Xi trade discussions; blank sailings and blank sailings from Asia lines remain sparse, suggesting confidence in sustained demand.
- Black Sea route deterioration: Ongoing contraction in Black Sea bulker activity (war spillovers, sanctions) is creating a two-tier market where Atlantic and Baltic routes hold while Eastern European grain/coal routes weaken; monitor for cascading gearless bulker repositioning.
- Red Sea carrier return acceleration: As Premier Alliance and others confirm Suez returns, watch for rapid capacity normalization; if multiple alliances commit to Red Sea in October, tight container slot availability (previously driving surcharges) could ease sharply, pressuring rates further.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
