
Shipping and Freight Markets: Baltic Dry to Box Rates — 2026-10-20
Container spot rates have rebounded, with the Drewry World Container Index rising 3% to $4,485 per FEU as carriers return to the Suez Canal. Meanwhile, dry bulk remains weak with the Baltic Dry Index sliding further due to Capesize declines, and crude tanker rates are retreating from their epic peaks despite high volatility.
Shipping and Freight Markets: Baltic Dry to Box Rates — 2026-10-20
Top developments
Drewry WCI rises as Suez transits recover
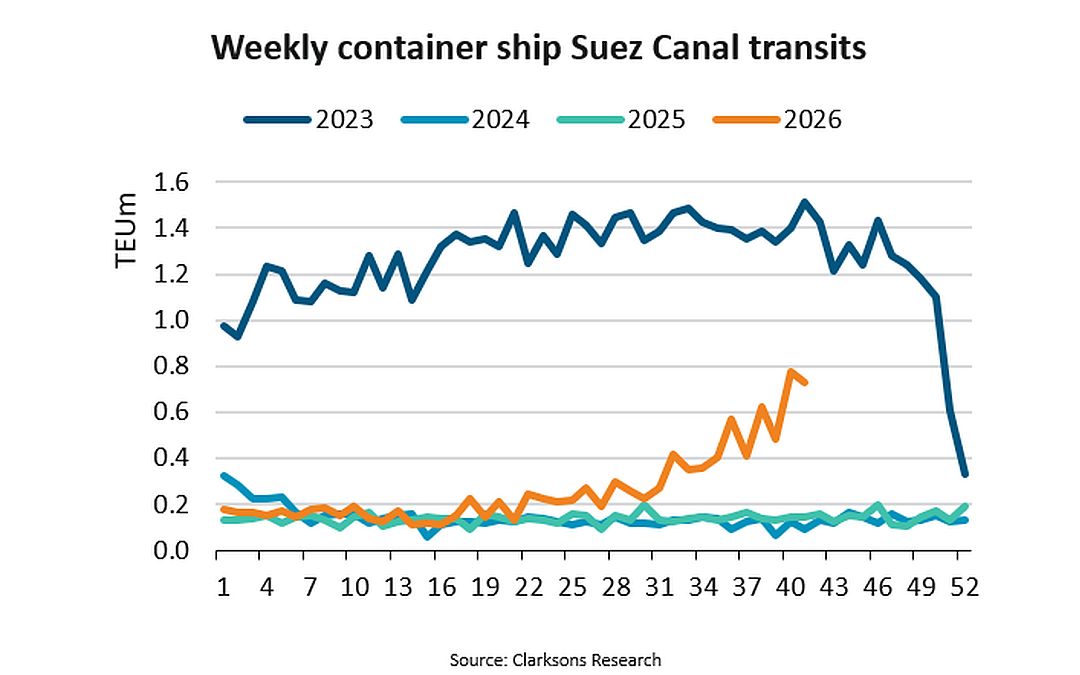
The Drewry World Container Index (WCI) rose 3% to $4,485 per 40ft container on October 15, signaling a stabilization in container spot rates. This increase coincides with a significant recovery in Suez Canal transits, which exceeded 50% of pre-crisis levels for the first time since the Red Sea disruptions began. Data from Clarksons Research indicates that weekly container ship capacity transiting the Suez averaged 753k TEU in the first two weeks of October, compared to 1,457k TEU in the same period of 2023.
Baltic Dry Index slides on Capesize weakness
The Baltic Dry Index (BDI) continued its downward trend, extending losses for a seventh consecutive session as of mid-October, driven primarily by a drop in Capesize rates. The index remained in the "doldrums," with weakness in Capesize vessel rates weighing heavily on the broader market. This persistent softness in dry bulk contrasts sharply with the recovering container markets, highlighting divergent sector performances.

Crude tanker rates retreat from peak
Spot rates for crude tankers have retreated from their "epic peak" as the pace of chartering slows, though they remain significantly higher than pre-crisis levels. Despite the retreat, rates are still down double digits from highs earlier in the month, reflecting market adjustment after the initial shock of geopolitical tensions. Greek media reports highlight that tanker earnings, while high, are facing pressure from a slowdown in transaction volumes and new supply signals.

Local view
Greek shipowners active in newbuild and second-hand markets
Greek shipowners are aggressively pursuing newbuilding orders, with reports of 40 new ships ordered by Greek interests within a 30-day period, representing investments approaching $4 billion. In the second-hand market, Greek owners remain dominant in tankers, recording 98 purchases and 133 sales over the past year. Additionally, COSCO has initiated a new wave of bulk carrier orders to renew its fleet, despite concerns about potential oversupply.
Chinese media tracks SCFI rebound
Chinese media reports indicate that the Shanghai Containerized Freight Index (SCFI) rose 15.47 points to 3,679.58 in the week ending October 16, marking a 0.42% weekly increase. European routes saw a 2.68% weekly rise, while US routes experienced slight declines, reflecting mixed demand across key trade lanes. Analysts suggest that the return to Suez routings is influencing rate expectations, with major alliances evaluating canal transits.

Context & numbers
- Drewry WCI: $4,485 per 40ft container (up 3% week-on-week).
- Suez Canal Transits: 753k TEU weekly average in early October, up from near-zero during peak disruptions, representing >50% of 2023 levels.
- Newbuild Orders: 54 newbuildings reported in the past week, including a large series of ultra-large boxships for Maersk.
- Baltic Dry Index: Extended losses for 7 consecutive sessions as of mid-October, driven by Capesize declines.
On the radar
- Full Suez Return: Container shipping's full return to Suez Canal transits is expected by Q1 2027, with ONE and HMM identified as the next major carriers to resume Red Sea routing.
- Panama Canal Slots: The Panama Canal has expanded its Long-term Slot Allocation (LoTSA) Programme to include both Panamax and Neopanamax locks, allowing carriers to bid for guaranteed slots ahead of the dry season.
- Tanker Supply: Xclusiv Shipbrokers warns of a strong increase in tanker supply from 2027, with the VLCC orderbook at 32.5% of the existing fleet.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
