
Shipping and Freight Markets: Baltic Dry to Box Rates — 2026-09-28
VLCC rates are the story of the week, with Gulf–China round-trip earnings above $1.2 million a day as Iran–Strait of Hormuz tensions keep tanker markets superheated. Dry bulk slipped back from last week's two-year highs, with the BDI down 62 points to 3,445, while container rates eased in both the Drewry WCI and SCFI after long runs of gains. Carriers continue edging back to Suez even as Houthis advance on the Bab el-Mandeb chokepoint.
Shipping and Freight Markets: Baltic Dry to Box Rates — 2026-09-28
Top developments
Tanker earnings stay above $1 million a day
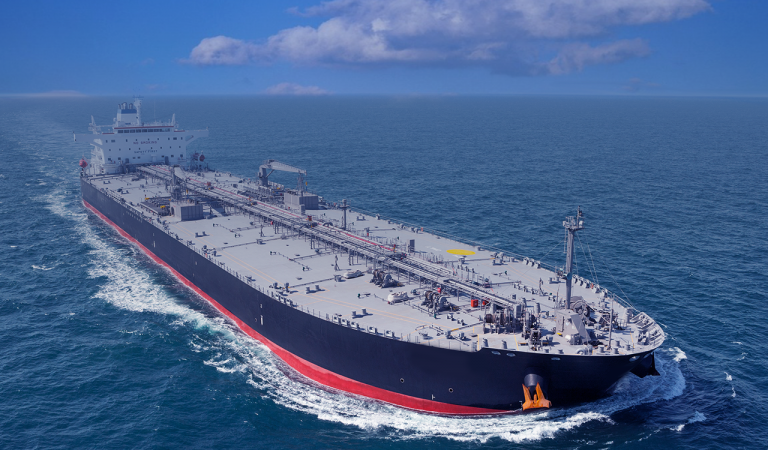
The Baltic Exchange's TD3C route (270,000 mt Middle East Gulf to China) eased only marginally from WS1,165 to WS1,157.5 over the week to Thursday, delivering a daily round-trip TCE of $1,235,414 for a standard Baltic VLCC. Earlier in September the Baltic VLCC TC average had hit roughly USD 722,946/day by 18 September, versus about USD 79,700/day a year earlier. Greek-language media report tanker rates have risen more than 800% in twelve months, with VLCC values up as much as 62%. The driver is geopolitical: disruptions around Iran and the Strait of Hormuz, with rates accelerating since late July.
Dry bulk cools from two-year high
The Baltic Dry Index fell 62 points to 3,445 at the latest reading, with the Baltic Capesize Index down 168 points to 5,912 and capesize average daily earnings off $1,517 to $53,622; the Baltic Panamax Index slipped 14 points. The pullback comes after the index had touched its highest levels since December 2023 earlier in the month. The Baltic Exchange's 25 September weekly report frames the move as a rebound-with-fluctuation story across sectors.
Container rates finally crack after long rally
Drewry's World Container Index fell 1% to $4,468 per 40ft container on 24 September. The SCFI ended an eight-week winning streak on 24 September, slipping 1.21 points to 3,686.62 (−0.03%), with FEU-to-Europe down $112 to $2,313/TEU (about −4%), US routes down 0.78–1.28%, and only Far East–Southeast Asia rates still climbing; Taipei desks attribute the softness to pre-holiday (Mid-Autumn Festival, China Golden Week) volume lulls. Traders still expect US-route rates to stay elevated through October on hopes of an extended US–China trade truce. Separately, the Shanghai-containerized settlement index for the Europe route fell 10.2% to 2,610.55 points as of 21 September.
Carriers keep returning to the Red Sea — risk rising
Carriers are resuming Suez transits even as Houthi forces expand along Yemen's Red Sea coast, a situation the Carra Globe analysis calls a mismatch between commercial normalization and security risk. More container capacity returning to Suez is a bearish signal for spot rates, which is consistent with this week's WCI and SCFI declines.
Local view
Greek shipping media is uniformly focused on the tanker supercycle. Naftika Chronika asks whether there is any ceiling to the freight market, warning that uncontrolled tanker rate rises could inflate delivered crude costs, while also reporting shipyards are selling out repair slots globally as strong demand drives a newbuilding surge. Newmoney details a fresh Greek orderbook push — 14 new ship orders spanning tankers, LNG carriers and ammonia carriers — and notes Greeks sold 650 vessels between 2025 and July 2026, with net fleet outflow of 8.1 million GT, as owners cash in on high asset values. Ot.gr links record VLCC freight to record oil movements and a tanker shortage that threatens to keep fuel prices elevated.
Context & numbers
- BDI: 3,445 (−62); BCI: 5,912 (−168); capesize TCE: $53,622/day
- TD3C VLCC: WS1,157.5; round-trip TCE $1,235,414/day
- VLCC TC average peak ~$722,946/day (18 Sept) vs ~$79,700 in mid-Sept 2025
- Drewry WCI: $4,468/FEU (24 Sept, −1%)
- SCFI: 3,686.62 (24 Sept, −0.03%, first fall in 8 weeks); Europe $2,313/TEU
- Greek fleet: net sales surplus of 120 ships in 2025; 8.1m GT net outflow
- Global newbuilding orderbook at historic dollar peak of 207m CGT / US$657bn; Newbuilding Price Index at 185.15 end-June
On the radar
- China Golden Week (early October) holiday lull: Taiwanese desks expect US-line container rates to hold elevated through end-October on trade-truce expectations — watch the next SCFI prints
- Houthi advance on Bab el-Mandeb chokepoints: a renewed attack campaign could abruptly reverse the Suez carrier return and re-tighten Asia–Europe capacity
- Strait of Hormuz exclusion-zone negotiations (rumored): Iranian plans for a wider exclusion zone remain the key swing factor for VLCC rates
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
