
Softs: Coffee, Cocoa, Sugar and Cotton Daily — 2026-10-31
Sugar prices surged nearly 10% in October amid delayed harvests in Brazil, while robusta coffee fell 6% as Vietnamese supply increased. Arabica coffee hit a one-month low due to improved supply prospects and a weaker Brazilian real, though domestic Brazilian prices remained supported by currency fluctuations. Cocoa markets faced selling pressure from rising ICE inventories, with Ivory Coast producers protesting fixed farm-gate prices.
Softs: Coffee, Cocoa, Sugar and Cotton Daily — 2026-10-31
Top developments
Sugar gains nearly 10% in October despite weekly volatility
Raw sugar futures on ICE No.11 closed the month of October with a gain of nearly 10%, driven by weather-related delays in Brazil’s harvest and concerns over lower production. Although prices dipped earlier in the week due to a stronger Brazilian real and rainfall, they recovered to trade around 19.34 cents per lb. The delayed harvest timeline is a critical factor for global supply chains, as Brazil is the world’s largest producer, and any shift in output timing impacts pricing volatility for the remainder of the year.
Robusta coffee falls 6% as Vietnam harvest accelerates
Robusta coffee prices declined by 6% in October, pressured by the onset of the harvest in Vietnam, the world’s largest robusta producer. Exchange stocks have continued to rise, easing supply tightness that had previously supported prices. In Vietnam, domestic farm-gate prices in the Central Highlands dropped to between 87,000 and 87,500 VND/kg, reflecting this downward trend. This divergence from arabica highlights the specific supply dynamics of the robusta segment.

Arabica hits one-month low on improved supply outlook
Arabica coffee futures on ICE hit a two-and-a-half-week low, losing 1.2% over the month. The decline was attributed to improved supply prospects in Brazil and a weaker Brazilian real, which incentivizes exporters to sell. Despite the drop in international prices, domestic prices in Brazil remained relatively stable due to the currency’s impact on local producers’ income. Certified ICE stocks, while still low, showed signs of moderating drawdowns, with some bags pending grading.
Cocoa weakens on rising inventories and producer disputes
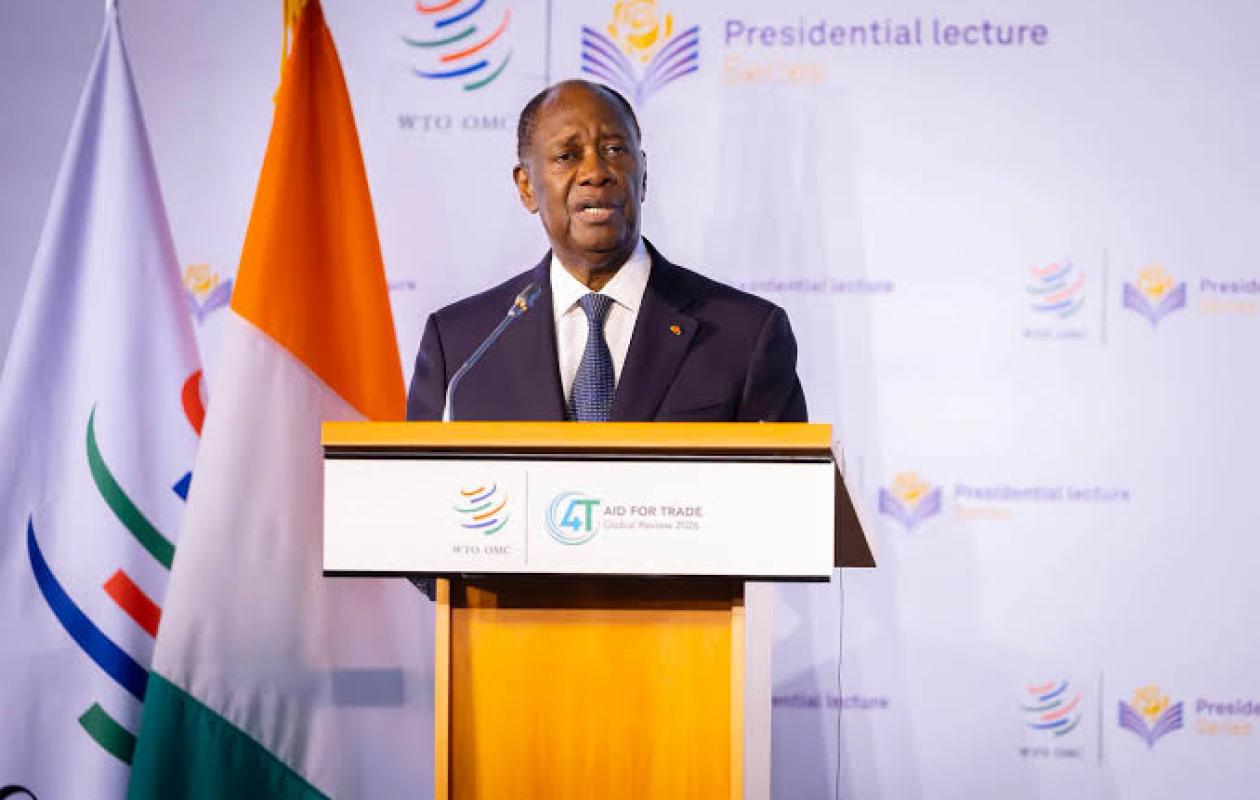
Cocoa prices remained under pressure as ICE-certified inventories rose, signaling a potential easing of the supply crunch that defined earlier months. In Ivory Coast, tensions persist over the fixed farm-gate price of 1,200 FCFA/kg for the 2026/27 campaign. Producer groups in regions like Sikensi have rejected strikes against this fixed price, but broader dissatisfaction remains among those who see private buyers offering higher rates. President Ouattara recently highlighted at the WTO that 41% of cocoa is now processed locally, though data from the Conseil Café Cacao suggests this figure may be closer to 30%.
Local view
In Vietnam, local media reports that domestic robusta prices have fallen below 88,000 VND/kg, with traders citing increased supply from the ongoing harvest in the Central Highlands. Baogialai and Index.vn note that while global robusta prices are adjusting downward, the pace of domestic decline is steady, reflecting local liquidity needs among farmers.
In Brazil, Globo Rural and CNN Brasil highlight that the weakening real is a double-edged sword: it depresses international arabica prices by boosting export competitiveness but sustains domestic prices for farmers. Forbes Brasil notes that sugar prices are rising despite rains in Brazil, as the wet weather is actually delaying the harvest and crushing operations, tightening immediate supply.
In Ivory Coast, Afriksoir reports on a gathering of over 8,000 producers from the SYNAP-CI union, who are questioning the fairness of the 1,200 FCFA/kg fixed price when some buyers are offering up to 1,500 FCFA/kg. This disconnect between state-fixed prices and market realities is causing friction in the cocoa supply chain.
Context & numbers
- Sugar (ICE No.11): +10% in October; trading around 19.34 cents/lb.
- Robusta Coffee (ICE): -6% in October; pressured by Vietnam harvest and rising stocks.
- Arabica Coffee (ICE): -1.2% in October; hit one-month low near 285 cents/lb.
- Vietnam Farm-gate Coffee: 87,000–87,500 VND/kg (Central Highlands).
- Ivory Coast Cocoa Farm-gate Price: Fixed at 1,200 FCFA/kg for 2026/27 campaign.
- Ivory Coast Cocoa Processing: Official claim of 41% local processing (WTO), disputed by CCC data suggesting ~30%.
On the radar
- Brazil Harvest Delays: Continued rainfall in Brazil’s Center-South could further delay sugar cane crushing, potentially extending the bullish trend in sugar prices.
- Vietnam Robusta Peak: As the harvest in Vietnam peaks in November, watch for further downward pressure on robusta futures if export logistics can’t keep pace.
- Ivory Coast Producer Strikes: While strikes were rejected in Sikensi, monitor for unrest in other cocoa-producing regions where the gap between fixed and open-market prices is widest.
- Cocoa Inventories: ICE cocoa stocks remain a key indicator; any further build-up could signal a broader market correction.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
