
Softs: Coffee, Cocoa, Sugar and Cotton Daily — 2026-10-14
Raw sugar futures remain volatile, retreating from a 19-month peak as Brazil's harvest delays persist but global supply concerns ease slightly. Meanwhile, cocoa prices surged to a one-month high on adverse El Niño weather in West Africa, while coffee markets face pressure from record Brazilian exports and a stronger dollar.
Softs: Coffee, Cocoa, Sugar and Cotton Daily — 2026-10-14
Top developments
Cocoa Futures Hit One-Month High on West African Weather Concerns
Cocoa futures on ICE reached their highest level in approximately one month on Tuesday, October 13, driven by adverse El Niño-linked weather conditions in key producing regions. This rally contrasts with the broader soft commodity pullback seen earlier in the week, highlighting the specific supply risks facing West African cocoa crops. The price surge matters for ICE cocoa settlements as traders position for potential yield reductions in the Ivory Coast and Ghana due to the unfavorable climate patterns.

Raw Sugar Retreating From 19-Month Peaks Amid Harvest Delays
Raw sugar futures fell on Thursday, October 9, moving away from the 19-month peak set earlier that week, though they rose again on Monday, October 13. The volatility is driven by conflicting signals: delayed harvesting in Brazil supports prices by tightening immediate supply, while improved rain forecasts and easing fund buying have capped gains. For ICE sugar settlements, this choppy action reflects the market's struggle to balance the delayed Brazilian crush against global crop concerns in India.

Coffee Prices Under Pressure From Record Brazilian Exports and Dollar Strength
Coffee futures, particularly arabica, have faced downward pressure due to a stronger US dollar and progress in Brazil's harvest. September shipments from Brazil rose more than 20%, overshadowing low certified stocks and emerging El Niño risks. This export surge is weighing on ICE coffee settlements, as the market absorbs the increased supply despite fundamental tightness in certified stocks.
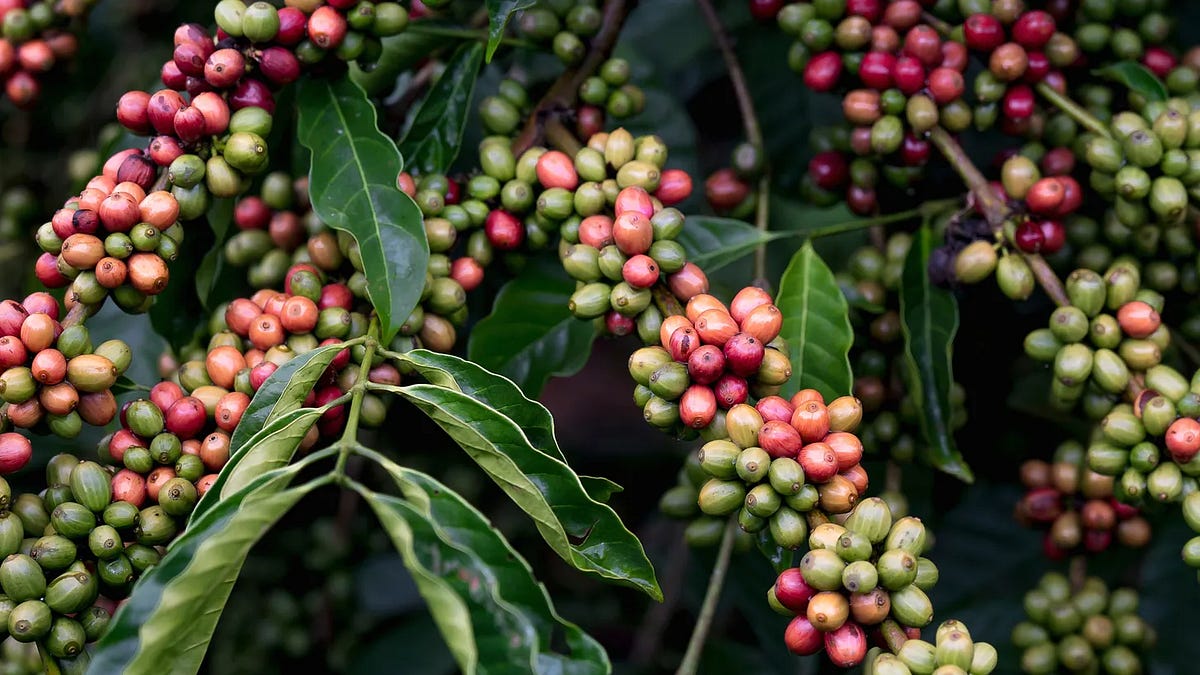
Brazil’s September Coffee Exports Rise 3.1% Despite Lower Arabica Volumes
Brazil exported 3.894 million bags of coffee in September, a 3.1% year-on-year increase, primarily driven by a 65.1% surge in canephora (robusta) exports. However, total revenue fell 7.1% to US$ 1.282 billion, indicating lower average prices or a shift in product mix. This data is critical for assessing the volume of Brazilian coffee hitting global markets, directly influencing ICE robusta and arabica price expectations.

Local view
Vietnam: In the Central Highlands (Tây Nguyên), domestic coffee prices rose slightly to 92,500–93,200 VND/kg on October 14. Local media notes that while global robusta prices dipped, arabica gains and concerns over Colombian supply have supported domestic sentiment. Farmers are preparing for the new harvest, with trading activity described as "moderate" but showing signs of improvement compared to the previous week's stagnation.

Ivory Coast: The Conseil Café-Cacao officially launched the main 2026-2027 campaign in the Bélier region on October 13. The farm-gate price remains fixed at 1,200 FCFA/kg for cocoa and 1,300 FCFA/kg for coffee. Local stakeholders are concerned about competition from Ghana, where prices are higher, leading to reports of retention strikes and cross-border smuggling. Banque Atlantique has also engaged with sector actors to support financing for the new campaign.
Context & numbers
- Brazil Coffee Exports: September volume was 3.894 million bags (+3.1% YoY); revenue was US$ 1.282 billion (-7.1% YoY). Canephora exports jumped 65.1%.
- Ivory Coast Farm-Gate Prices: Cocoa at 1,200 FCFA/kg; Coffee at 1,300 FCFA/kg for the 2026-2027 campaign.
- Vietnam Domestic Coffee: Prices in Tây Nguyên ranged from 92,500 to 93,200 VND/kg on October 14.
- Sugar Market: NY Sugar #11 (SBH27) and London White Sugar #5 (SWZ26) showed mixed closes on Wednesday, following a 19-month high for NY sugar and a 22-month high for London sugar earlier in the week.
On the radar
- El Niño Impact: Continued monitoring of El Niño-linked weather patterns in West Africa and Brazil, which are currently driving cocoa rallies and affecting sugar harvest timing.
- Colombian Supply: Emerging concerns over declining Colombian coffee supply are supporting arabica prices, offsetting some pressure from Brazilian exports.
- Fund Positioning: Heavy fund positioning in sugar raises liquidation risks if prices fail to sustain recent highs, according to ADM Investor Services.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
