
UK Gilts and the Bank of England — 2026-09-15
On 15 September, reports said the Bank of England may halt active sales of 20- and 30-year gilts as the bond sell-off pushed 10-year yields to 5.41% and 30-year yields to 5.93%. The story is reinforced by fresh DMO auction listings and by economists urging Chancellor John Healey to press the BoE to slow bond-selling that is described as costing the exchequer billions.
UK Gilts and the Bank of England — 2026-09-15
Top developments
BoE reported to halt long-term gilt sales
On 15 September, The Telegraph reported that the Bank of England plans to overhaul debt operations amid bond-market turmoil, with the move said to be able to save billions as Britain faces its highest borrowing rates in more than 25 years. Business Recorder and Investing.com carried the same report, specifying that the BoE would stop selling 20- and 30-year gilts, while Global Banking & Finance said the announcement was expected on Thursday. For the daily gilt wrap, cutting official long-dated sales is the most direct supply-side lever discussed in the fresh sources, because EBC said the maturity mix and active sales are central to long-end yields.

Long-end yields climb toward 6%
Guido Fawkes reported on 15 September that 10-year gilt yields had climbed to 5.41% and 30-year gilts to 5.93%, adding that gilts were taking a heavier beating than most continental bonds. The same market wrap gave 10- and 30-year figures but not a fresh 2-year yield, leaving the long end as the main visible stress point. The supplied sources did not quantify pension LDI demand, so the long-end story rests on reported BoE sales, global selling pressure and the absence of fresh demand data.
Economists urge Healey to press BoE on bond-selling
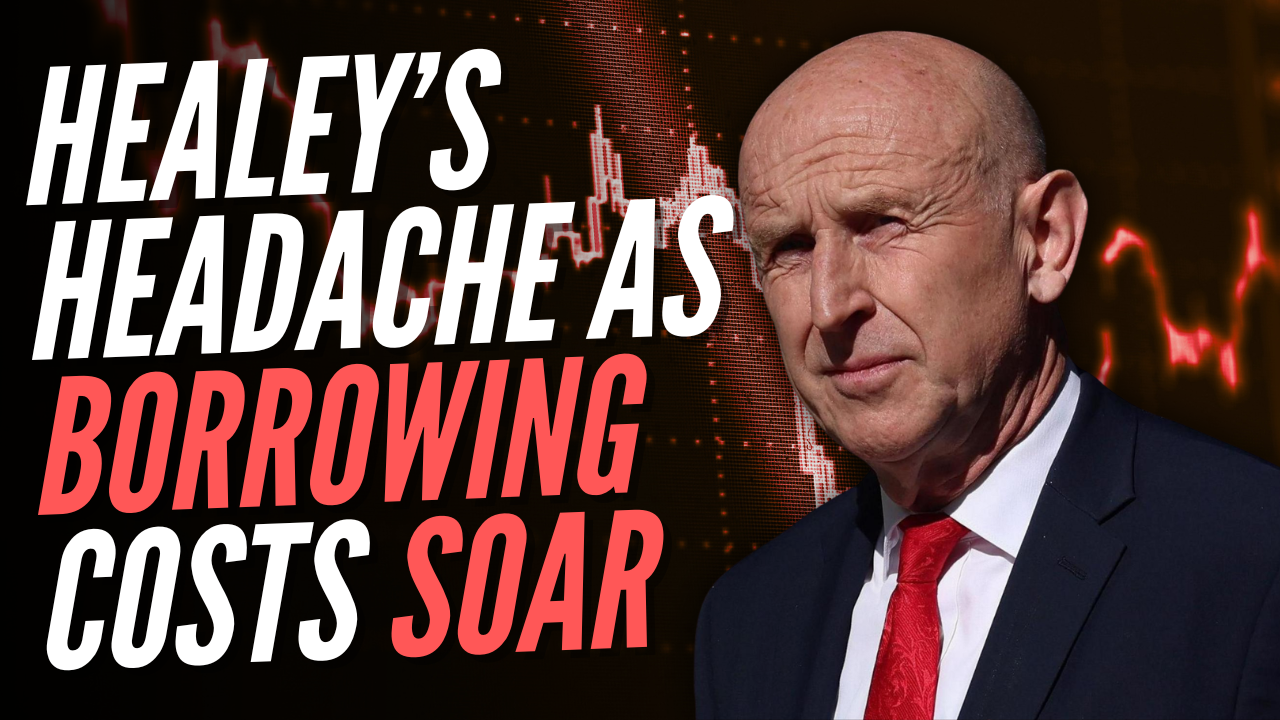
The Guardian reported on 15 September that economists urged Chancellor John Healey to press the Bank of England to slow or halt bond-selling, arguing the policy is costing the exchequer billions of pounds. That links balance-sheet runoff directly to gilt supply and government funding costs, because the active sales discussed in the fresh reports are concentrated in longer maturities. With OMFIF describing the October budget as a moment when Healey must reconcile spending plans with fiscal rules, the QT debate is becoming a fiscal credibility issue as well as a monetary-policy issue.

DMO auction flow continues while syndication detail is thin
The DMO website listed the result of a sale-by-auction of £5,000 million of 4⅝% Treasury Gilt 2030 on 10 September 2026. Investing.com separately reported on 15 September that the UK sold £1.25 billion of treasury gilts maturing in 2029. The supplied snippets did not include bid-to-cover, tail or fresh syndication results, so the immediate auction takeaway is the size and maturity of official supply rather than demand quality.

QT expectations move to the foreground
EBC Financial Group reported on 15 September that the BoE may cut annual quantitative tightening to £50 billion while active gilt sales stay near £20 billion, putting maturity mix and long-end yields in focus. France Epargne framed the upcoming 17 September BoE decision as a hold at 3.75% with QT expected around £50 billion. The post-8 September sources reviewed here did not publish a new MPC vote tally, so the fresh policy signal is the expected runoff mix rather than a newly disclosed voting split.
Local view
German-language Investing.com reported that Goldman Sachs raised its gilt yield forecasts because energy prices were dampening hopes for rate cuts. The same outlet said Citigroup expected Bank of England rate increases from 2026, pointing to a hawkish shift in analyst expectations. French-language France Epargne presented the BoE meeting as a likely hold at 3.75% and a QT pace near £50 billion, tying UK bond supply to European rate expectations. German-language Euronews placed the UK move in a global bond sell-off, noting the 10-year US Treasury yield briefly rose to 5.011%. Liz Truss posted on X that gilts were “almost at 6%” and that the Bank of England “never managed to achieve that” in her era.
Context & numbers
- 10-year gilt yield: 5.41% on 15 September.
- 30-year gilt yield: 5.93% on 15 September.
- 2-year gilt yield: no fresh 2-year print was included in the supplied post-8 September sources.
- DMO auction: £5,000 million 4⅝% Treasury Gilt 2030 result listed for 10 September 2026.
- DMO sale: £1.25 billion of treasury gilts maturing in 2029 reported on 15 September.
- BoE QT: annual quantitative tightening may fall to £50 billion while active gilt sales stay near £20 billion, according to EBC.
- Bank Rate expectation: France Epargne framed the 17 September BoE decision as a hold at 3.75%.
- Sterling: GBP/USD closed just beneath 1.3500 on Monday, 0.19% lower, after touching its lowest level since 14 August.
- Fiscal backdrop: OMFIF argued that the UK fiscal rules do not work and that Chancellor John Healey must reconcile higher spending with credibility ahead of the October budget.
- Pension LDI demand: no fresh LDI positioning or demand data was provided in the supplied sources.
On the radar
- Thursday 17 September: Global Banking & Finance said the BoE debt-sales overhaul is expected to be announced Thursday, and France Epargne pointed to the BoE decision date as 17 September.
- 22 September: Steve Baker noted the next ONS public finances release is due on 22 September, a date that will matter if gilt yields feed into borrowing costs and debt-service estimates.
- End of October: OMFIF said Chancellor John Healey is due to deliver the first budget of the Burnham government at the end of October, making the long-end yield path a fiscal risk.
- DMO notices: Watch for the next auction or syndication announcements and any revised maturity mix after the reported BoE halt to 20- and 30-year gilt sales.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
