
Volatility and Derivatives: VIX, 0DTE and Structured Notes — 2026-10-16
Global volatility markets faced severe stress this week as a sharp AI-driven selloff triggered the worst hedge fund losses since August and pushed the Nikkei Volatility Index (VI) to two-month highs. In Korea, ELS investors faced early redemption failures amid market turbulence, while US dealers grappled with shifting gamma dynamics as inflation data surged.
Volatility and Derivatives: VIX, 0DTE and Structured Notes — 2026-10-16
Top developments
Hedge funds suffer synchronized losses as AI trade unwinds
Hedge funds experienced their worst single-day performance since August as the AI stock selloff deepened, causing synchronized losses across quant, tech, and Asia-focused strategies. Asia-focused stock pickers were hit hardest, losing 6.8% in early October, while global fundamental long-short funds fell 2.9%. This unwind has significantly impacted dispersion trades and increased demand for downside protection, altering the typical correlation assumptions used in structured product pricing.
Nikkei VI spikes on AI bubble fears and PPI shock
The Nikkei Average Volatility Index (Nikkei VI) surged to its highest level in two months on October 15, driven by accelerating US inflation data and renewed concerns over an AI investment bubble. The index rose sharply after the Nikkei 225 dropped nearly 5%—the third-largest daily decline in history—triggering margin calls and hedging flows that amplified the move. Local media noted that the "AI bubble" narrative is now a primary driver of short-term volatility expectations in Japanese derivatives markets.
Korean ELS early redemptions fail amid KOSPI200 volatility
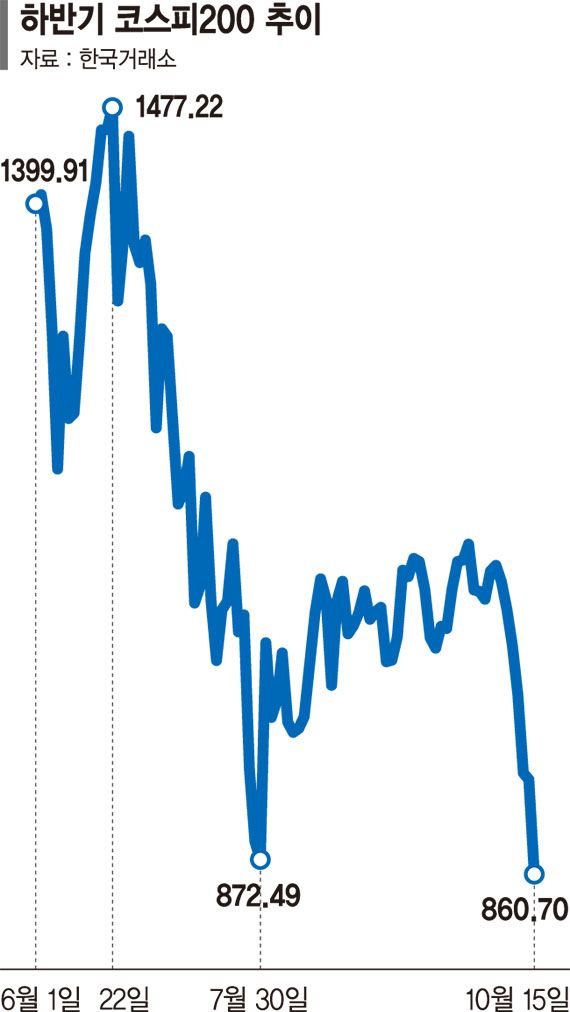
In Korea, approximately 4.4 trillion won worth of Equity-Linked Securities (ELS) issued during recent market highs are facing early redemption failures due to KOSPI200 declines. Financial News reported on October 15 that investors are unable to recover funds as underlying assets failed to meet redemption conditions, creating liquidity pressure for issuers. This highlights the growing risk in the Korean structured notes market, where 85% of ELS issuance is tied to the KOSPI200, exposing domestic retail investors to concentrated index risk.
Hot PPI data disrupts dealer gamma positioning
US stocks slipped early on October 16 after September headline PPI increased 1.3%, the second-largest rise ever recorded, with core PPI posting its biggest gain in four years. This inflation surprise has shifted dealer gamma exposure, potentially moving markets from a positive gamma regime (where dealers buy dips/sell rallies) to negative gamma, which amplifies price moves. Traders are now reassessing 0DTE option flows as the term structure adjusts to higher near-term volatility expectations.

Local view
Japan: Zaikei Shimbun and Yomiuri Shimbun emphasize that the Nikkei VI spike is directly linked to "AI bubble" anxieties and US inflation data, noting that the fear gauge's sharp rise reflects genuine institutional hedging rather than just retail panic.
Korea: Financial News reports that the failure of early redemptions for 4.4 trillion won in ELS products is causing significant investor distress, with local media highlighting the concentration risk in KOSPI200-linked structures.
Context & numbers
- Nikkei VI: Surged to a two-month high on Oct 15, 2026, following a ~5% drop in the Nikkei 225.
- KOSPI200 Futures: The December contract traded at 870.15 on Oct 16, up more than 1% from the previous day's spot close of 860.70, indicating potential stabilization or hedging adjustments after the crash.
- Hedge Fund Performance: Asia-focused stock pickers lost 6.8% in early October; global long-short funds lost 2.9%.
- US PPI: September headline PPI +1.3% MoM; core PPI saw its largest gain in four years.
On the radar
- Election Day Volatility: The October VIX futures contract settles on Oct 21 but covers a window extending to Nov 20, which includes the Nov 3 Election Day, keeping near-term volatility elevated.
- Structured Note Unwind: Monitor Korean financial regulators for potential intervention or guidance regarding the wave of ELS early redemption failures.
- Margin Call Feedback Loops: Watch for secondary margin calls in Japan if the Nikkei VI remains elevated, particularly among leveraged retail traders exposed to AI-linked equities.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
