
Volatility and Derivatives: VIX, 0DTE and Structured Notes — 2026-10-09
Cboe is exploring perpetual futures for the VIX, introducing a crypto-style trading mechanism to Wall Street's primary fear gauge. In Asia, South Korea’s structured product exposure hit a three-year high of ₩96.7 trillion, while Japan’s Nikkei Volatility Index (VI) fluctuated sharply as equity markets cooled from recent highs.
Volatility and Derivatives: VIX, 0DTE and Structured Notes — 2026-10-09
Top developments
Cboe Proposes Perpetual VIX Futures
On October 2, 2026, reports emerged that Cboe is considering "no-expiry" or perpetual futures contracts for the VIX. This concept, originally proposed by economist Robert Shiller in 1993 and popularized by the crypto industry, would allow traders to maintain volatility positions without the friction of rolling expirations. If approved, this structural change could significantly alter how institutional investors hedge tail risk and manage vol exposure, potentially reducing the mechanical buying pressure associated with monthly roll dates.

Bond Volatility Diverges from Equities
As of October 6, 2026, macro observers noted a divergence where bond market volatility metrics are rising while equity indices remain calm. The "VIX of bonds" is signaling stress that has not yet translated into elevated stock market fear, with Bitcoin and US stocks showing little reaction to the underlying fixed-income turbulence. This disconnect suggests that equity volatility models may be underestimating systemic risk if bond yields continue to destabilize.

Korean Structured Products Hit 3-Year High
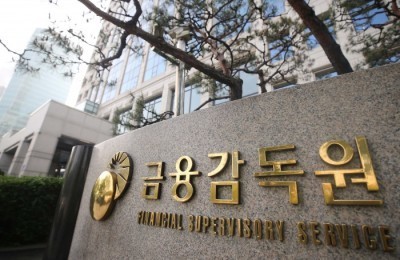
South Korea’s outstanding balance of derivative-linked securities (ELS and ELBs) reached ₩96.7 trillion in the first half of 2026, marking the highest level since June 2023. The Financial Supervisory Service reported on October 1 that issuance increased 21.2% year-over-year, driven by strong demand for ELS products tracking semiconductor stocks like Samsung Electronics and SK Hynix. With KOSPI200 weighting at nearly 85%, this concentration creates significant knock-in risk should tech volatility spike.
Nikkei VI Spikes Then Cools Amid Equity Pullback
The Nikkei Average Volatility Index (Nikkei VI) hit a two-month high on October 7, 2026, before falling sharply by October 8 as the Nikkei 225 declined. The rapid rise in VI reflected overheated sentiment during a pitch-fast rally in Japanese equities, which subsequently cooled. This volatility whipsaw highlights the sensitivity of Japanese derivatives markets to global risk sentiment shifts, particularly as investors navigate the Bank of Japan's upcoming policy decisions.
Local view
South Korea: Local media, including Maeil Business Newspaper and News Pim, are warning of "principal loss alarms" for semiconductor-focused ELS products. Analysts note that while early redemptions have surged due to stock market highs, the sheer volume of new issuance (₩7.6 trillion in Q3 alone) leaves retail investors exposed if memory chip stocks correct more than 35% within their 3-year terms.
Japan: Fisco and Zaikei Shimbun report that the Nikkei VI is acting as a leading indicator for local equity corrections. Commentary suggests that the recent drop in VI following a price decline indicates that panic selling has subsided, but traders remain cautious ahead of the BOJ meeting, keeping a "wait-and-see" stance on options positioning.
Context & numbers
- Korea ELS Balance: ₩96.7 trillion (approx. $70B USD equivalent), highest since June 2023.
- Korea Issuance Growth: +21.2% YoY for ELS; +28.8% YoY for ELBs in H1 2026.
- Nikkei VI Movement: Reached a 2-month high on Oct 7, then declined significantly on Oct 8 as the Nikkei 225 fell.
- VIX Structure: Cboe is actively evaluating perpetual futures to replace traditional term-structure rolling mechanisms.
On the radar
- BOJ Policy Decision: Japanese derivatives traders are bracing for potential volatility spikes around the upcoming Bank of Japan announcement, with Nikkei VI remaining sensitive to yen carry trade adjustments.
- Korean ELS Maturity Walls: Monitor for cluster maturities in semiconductor-tracking ELS products; a sharp drop in Samsung Electronics or SK Hynix below knock-in barriers could trigger forced selling and amplify downside volatility.
- Cboe Regulatory Filings: Watch for formal SEC filings regarding the proposed perpetual VIX futures, which could redefine volatility hedging strategies globally.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
